Does History Operate on a Long Fuse? Evidence from Isaac Bashevis Singer

Isaac Bashevis Singer’s The Manor orbits two Polish rebellions (1830 and 1863).

Author’s Note to the Original Edition

The Manor was written between 1953 and 1955. As with many of my stories and all my novels (with the exception of Satan in Goray, which I wrote while still in Warsaw), it was first serialized in The Jewish Daily Forward. Although The Manor was published many years after The Family Moskat, it portrays an earlier period—the epoch between the Polish insurrection of 1863 and the end of the nineteenth century. It was the era of gas lamps, the time when the Poles had finally become resigned to their loss of independence and turned to a kind of national positivism. Poland now began to emerge as an industrial country; railroads were built, factories were opened, and the cities grew rapidly. The Jews, who until 1863 for the most part still lived in a ghetto atmosphere, now began to play an important role in Polish industry, commerce, the arts and sciences. All the spiritual and intellectual ideas that triumphed in the modern era had their roots in the world of that time—socialism and nationalism, Zionism and assimilationism, nihilism and anarchism, suffragettism, atheism, the weakening of the family bond, free love, and even the beginnings of Fascism.

The Estate, a sequel to and the conclusion of The Manor, ends in the last years of the nineteenth century—an epoch when humanism undertook to practice what it had preached for generations. What happened in the village of Jampol, and what was discussed by a small group of self-educated youths in furnished rooms in Warsaw, became the basis of the social upheavals and the terrible disillusions of our present time.

Isaac Bashevis Singer. The Manor. Avon Books, 1979.

If you look at his sentence above describing “All the spiritual and intellectual ideas”, you may start to see what we describe as the long fuse of history. When we are in the present, a lot of the issues from the past emerge again in the future. Reality is such that there is no permanent yesterday.

The novel is also haunted by another kind of deep change, the rise of the world market or globalization.

The novel’s protagonist, Jacoby, acquires a hill, which allows him to begin his fortune with a quarry:

The peasants complained that the Jew was contaminating the Polish countryside, putrefying the air, but the authorities ignored them. Poland, after the insurrection, was full of activity, as if awakened from a long slumber. Workshops sprang up, mines were dug, forests cut down, and railroads built. Polish products, textiles, leather goods, brushes, sieves, sheepskin coats, glassware appeared on the world market. As soon as the Jews were granted permission to reside freely in the cities, the country began to grow.

It was said that Calman had been blessed by a holy man. A building boom was in progress, and his lime quarry yielded immense profits. Scores of Jews and Gentiles earned their livelihood from it. Calman purchased horses and wagons and built a smithy. As if all this were not enough, the Russian government decided to build a railway line through Jampol. …

Isaac Bashevis Singer. The Manor. Avon Books, 1979. p. 9.

Accompanying the rebellions and the commerce are a set of perpetual questions that have yet to be definitively answered.

Does a live carp suffer agonies when it is scaled and cut to pieces for the Sabbath meal? Why are some people poor and others rich? What was there before the universe? Does a goat have a soul? Was Adam a Jew? Did Eve wear a bonnet? And he was constantly finding contradictions in the Holy Writ, pointing out that in one place it is stated that a man is punished only for his own sins, but in another, that the third and fourth generations must suffer for them; and first the Lord is said to be invisible, then it is written that the elders while they ate and drank saw the Lord. For another thing, Ezriel criticized the prophet Elisha for causing the children to be attacked by bears; the boy felt bitterly reproachful toward King David for slaying Uriah the Hittite, and he wept and blasphemed when he read how Abraham sent his concubine Hagar into the desert with nothing but a jug of water, and how she almost perished of thirst.

Isaac Bashevis Singer. The Manor. Avon Books, 1979. pp. 23-24.

Consider specifically the question of what was before the universe. Today our greatest cosmologists and physicists continue to ask this very question. This confirms a famous quote from William Faulkner, “The past is never dead. It’s not even past.”

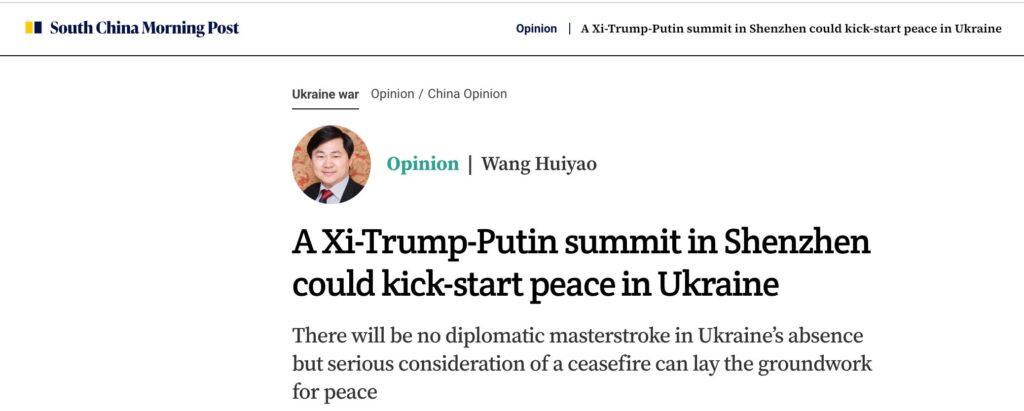
Henry Huiyao Wang: A Xi-Trump-Putin summit in Shenzhen could kick-start peace in Ukraine

CCG’s President says there will be no diplomatic masterstroke in Ukraine’s absence, but serious consideration of a ceasefire can lay the groundwork for peace

[from the Center for China & Globalization, 31 October 2026]

Below is the latest opinion column by Henry Huiyao Wang, founder and President, Center for China and Globalization, published in the South China Morning Post.

At the recent Valdai Discussion Club, I asked Russian President Vladimir Putin if he would be open to meeting Chinese President Xi Jinping and U.S. President Donald Trump at the Asia-Pacific Economic Cooperation (APEC) forum in Shenzhen. I also asked, more broadly, what role China could play in promoting peace in Ukraine, mediating and contributing to peacekeeping.

Putin was receptive, warmly welcoming the idea of a China-hosted meeting. Trump, too, has expressed a willingness to meet Xi and Putin. These expressions of openness offer an opportunity we must seize in pursuit of peace.

Some in the United States and Europe question the value of such a summit. They may fear restoring Putin’s standing or normalising the conflict without yielding any real progress towards an end to the war. That risk is still real but these largely Western fears must be tempered by the very real, very human cost of letting the war continue unabated.

From the very beginning of the war, I have been arguing that China has a constructive role to play. In March 2022, less than three weeks into Russia’s invasion, I wrote an article in The New York Times titled “It’s Time to Offer Russia an Offramp. China Can Help With That.”

In August last year, I extended that train of logic in Foreign Policy, where I proposed a seven-party format for peace negotiations and suggested that a peacekeeping force include troops from European and BRICS countries. A meeting of the three leaders in Shenzhen could help lay the groundwork for these broader diplomatic and peacekeeping efforts.

Without Ukraine’s participation, such a meeting is unlikely to produce a diplomatic masterstroke that ends the war. But the three leaders need not put the war to rest at a table in Shenzhen to make progress. Serious consideration of a ceasefire along the current line of contact—an approach Ukrainian President Volodymyr Zelenskyy has supported—could give peace efforts fresh momentum, leaving the final status of disputed territories for subsequent negotiations.

Further agreement could be sought on the protection of nuclear facilities, or a mutual end to strikes on energy infrastructure, new prisoner exchanges or improved humanitarian access. Of course, issues of sovereignty, security guarantees, Russia’s security concerns and Europe’s security commitments would remain. But these need not all be resolved at once before a ceasefire can begin.

Already, years of war have inflicted immense suffering on both Russia and Ukraine. Neither side achieved its objectives, and both need a dignified way out that protects their core interests. Thus, we must open a path towards peace without requiring either side to concede defeat. China could help bridge this gap by bringing Xi, Trump and Putin together in Shenzhen to explore how a ceasefire and wider negotiations involving Ukraine might work.

The United Nations could stand at the core of such an arrangement by monitoring any ceasefire and preventing a return to fighting by physical peacekeeping if the parties are so inclined.

For a broader negotiation on settlement, I find myself returning to a seven-party format that would bring together the five permanent members of the UN Security Council—China, France, Russia, Britain and the U.S.—alongside Ukraine and the European Union. An understanding reached in Shenzhen could give momentum to this broader negotiating process and free up the Security Council for action.

A peacekeeping force composed entirely of NATO or European troops might be unacceptable to Russia. Yet a mission without European participation would struggle to reassure Ukraine and its neighbours. Any workable arrangement would need to address both concerns.

In my Foreign Policy article, I proposed a peacekeeping force drawing troops from five European countries—Germany, France, Britain, Poland and Italy—and five members of the BRICS grouping, such as China, India and Brazil. And while the exact formulation, from the composition and mandate to the terms of deployment, would need to be negotiated with the consent of Russia and Ukraine, and the agreement of the contributing countries, the core idea remains sound.

As a permanent member of the UN Security Council and the largest contributor of peacekeeping personnel among the five permanent members, China is well positioned to help. Its distinctive role in the global economy and dialogue with Russia, Ukraine, the U.S. and Europe, give it channels through which to coax the parties towards peace. But this process must begin somewhere, and that somewhere could be Shenzhen.

Nor should APEC be the end of the diplomatic effort. With an understanding reached by the leaders in Shenzhen, the Security Council may pick up the momentum by advancing ceasefire and peacekeeping proposals. The Group of 20 could then join the effort to rally support from major economies with an interest in maintaining the deal. Each would play a different role and would not be tasked with settling the entire conflict.

China’s role in the Saudi Arabia-Iran rapprochement in 2023 showed Beijing’s ability to open a door after years of enmity. The Ukraine war is different, and there can be no guarantee of a similar outcome. But diplomacy must begin somewhere, particularly when fighting has brought such destruction.

The central question is whether such a meeting could help bring the war to an end. In that light, any gain in prestige for an individual leader is almost irrelevant. And if the three leaders could agree on practical steps towards peace, they would give the United Nations and the wider international community a material basis upon which peace could be built.

World-Watching: PONARS Eurasia—In the News

[from George Washington University’s Institute for European, Russian and Eurasian Studies/PONARS Eurasia, 8 September 2025]

Robert Orttung, Debra Javeline, Graeme Robertson, Richard Arnold, Andrew Barnes, Edward Holland, Mikhail Troitskiy, Judyth Twigg, and Susanne Wengle argue that the renewed U.S.–Russia alignment under Trump and Putin prioritizes fossil fuel development over climate action, and undermines international climate negotiations.

Read the full article [archived PDF].

In a statement to The Kyiv Independent, Peter Rutland echoes the contrast between the West’s diplomatic quarantine of Russia and the possibility of implementing policies without its permission, articulating how differing attitudes between Europe and Putin discourage any kind of escalation. In her recent article, Margarita Zavadskaya explores the “White Coat” narrative, explaining the origin and manipulation of Russian attitudes towards those who have left.

Read the Rutland article / read the Zavadskaya article [archived PDF].

In a recent interview, Volodymyr Dubovyk explains why he believes Putin “wins” the Alaska summit, sharing his perspective on the meeting’s implications and concluding that the dynamics of peace negotiations shift somewhat. Richard Arnold marks the Donbas’ significance, stating that Russian control of the “Fortress Belt” enables havoc on all areas to the west.

Read the Dubovyk interview / read the Arnold article.

Ryhor Nizknikau speaks with TVP World, interpreting the significance of Ukrainian Parliamentary Speaker Parubiy’s assassination. Tymofii Brik’s recent study, together with Oleksii Sereda, Anna Kokoba, and Alina Shmaliuk, appears in Vox Ukraine, covering the participants and reasoning behind the protest against the bill to limit SAPO and NABU’s independence.

Watch the Nizknikau interview / read the Vox Ukraine article.

In the context of Russia’s recent nuclear developments near the Pan’kovo testing range, Pavel Podvig comments that “Skyfall”, the new weapon’s NATO nickname, has likely undergone testing already. During an interview with DW News, Mikhail Alekseev addresses the goals pursued by the Sino-Russian partnership, which range from the tangible benefits of constructing gas infrastructure to the more ideological advantage of presenting an alternative to the U.S.-led world order.

Read the Podvig article / watch the Alekseev interview.

Why Is the World So Nightmarish?

The phrase, “La Belle Époque” (French: “The Beautiful Era”) refers to the atmosphere in Europe and especially France, the high point of which lasted from 1900 to 1914, with the outbreak of World War I. The whole era was characterized by the phrase, “la douceur de la vie” (French: “the sweetness of life”). People of the time would say that if you weren’t alive then, they could not communicate how charming life was at the time.

The sinking of the Titanic in April, 1912 is the symbolic catastrophe that heralded the end of the era. Anyone who watched Downton Abbey would perhaps remember the opening scene, which depicts the newspaper announcing it with a screaming headline.

The great masterpiece, Journey to the End of the Night (French: Voyage au bout de la nuit, 1932), describes the whole world around World War I as a nightmarish battlefield of previously unseen scope. Céline’s protagonist, Ferdinand, travels the world, from battles in Europe to Africa, then to New York and Detroit’s Ford assembly line before returning to France, finding that the nightmare is global and inescapable.

Céline died within 24 hours of Ernest Hemingway. Hemingway is famous for the quote from The Sun Also Rises (set in the 1920s), “The world breaks everyone and afterward many are strong at the broken places. But those that will not break it kills.”

The question is how could we ever explain complete evaporation of the sweetness of life and transformation into such a nightmare, culminating into the world of today.

Lastly, think of the point made in Sebastian Haffner’s The Meaning of Hitler, how Hitler fit into this nightmarization of the world. Haffner writes:

It is impossible for a serious historian to maintain that without Hitler world history in the twentieth century would have taken the course it has taken. It is by no means certain that without Hitler a second world war would even have taken place; it is quite certain that if it had taken place it would have taken a different course — possibly even with different alliances, fronts and outcomes. Today’s world, whether we like it or not, is the work of Hitler. Without Hitler there would have been no partition of Germany and Europe; without Hitler there would be no Americans and no Russians in Berlin; without Hitler there would be no Israel; without Hitler there would be no de-colonization, at least not such a rapid one; there would be no Asian, Arab or Black African emancipation, and no diminution of European preeminence. Or, more accurately, there would be none of this without Hitler’s mistakes. He certainly did not want any of it.

(The Meaning of Hitler, Harvard University Press, 1979, page 100)

No-one has yet captured how the nightmarish feeling of 2025 is itself downstream from the preceding era.

Economics-Watching: “Doing Nothing” Is Still Doing a Lot

[from the Federal Reserve Bank of Philadelphia, speech by Patrick T. Harker President and Chief Executive Officer at the National Association of Corporate Directors Webinar, Philadelphia, PA (Virtual)]

Good afternoon, everyone.

I appreciate that you’re all giving up part of the end of your workday for us to be together, if only virtually.

My thanks to my good friend, Rick Mroz, for that welcome and introduction.

I do believe we’re going to have a productive session. But just so you all know, as much as I enjoy speaking and providing my outlook, I enjoy a good conversation even more.

So, first, let’s take a few minutes so I can give you my perspective on where we are headed, and then I will be more than happy to take questions and hear what’s on your minds.

But before we get into any of that, I must begin with the standard Fed disclaimer: The views I express today are my own and do not necessarily reflect those of anyone else on the Federal Open Market Committee (FOMC) or in the Federal Reserve System.

Put simply, this is one of those times where the operative words are, “Pat said,” not “the Fed said.”

Now, to begin, I’m going to first address the two topics that I get asked about most often: interest rates and inflation. And I would guess they are the topics front and center in many of your minds as well.

After the FOMC’s last policy rate hike in July, I went on record with my view that, if economic and financial conditions evolved roughly as I expected they would, we could hold rates where they are. And I am pleased that, so far, economic and financial conditions are evolving as I expected, if not perhaps even a tad better.

Let’s look at the current dynamics. There is a steady, if slow, disinflation under way. Labor markets are coming into better balance. And, all the while, economic activity has remained resilient.

Given this, I remain today where I found myself after July’s meeting: Absent a stark turnabout in the data and in what I hear from contacts, I believe that we are at the point where we can hold rates where they are.

In barely more than a year, we increased the policy rate by more than 5 percentage points and to its highest level in more than two decades — 11 rate hikes in a span of 12 meetings prior to September. We not only did a lot, but we did it very fast.

We also turned around our balance sheet policy — and we will continue to tighten financial conditions by shrinking the balance sheet.

The workings of the economy cannot be rushed, and it will take some time for the full impact of the higher rates to be felt. In fact, I have heard a plea from countless contacts, asking to give them some time to absorb the work we have already done.

I agree with them. I am sure policy rates are restrictive, and, as long they remain so, we will steadily press down on inflation and bring markets into a better balance.

Holding rates steady will let monetary policy do its work. By doing nothing, we are still doing something. And I would argue we are doing quite a lot.

Headline PCE inflation remained elevated in August at 3.5 percent year over year, but it is down 3 percentage points from this time last year. About half of that drop is due to the volatile components of energy and food that, while basic necessities, they are typically excluded by economists in the so-called core inflation rate to give a more accurate assessment of the pace of disinflation and its likely path forward.

Well, core PCE inflation has also shown clear signs of progress, and the August monthly reading was its smallest month-over-month increase since 2020.

So, yes, a steady disinflation is under way, and I expect it to continue. My projection is that inflation will drop below 3 percent in 2024 and level out at our 2 percent target thereafter.

However, there can be challenges in assessing the trends in disinflation. For example, September’s CPI report came out modestly on the upside, driven by energy and housing.

Let me be clear about two things. First, we will not tolerate a reacceleration in prices. But second, I do not want to overreact to the normal month-to-month variability of prices. And for all the fancy techniques, the best way to separate a signal from noise remains to average data over several months. Of course, to do so, you need several months of data to start with, which, in turn, demands that, yes, we remain data-dependent but patient and cautious with the data.

Turning to the jobs picture, I do anticipate national unemployment to end the year at about 4 percent — just slightly above where we are now — and to increase slowly over the next year to peak at around 4.5 percent before heading back toward 4 percent in 2025. That is a rate in line with what economists call the natural rate of unemployment, or the theoretical level in which labor market conditions support stable inflation at 2 percent.

Now, that said, as you know, there are many factors that play into the calculation of the unemployment rate. For instance, we’ve seen recent months where, even as the economy added more jobs, the unemployment rate increased because more workers moved off the sidelines and back into the labor force. There are many other dynamics at play, too, such as technological changes or public policy issues, like child care or immigration, which directly impact employment.

And beyond the hard data, I also have to balance the soft data. For example, in my discussions with employers throughout the Third District, I hear that given how hard they’ve worked to find the workers they currently have, they are doing all they can to hold onto them.

So, to sum up the labor picture, let me say, simply, I do not expect mass layoffs.

I do expect GDP gains to continue through the end of 2023, before pulling back slightly in 2024. But even as I foresee the rate of GDP growth moderating, I do not see it contracting. And, again, to put it simply, I do not anticipate a recession.

Look, this economy has been nothing if not unpredictable. It has proven itself unwilling to stick to traditional modeling and seems determined to not only bend some rules in one place, but to make up its own in another. However, as frustratingly unpredictable as it has been, it continues to move along.

And this has led me to the following thought: What has fundamentally changed in the economy from, say, 2018 or 2019? In 2018, inflation averaged 2 percent almost to the decimal point and was actually below target in 2019. Unemployment averaged below 4 percent for both years and was as low as 3.5 percent — both nationwide and in our respective states — while policy rates peaked below 2.5 percent.

Now, I’m not saying we’re going to be able to exactly replicate the prepandemic economy, but it is hard to find fundamental differences. Surely, I cannot and will not minimize the immense impacts of the pandemic on our lives and our families, nor the fact that for so many, the new normal still does not feel normal. From the cold lens of economics, I do not see underlying fundamental changes. I could also be wrong, and, trust me, that would not be the first time this economy has made me rethink some of the classic models. We just won’t know for sure until we have more data to look at over time.

And then, of course, there are the economic uncertainties — both national and global — against which we also must contend. The ongoing auto worker strike, among other labor actions. The restart of student loan payments. The potential of a government shutdown. Fast-changing events in response to the tragic attacks against Israel. Russia’s ongoing war against Ukraine. Each and every one deserves a close watch.

These are the broad economic signals we are picking up at the Philadelphia Fed, but I would note that the regional ones we follow are also pointing us forward.

First, while in the Philadelphia Fed’s most recent business outlook surveys, which survey manufacturing and nonmanufacturing firms in the Third District, month-over-month activity declined, the six-month outlooks for each remain optimistic for growth.

And we also publish a monthly summary metric of economic activity, the State Coincident Indexes. In New Jersey, the index is up slightly year over year through August, which shows generally positive conditions. However, the three-month number from June through August was down, and while both payroll employment and average hours worked in manufacturing increased during that time, so did the unemployment rate — though a good part of that increase can be explained as more residents moved back into the labor force.

And for those of you joining us from the western side of the Delaware River, Pennsylvania’s coincident index is up more than 4 percent year over year through August and 1.7 percent since June. Payroll employment was up, and the unemployment rate was down; however, the number of average hours worked in manufacturing decreased.

There are also promising signs in both states in terms of business formation. The number of applications, specifically, for high-propensity businesses — those expected to turn into firms with payroll — are remaining elevated compared with pre-pandemic levels. Again, a promising sign.

So, it is against this full backdrop that I have concluded that now is the time at which the policy rate can remain steady. But I can hear you ask: “How long will rates need to stay high.” Well, I simply cannot say at this moment. My forecasts are based on what we know as of late 2023. As time goes by, as adjustments are completed, and as we have more data and insights on the underlying trends, I may need to adjust my forecasts, and with them my time frames.

I can tell you three things about my views on future policy. First, I expect rates will need to stay high for a while.

Second, the data and what I hear from contacts and outreach will signal to me when the time comes to adjust policy either way. I really do not expect it, but if inflation were to rebound, I know I would not hesitate to support further rate increases as our objective to return inflation to target is, simply, not negotiable.

Third, I believe that a resolute, but patient, monetary policy stance will allow us to achieve the soft landing that we all wish for our economy.

Before I conclude and turn things over to Rick to kick off our Q&A, I do want to spend a moment on a topic that he and I recently discussed, and it’s something about which I know there is generally great interest: fintech. In fact, I understand there is discussion about NACD hosting a conference on fintech.

Well, last month, we at the Philadelphia Fed hosted our Seventh Annual Fintech Conference, which brought business and thought leaders together at the Bank for two days of real in-depth discussions. And I am extraordinarily proud of the fact that the Philadelphia Fed’s conference has emerged as one of the premier conferences on fintech, anywhere. Not that it’s a competition.

I had the pleasure of opening this year’s conference, which always puts a focus on shifts in the fintech landscape. Much of this year’s conference centered around developments in digital currencies and crypto — and, believe me, some of the discussions were a little, shall we say, “spirited.” However, my overarching point to attendees was the following: Regardless of one’s views, whether in favor of or against such currencies, our reality requires us to move from thinking in terms of “what if” to thinking about “what next.”

In many ways, we’re beyond the stage of thinking about crypto and digital currency and into the stage of having them as reality — just as AI has moved from being the stuff of science fiction to the stuff of everyday life. What is needed now is critical thinking about what is next. And we at the Federal Reserve, both here in Philadelphia and System-wide, are focused on being part of this discussion.

We are also focused on providing not just thought leadership but actionable leadership. For example, the Fed rolled out our new FedNow instant payment service platform in July. With FedNow, we will have a more nimble and responsive banking system.

To be sure, FedNow is not the first instant payment system — other systems, whether operated by individual banks or through third parties, have been operational for some time. But by allowing banks to interact with each other quickly and efficiently to ensure one customer’s payment becomes another’s deposit, we are fulfilling our role in providing a fair and equitable payment system.

Another area where the Fed is assuming a mantle of leadership is in quantum computing, or QC, which has the potential to revolutionize security and problem-solving methodologies throughout the banking and financial services industry. But that upside also comes with a real downside risk, should other not-so-friendly actors co-opt QC for their own purposes.

Right now, individual institutions and other central banks globally are expanding their own research in QC. But just as these institutions look to the Fed for economic leadership, so, too, are they looking to us for technological leadership. So, I am especially proud that this System-wide effort is being led from right here at the Philadelphia Fed.

I could go on and talk about fintech for much longer. After all, I’m actually an engineer more than I am an economist. But I know that Rick is interested in starting our conversation, and I am sure that many of you are ready to participate.

But one last thought on fintech — my answers today aren’t going to be generated by ChatGPT.

On that note, Rick, thanks for allowing me the time to set up our discussion, and let’s start with the Q&A.

[archived PDF of the above speech]

Movies and Chemistry: Keeping the Enchantment of Education

Several movies give you an “enchanting” back door or window into chemistry so that you can “beat” the tediousness of regular education and come into the field and its topics via these movies:

I.

The Man in the White Suit is a 1951 British comedy classic with Alec Guinness as a genius research chemist. He fiddles with his flasks and polymer and textile chemistry experiments until he invents a fabric that shows no wear and tear “forever.” This would seem like a great boon to humanity in its clothing needs but the chemist (“Sidney Stratton”) finds that both labor and management reject his discovery violently as it threatens jobs and profits. Textile or fabric polymer chemistry is at the heart of the plot.

Cry Terror! is a taut 1958 crime thriller movie with James Mason and Rod Steiger. The plot involves the terrorist threat of exploding a domestic airliner with a hidden RDX cache (a TNT successor) unless the demanded payment is made.

RDX was used by both sides in World War II. The U.S. produced about 15,000 long tons per month during WWII and Germany about 7,000 long tons per month. RDX had the major advantages of possessing greater explosive force than TNT, used in World War I and requiring no additional raw materials for its manufacture.

Semtex is a general-purpose plastic explosive containing RDX and PETN. It is used in commercial blasting, demolition, and in certain military applications.

A Semtex bomb was used in the Pan Am Flight 103 (known also as the Lockerbie) bombing in 1988. A belt laden with 700 g (1.5 lb) of RDX explosives tucked under the dress of the assassin was used in the assassination of former Indian prime minister Rajiv Gandhi in 1991.

The 1993 Bombay bombings used RDX placed into several vehicles as bombs. RDX was the main component used for the 2006 Mumbai train bombings and the Jaipur bombings in 2008. It also is believed to be the explosive used in the 2010 Moscow Metro bombings.

Traces of RDX were found on pieces of wreckage from 1999 Russian apartment bombings and 2004 Russian aircraft bombings. Further reports on the bombs used in the 1999 apartment bombings indicated that while RDX was not a part of the main charge, each bomb contained plastic explosive used as a booster charge.

Ahmed Ressam, the al-Qaeda Millennium Bomber, used a small quantity of RDX as one of the components in the bomb that he prepared to detonate in Los Angeles International Airport on New Year’s Eve 1999-2000; the bomb could have produced a blast forty times greater than that of a devastating car bomb.

In July 2012, the Kenyan government arrested two Iranian nationals and charged them with illegal possession of 15 kilograms (33 pounds) of RDX. According to the Kenyan Police, the Iranians planned to use the RDX for “attacks on Israeli, U.S., UK and Saudi Arabian targets.”

RDX was used in the assassination of Lebanese Prime Minister Rafic Hariri on February 14, 2005.

In the 2019 Pulwama attack in India, 250 kg of high-grade RDX was used by Jaish-e-Mohammed. The attack resulted in the deaths of 44 Central Reserve Police Force personnel as well as the attacker.

Semtex was developed and manufactured in Czechoslovakia, originally under the name B 1 and then under the “Semtex” designation since 1964, labeled as SEMTEX 1A, since 1967 as SEMTEX H, and since 1987 as SEMTEX 10. Originally developed for Czechoslovak military use and export, Semtex eventually became popular with paramilitary groups and rebels or terrorists because prior to 2000 it was extremely difficult to detect, as in the case of Pan Am Flight 103.

The Russian apartment bombings were a series of explosions that hit four apartment blocks in the Russian cities of Buynaksk, Moscow and Volgodonsk in September 1999, killing more than 300, injuring more than 1,000, and spreading fear across the country. The bombings, together with the Invasion of Dagestan, triggered the Second Chechen War. The handling of the crisis by Vladimir Putin, who was prime minister at the time, boosted his popularity greatly and helped him attain the presidency within a few months.

The blasts hit Buynaksk on 4 September and in Moscow on 9 and 13 September. On 13 September, Russian Duma speaker Gennadiy Seleznyov made an announcement in the Duma about receiving a report that another bombing had just happened in the city of Volgodonsk. A bombing did indeed happen in Volgodonsk, but only three days later, on 16 September. Chechen militants were blamed for the bombings, but denied responsibility, along with Chechen president Aslan Maskhadov.

A suspicious device resembling those used in the bombings was found and defused in an apartment block in the Russian city of Ryazan on 22 September. On 23 September, Vladimir Putin praised the vigilance of the inhabitants of Ryazan and ordered the air bombing of Grozny, which marked the beginning of the Second Chechen War. Three FSB agents who had planted the devices at Ryazan were arrested by the local police, with the devices containing a sugar-like substance resembling RDX.

II.

The movie Khartoum (1966) has General Charles Gordon traveling to Sudan in 1884 to quell the “mad mullah” the Mahdi. (Osama bin Laden of his day).
At the train station where General Gordon starts his trip, there’s a railway ad sign that promotes the use of “Wright’s Coal Tar Soap.”

This gives us a sign of the rise of the modern chemical industry.

III.

Think of “Sherlock Holmes” in terms of all the movies and TV series or the original stories and books:

Holmes has to explain to Watson how he survived the assassination attempt on him by Moriarty, “the Napoleon of Crime” who threw him off the Reichenbach Falls. Holmes explains that he faked Moriarty out and clung to a bush or something and was (obviously) not killed.

Holmes tells Watson what he does when he returns to civilization and travels and studies for some three years:

“I then passed through Persia, looking in at Mecca, and paid a short but interesting visit to the Khalifa at Khartoum, the results of which I communicated to the Foreign Office. Returning to France, I spent some months in a research into the coal-tar derivatives, which I conducted in a laboratory at Montpellier, in the south of France.”

The context implies the year 1894.

There is clear evidence that Mr. Holmes was deeply involved in the research of coal-tar derivatives as early as 1889 when the events of the Copper Beeches matter were transpiring.

We are told that on an evening in 1889, Mr. Holmes was seated in 221B Baker Street at the deal table loaded with retorts and test tubes. He was settling down to one of those all-night chemical researches in which he frequently indulged.

The research work was interrupted by a message of distress from Violet Hunter. Watson found that there was a train the next morning, and Holmes tells Watson:

“That will do very nicely. Then perhaps I had better postpone my analysis of the acetones as we may need to be at our best in the morning.”

It is clear that Holmes was engaged in coal-tar research long before his visit to Montpellier in the south of France.

The quotation from the Copper Beeches story refers to acetones, not to coal-tar derivatives.

“In the fractional distillation of coal-tar, the distillate separates into five distinct groups or layers, depending upon the stage of the process and the amount of heat applied. Category-one of the five includes benzene, toluene, xylenes and cumenes.

Acetones [dimethelketone-CH3COCH3] may be derived from the oxidation of cumene. And cumene [isopropylbenzene-C6H5C(CH3)2] is derived by distillation from the coal-tar naphtha fractions.”

Cumenes are derived from coal-tar, and acetones are derived from cumenes. Thus, a study of the acetones is, necessarily, research into coal-tar derivatives.

The rise of chemical engineering and organic chemistry are at the heart of the Sherlock Holmes stories.

Thus we can “climb” into chemistry via these books and movies and keep a feeling of enchantment as a kind of educational “shoehorn.”

From ASEAN and G20 to APEC, as World Leaders Meet in Person Again, 3 Reasons to Root for Multilateralism

By Wang Huiyao | Founder of the Center for China and Globalization (CCG)

Over the past two weeks, Asia has played host to the most intense sequence of multilateral summits since the pandemic began, as national leaders gathered for meetings organized by ASEAN, the G20 and APEC. Although overshadowed by geopolitical tensions, the meetings marked a welcome return to in-person summit diplomacy, and the better-than-expected outcomes show hope yet for multilateralism.

The conclaves began in Phnom Penh with the annual summit of the Association of Southeast Asian Nations. At the first of such in-person events in almost three years, ASEAN leaders took the positive step of agreeing in principle to admit East Timor as the 11th member of the organization.

As leaders moved on to Bali for the Group of 20 summit, expectations were low after ministerial meetings in the run-up had failed to produce consensus. Earlier in the year, given fractures in the wake of Russia’s invasion of Ukraine, there was a question mark over whether the G20 could even go ahead or survive in its existing form.

In the end, the summit surpassed expectations by producing a joint declaration after intense negotiations, with leaders finding the compromises necessary to unite in declaring that “today’s era must not be of war” and pledging to uphold the multilateral system.

The summit also saw a positive face-to-face meeting between China’s President Xi Jinping and U.S. President Joe Biden, their first as leaders, signaling a willingness to halt the downward trajectory of China-U.S. relations.

In Bangkok, the 21 leaders of the Asia-Pacific Economic Cooperation forum also pledged to uphold and strengthen the rules-based multilateral trading system. Importantly, the group agreed on a multi-year work plan for an Asia-Pacific free trade area.

Reflecting on these three summits, three takeaways give reason for cautious optimism that multilateralism can yet be revived and play a major role in solving our challenges.

First, and perhaps most obviously, the return of in-person summit diplomacy is a welcome uplift for global cooperation. Virtual formats played a useful interim role at the height of the pandemic but were never a substitute for getting leaders in the same room. That is especially when it comes to interactions on the sidelines, often as important as the main event.

China’s return to diplomacy at the highest level was a further boost, both for the nation and the rest of the world.

In addition to Xi’s highly anticipated meeting with Biden, the Chinese leader met over a dozen other leaders at the G20 and APEC summits, including a warmer-than-expected first meeting with Japanese Prime Minister Fumio Kishida and his first meeting with an Australian prime minister since 2016.

Leaders got to meet their new counterparts for the first time or build on existing relationships, which can only help global cooperation.

The second takeaway is that as grave as our challenges are, the threat of escalating conflict and severe economic pressures on all nations seem to be focusing minds and increasing the willingness to engage and cooperate—out of necessity if nothing else.

The G20 summit was the second major one this year to surpass expectations after the 12th World Trade Organization Ministerial Conference in June surprised observers by agreeing on a plan to reform the organization and its dispute settlement mechanism. The G20 statement reiterated support for this WTO reform plan, which will be critical to get the free trade agenda back on track and provide a much-needed boost for the global economy.

Third, and perhaps most significantly for the long term, the recent summits marked an acceleration of the trend towards multi-polarization in international diplomacy, and in particular, the rising influence of non-aligned “middle powers” to shape multilateral outcomes.

The middle powers represented at ASEAN, the G20 and APEC have huge stakes in avoiding a bifurcation of the global economy that might result from a new cold war. They don’t want to be forced to pick sides and many show a growing willingness and ability to build bridges and restore positive momentum for multilateralism.

Indonesia is a prime example. The country’s strategic heft and non-aligned credibility make it well-placed to bridge different camps. President Joko Widodo made a big political bet on the success of the G20 and has won praise for the deft diplomacy that kept the organization alive and got it to a joint statement.

The Indian delegation reportedly also played a big role in achieving consensus on language in the statement, with the BRICS group (Brazil, Russia, India, China and South Africa)—as well as Indonesia—turning out to be crucial swing voters in securing the joint statement. One Indian official said it was “the first [G20] summit where developing nations shaped the outcome.”

There is scope for this trend to continue next year as middle powers continue to rise in stature, and India and Indonesia take over the presidency of the G20 and ASEAN, respectively. Brazil will host the G20 the year after.

Over in Sharm el-Sheikh at the COP27 UN climate summit, another middle power—the host Egypt—also won praise for helping to shepherd a historic financing deal for poor countries affected by climate change. But the ultimate failure to reach a commitment to phase down fossil fuels was a sobering reminder of the huge difficulties that remain in forging the global consensus needed to overcome our shared challenges.

World-Watching: The Problem with the Current Russia Sanctions Regime

[from Project Syndicate, by Mohamed A. El-Erian]

There is much debate about the effectiveness of Western sanctions, the Ukraine war’s implications for markets and the global economy, and what the West’s next steps should be. While there are few good options, some are clearly worse than others.

Cambridge — It has been five months since Europe and the United States imposed tough economic and financial sanctions on Russia, a G20 country that was the world’s eleventh-largest economy on the eve of its invasion of Ukraine. While the sanctions have been gradually strengthened in the intervening months, debate rages about their effectiveness, the war’s broader implications for markets and the global economy, and what the West’s next steps should be.

On the first question, although the sanctions have been less effective than Europe and the U.S. had hoped, they also are proving more onerous than the Kremlin claims. Russia’s central bank expects GDP to contract by 8-10% this year, while other forecasters expect a larger fall, together with longer-lasting damage to growth potential. Imports and exports have been severely disrupted, and inflows of foreign investment have essentially stopped. Shortages are multiplying, pushing inflation higher. At this point, the country no longer has a properly functioning foreign-exchange market.

The sanctions would have bitten much harder had the West not opted for a carve-out of Russia’s energy sector, and had many more countries joined the U.S. and Europe in the effort. Because that didn’t happen, Russia has not felt nearly as much pressure as it would have. Moreover, it has been able to continue trading through various side and back doors that will likely become increasingly important as long as the sanctions regime, as currently designed, continues.

Nonetheless, it is only a matter of time before the Russian economy experiences a harder hit. Inventories of imported goods – including many critical technological and industrial inputs – are dwindling fast, and many sectors are becoming less resilient. The cumulative damage to Russia’s economy over time will be significant and long-lasting – a fact that has not yet been fully captured by consensus medium-term forecasts.

The second question concerns global spillovers from the war and the sanctions regime. Most observers agree that Russia’s invasion has increased not just energy insecurity but also food insecurity, highlighting the fallout from the war’s disruption to Ukrainian agricultural exports. But there is still much debate about the West’s use of the economic nuclear sanctions option: the curbs placed on Russia’s central bank and on Russia’s use of the international payments system.

These curbs are far more intrusive than the usual mix of restrictions on sanctioned government and private sector trade and on individuals’ financial dealings. Yet, because they are not subject to any internationally agreed standards, guidelines, or checks and balances, they fall outside the purview of relevant global-governance bodies such as the Bank for International Settlements, the International Monetary Fund, and the World Trade Organization.

In a time of war, such oversight might seem like a nicety. But some worry that the sanctions could significantly reduce the dollar’s role as the world’s reserve currency and the U.S. financial system’s role as the primary global intermediary for other countries’ savings and investments. After all, a growing number of countries undoubtedly now feel more vulnerable to the reach of U.S. sanctions.

But it is impossible to replace something with nothing, which means that no significant loss of dollar or U.S. financial primacy will occur in the immediate future. Rather, the sanctions will lend further momentum to the gradual process of global economic fragmentation, which was also fueled a few years ago by the tariffs imposed by the Trump administration. More countries now have even more of a reason to pursue greater financial resilience and inherently inefficient forms of self-insurance.

That brings us to the third debate. With no end in sight for the war, what should the West do next? Fearing the implications for energy prices and the supply of gas to Europe, many in the West are tempted to call for a moratorium on any new sanctions – or even for additional carve-outs. Others, however, favor additional measures to hold Russia accountable for its indiscriminate attacks on Ukrainian civilians.

In any case, maintaining the current sanctions regime is not problem-free, owing to the twin objectives of pressuring Russia and limiting the economic disruption to Europe. Moreover, as European Commission President Ursula von der Leyen recently said, it feels as if Russia is “blackmailing” Europe by threatening to disrupt gas supplies at any moment. No wonder the Commission is urging member countries to cut consumption by 15%.

Under the current sanctions regime, the West risks falling between two horses. While easing sanctions could help alleviate concerns about Europe’s economic outlook, this option is a non-starter, given the atrocities that Russian forces are committing in Ukraine. But if the West is serious about pressuring Russia through truly crippling economic and financial sanctions, it needs to bite the bullet and eliminate the carve-outs for energy.

Doing so would undoubtedly have a severe short-term economic impact on European economies and the rest of the world, amplifying the “little fires everywhere” syndrome that I warned about in May. It is therefore critical that governments use their available fiscal space to provide targeted support to vulnerable segments of the population, as well as to fragile countries; and multilateral agencies must support developing countries through aid and a more operational debt relief framework. If done properly, this option would yield better outcomes in the medium and long term than the current strategy.

Muddling through risks bringing about the worst of all possible worlds. It is insufficient to dissuade Russia from continuing its illegal war; it is fueling deeper fragmentation of the international monetary system; and it is not even protecting Europe from a winter gas disruption.

Mohamed A. El-Erian, President of Queens’ College at the University of Cambridge, is a professor at the Wharton School of the University of Pennsylvania and the author of The Only Game in Town: Central Banks, Instability, and Avoiding the Next Collapse (Random House, 2016).

Russia-Watching: Economic Dysfunctionalities

[from the Russian Analytical Digest]

This issue deals with dysfunctionalities in the Russian economy. The first three contributions look at the direct impact of sanctions. Ilya Matveev provides an overview, while Andrei Yakovlev compares the government’s anti-sanctions measures to its reaction to the economic impact of the COVID-19 pandemic. Janis Kluge offers a more detailed picture of the short- and long-term effects of the unfolding sanction regime. Michael Rochlitz then goes on to explain the lack of strategic planning in the country’s economic policy. Finally, Olga Masyutina and Ekaterina Paustyan provide a case study of inefficient governance mechanisms looking at waste management.

Read the full issue [archived PDF].

Analyses

Sanctions against Russia: No Blitzkrieg, but a Devastating Effect Nonetheless

by Ilya Matveev

In response to the Russian invasion of Ukraine, over 40 countries have introduced sanctions against Russia. The new restrictions concern finance, trade, logistics, and personal sanctions against businessmen and officials. In addition, more than 1,000 companies have ceased or limited their activities in Russia. In this article, Ilya Matveev argues that the sanctions, despite their unprecedented scale, have not led to the collapse of the Russian economy, yet their effect is dramatic, multi-faceted, and will increase over time.

Read the full issue [archived PDF].

Fighting the Pandemic and Fighting Sanctions: Can the Russian Economy Now Benefit from Its Experience with Anti-Crisis Measures?

by Andrei Yakovlev

Faced with tough international sanctions in reaction to its war against Ukraine, the Russian government has resorted to measures developed during the COVID-19 pandemic in order to stabilize the economy. This short analysis discusses the rationale behind this approach and demonstrates its limits.

Read the full issue [archived PDF].

Russia’s Economy under Sanctions: Early Impact and Long-Term Outlook

by Janis Kluge

Four months after a coalition of Western states imposed unprecedented sanctions on Russia, the Russian economy seems to be holding up better than expected. The Central Bank has managed to stabilize the country’s financial system and Russian officials are trying to project optimism about the future. However, this optimism is likely to be short-lived. The sanctions’ effects are only just beginning to unfold: supply-chain problems are intensifying and demand is falling quickly. In the longer run, Russia’s economy will become more primitive as it partially decouples from international trade. To avoid social tensions, the government will intervene to support Russian businesses, leading to more protectionism and a larger state footprint in the economy.

Read the full issue [archived PDF].

Why Russia Is Lacking an Economic Strategy for the Future

by Michael Rochlitz

Even before the economic crisis caused by Russia’s full-scale attack against Ukraine and the ensuing sanctions, the Russian economy was plagued by a number of growing problems. As a result, Russia’s economy has hardly grown for almost a decade, with an average annual growth rate of just 0.5% between 2013 and 2021. However, the Russian government does not have a strategy for addressing the fundamental economic challenges that are looming just over the horizon. There also seem to be no public debates about these challenges, whether in the policy circles around the government or among the wider public.

Read the full issue [archived PDF].

The Political Economy of Waste Management in Russia

by Olga Masyutina and Ekaterina Paustyan

The problem of household waste is one of the numerous environmental challenges facing Russia today. The 2019 nation-wide waste management reform was designed to tackle this problem by promoting recycling. However, the reform is stalling, due in large part to the nature of state-business relations in Russia. The lack of transparency in the public procurement process and the importance of personal connections between businesses and the federal and regional authorities undermine the implementation of the reform and produce suboptimal outcomes in the fight against waste.

Read the full issue [archived PDF].

India and the Russia-Ukraine War: The Paradox of Military Dependence, Traditional Loyalty and Strategic Autonomy

[from India in Transition, published by the Center for the Advanced Study of India (CASI) of the University of Pennsylvania, by Arndt Michael]

India, long-established as the world’s most populous democracy, has been quite instrumental over the years in assisting various countries dealing with democratic struggles. This support has included a blend of bilateral and multilateral initiatives, and especially economic development projects. Yet, India’s recent attitude toward the Russian attack on Ukraine and its concomitant behavior in the United Nations Security Council (as a non-permanent member) seems to contradict its support of democracy. By abstaining, rather than explicitly voting in favor of UN resolutions condemning Russian aggression at the beginning of the war, India angered several UN member-countries.

In order to substantiate its abstention from voting, India felt compelled to issue a so-called “Explanation of Vote” (EoV). In it, India asked for a “return to the path of diplomacy” and an immediate cessation of “violence and hostilities.” Crucially, India stated in the EoV that “the contemporary global order has been built on the UN Charter, international law, and respect for the sovereignty and territorial integrity of states…all member states need to honor these principles in finding a constructive way forward. Dialogue is the only answer to settling differences and disputes, however daunting that may appear at this moment.” 

While these statements and the call for dialogue are in accordance with India’s professed stance toward the relevance and objectives enshrined in the UN Charter, the discrepancy between rhetoric and practice is still conspicuous. At first glance, a “good” relationship with Russia seems to be more significant than the expectations of the world-community as represented in the United Nations. And, more importantly, by abstaining, India seemingly violated one of its central foreign and strategic policies: to always strive for strategic autonomy.

However, from a strategic perspective, India is precisely replicating what it did when the Soviet Union invaded Afghanistan. For India, its own national security is at stake, as well as its current and future geostrategic influence in Asia and the world. The military dependence that currently exists between India and Russia is nothing short of gigantic and has created a dangerous conundrum. Since the “Indo–Soviet Treaty of Peace, Friendship and Cooperation” was signed in 1971, defense agreements and long-term supply contracts have been in place. And while India and Russia have shared a strategic relationship since October 2000, this was upgraded in December 2020 to a “Special and Privileged Strategic Partnership.” 

Although there was a marked reduction of Russian imports in past years, official data from the Stockholm International Peace Research Institute (SIPRI) reveal that between 1996-2015, the Russian proportion of Indian military imports was almost 70 percent, and between 2016-20 it still hovered around 49 percent. In fact, 70 percent of all Indian military equipment currently in use has been directly produced in Russia, was manufactured with the majority of parts coming from Russia, or licensed by Russia. In 2020, this included the majority of Indian tanks, the only aircraft carrier (the INS Vikramaditya, a heavily modified Kiev-class aircraft carrier) with all of its combat aircraft MiG-29s, six frigates, four destroyers and the only nuclear-powered submarine. Additionally, eight out of fourteen Indian Navy submarines belong to the Russian Kilo-class. The Indian Air Force flies Sukhoi Su-30MKIs and Mil Mi-17s, which, respectively, constitute the largest share of the combat aircraft and utility helicopters, in addition to Russian tanker planes. India also just recently purchased the S-400 missile system.

Even though India has begun to reorient itself militarily toward other countries—the U.S., Israel, France and Italy—and has substituted foreign imports by slowly developing its own capabilities, a large number of new Indo-Russian projects are in the conceptual or implementation stages. In December 2021, in the frame of the so-called “2+2 Dialogue” (foreign and defense ministers), India and Russia began a new phase in their military–technological cooperation. Incidentally, India has used this very format for furthering cooperation in strategic, security and intelligence issues with four of its key strategic partners: Australia, the U.S., Japan and the newly added Russia. Russia and India agreed upon a further deepening of mutual military relations for ten years (until 2031). What is new is that next to the traditional purchase of Russian weapons systems, many common research projects and the development of new weapons systems—with their production taking place equally in both countries—have been agreed upon. This production includes new frigates, helicopters, submarines, cruise missiles and even Kalashnikovs. 

The depth of this mutual engagement, and especially India’s dependence, highlights a huge dilemma that might not only have drastic strategic consequences, but also long-lasting regional repercussions. The worldwide sanctions issued against Russia aim at the Russian economy and military. When it comes to the procurement of such crucial components as microchips or airline parts, Russia is soon expected to face shortages, essentially crippling its capacity to repair, construct, or have spare parts available (let alone construct new equipment). Unless other countries, such as China, circumvent international sanctions and step-in, the expected Russian inability to take care of its own military will have a spill-over effect. Russia is unlikely to be able to fulfill its contractual obligations toward India, and the lack of spare parts also has the potential to cripple India’s own military with regards to the Russian weapons equipment. The procurement agreements and common projects are, hence, all in jeopardy and India, now more than ever, depends on Russian goodwill. 

Next to military dependence, there are other concomitant effects in the economic and political sphere that influence Indian voting behavior. The worldwide sanctions have already led to dramatic increases in oil and gas prices, with India relying on imports of up to 80 percent. India will, therefore, have to pay much more for such crucial imports. Military imports from other countries aimed at substituting Russian equipment will also be much more expensive. All of this deals the Indian economy another blow—an economy that has been especially hit hard by the COVID-19 pandemic. And politically, Indian hegemony in South Asia has been markedly under pressure, in no small part because of the China–Pakistan axis. In the eyes of India, this axis poses a serious threat to an already highly volatile Indo–Pakistan relationship. In addition, the Indo–China relationship reached a new low in May 2020 when Chinese infrastructure projects along the Himalayan borderlands led to fighting and the killing of soldiers. In addition, the Chinese claims to the South China Sea are categorically disputed by India. Chinese overtures toward Sri Lanka, the Maldives, and especially Pakistan in the frame of the Road Initiative are also regarded with growing discontent, as India claims that China is following a policy of encircling India.

In its 75th year of independence, India is following a classic realpolitik in trying not to alienate Russia while pledging rhetorical support for Ukraine. The contradictory consequence is that Russia has now offered more discounted oil, gas, and investments, while at the same time, the UK has suggested its military relationship with India could be upgraded—and has offered weapons made in the UK. For the Indian political establishment, India cannot forgo Russian support, militarily or as a producer of cheap oil and gas. Going forward, India’s military will need to protect its national security and project Indian influence and power well beyond its borders.

Arndt Michael is a Lecturer in the Department of Political Science, University of Freiburg (Germany), author of the multi-award-winning book India’s Foreign Policy and Regional Multilateralism (Palgrave Macmillan, 2013), and co-editor of Indien Verstehen (Understanding India, Springer, 2016). His articles have been published in Asian Security, Cambridge Review of International Affairs, Harvard Asia Quarterly, India Quarterly and India Review.