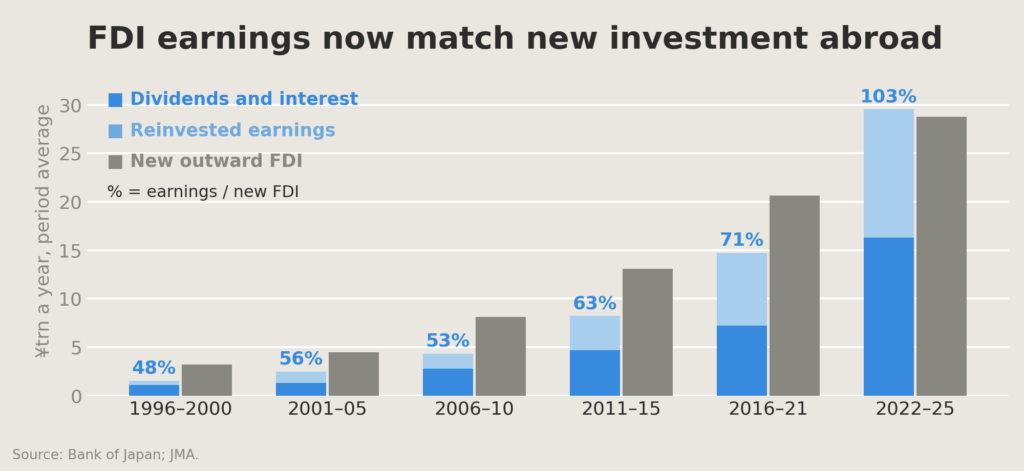
Earnings on Japan’s foreign direct investment (FDI) reached 103% of new FDI in 2022–25. With dividends and retained earnings counted together, Japan Inc. now needs to sell little yen to invest abroad.
[by OKUBO Takuji]
Key takeaways
Foreign affiliates now earn about as much as Japan invests abroad each year. Reinvested earnings, dividends and interest together reached 103% of new outward FDI in 2022–25, against 48% in 1996–2000.
Dividends from foreign affiliates account for a growing share of Japanese corporate profit. We estimate that foreign affiliates contributed 13.4% of Japan Inc.’s earnings in FY2025, up from 1.7% in FY1996.
Corporate investment abroad now involves little net yen selling. After dividends and interest paid home, the estimated outflow has been close to zero since 2022, down from about ¥5 trillion a year, or about 1% of GDP, on average in the 2010s.
Japan’s FDI stock now earns 103% of new investment
“Japan’s ageing and shrinking population depresses expected demand at home. Expected returns remain higher abroad, so Japanese companies have accelerated outward direct investment” (my translation). — MATSUBAYASHI Yōichi [松林 洋一], MOF PRI, chapter 8, p.136.
“Companies invested abroad because they saw no promising investments in Japan; they are unlikely to bring back every return. On a cash-flow basis, the external balance is in deficit and is one factor behind the weak yen” (my translation). — KARAKAMA Daisuke [唐鎌 大輔], MOF PRI, chapter 10, pp.178 and 175.
However, my review of recent data shows that while their premise of low growth prospects in Japan is probably still right, the direct investmentJapan has accumulated abroad has reached a level where it earns enough to cover Japan’s new investment abroad. This changes the exchange-rate implication even if Japan keeps investing abroad.
Overseas affiliates pay interest and dividends to their parent companies in Japan. Those dividends have become a sizable part of corporate Japan’s income: we estimate that they made up 13.4% of Japanese corporate profit in FY2025, up from 1.7% in FY1996.
When foreign affiliates retain their earnings on their balance sheets, Japan’s balance of payments statistics record them as FDI from Japan, even though no money crosses the border. While the companies receiving FDIdividends and the companies paying for new FDI are not necessarily the same, Japan Inc. as a whole is now financing its FDI almost entirely from the earnings of its overseas affiliates. At the current level of FDI, little new yen needs to be converted into foreign currencies as Japan goes about investing abroad.
A strong yen helped drive Japan’s first outward FDI boom
Japan’s outward investment was heavily restricted after WWII, requiring case-by-case permission from the government. Approvals became more and more automatic over the years until outward investment became “free in principle” in 1980. Trade friction with the US-led Japanese carmakers to restrain their exports from 1981, pushing them to build factories abroad. The rapid appreciation of the yen was also a factor. The yen strengthened from ¥242 per dollar before the Plaza Accord in September 1985 to ¥121 by the end of 1987. Japanese producers had to move lower value-added work abroad. The strong yen also gave Japanese financial institutions sizable purchasing power for a while, until the stock and property bubbles burst in 1990 and 1991.
All of these factors contributed to a rapid increase in outward FDI through the 1980s and 1990s (chart 2).
The next phase was sustained by a different pressure. With weak growth and low interest rates at home, Japan Inc. kept investing abroad, across a broader range of industries. Between 1995 and 2025, the stock of FDI rose from 9% of Japan’s GDP to 58% (chart 4). In 2025, it is as large as about 38% of the private sector’s domestic fixed capital, on our estimate.
Chart 4
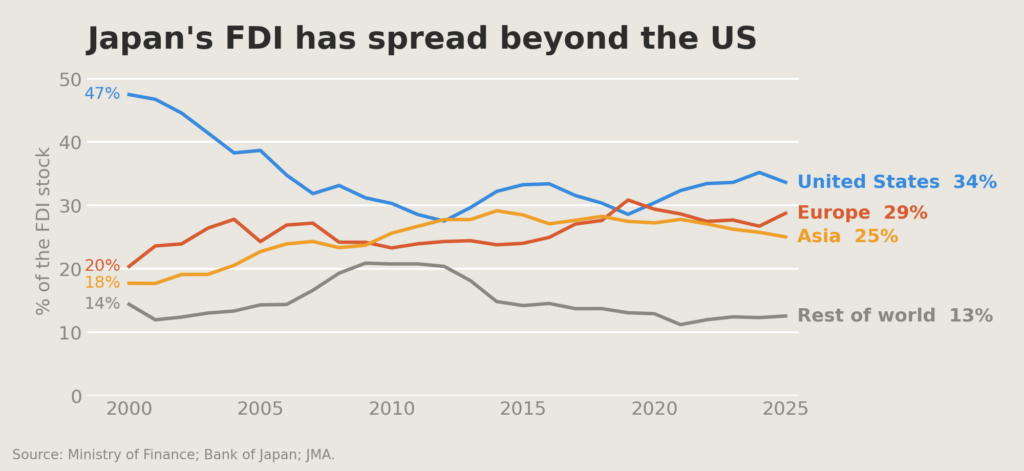
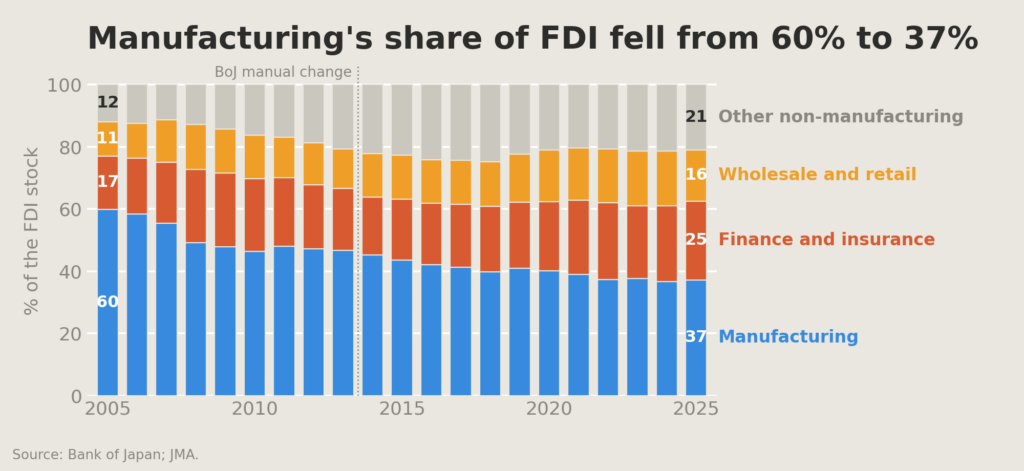
By industry composition and by destination compositions changed over time. Manufacturing’s share of the FDIstock had fallen to 37% by 2025, giving Japan’s FDI more breadth. By destination, we are seeing a revival of FDI toward the United States. It accounted for 34% of the stock in 2025, Europe 29% and Asia 25% (see earlier chart 3).
Thus, after decades of overseas investment, Japan’s FDI stock is now large enough that its earnings are sufficient to finance new investment abroad, at least for now. In the next section, I consider whether this will continue, and in particular whether Japanese companies may bring an even larger share of their overseas earnings back to Japan, given the weak yen, higher borrowing costs in yen and possibly better investment opportunities at home.
The weak yen has slowed offshoring, not reversed it
The real depreciation of the yen over the past 15 years made production in Japan more competitive. There is some evidence that manufacturers are considering bringing production back to Japan. The 2023 manufacturingwhite paper found more firms shifting production back from China than moving there, and they named the weak yen as one reason. We see some signs of reshoring. Japanese manufacturers’ overseas production ratio rose from 18.0% in FY2011 to 27.2% in FY2023, but it may have started to decline or at least stabilize. The ratio fell to 26.7% in FY2024. A Cabinet Office survey of listed manufacturers puts the ratio at 24.5% in FY2025, and their plan for FY2030 is broadly unchanged at 24.7%. The weak yen seems to have stabilized the wave of offshoring, but I see no firm evidence of a move back onshore yet.
Domestic investment has grown slowly despite the weak yen
There are tentative signs that domestic capital spending is starting to grow again. For three decades it grew at a very low speed. In real terms, private business investment rose only 26% between FY1997 and FY2025, less than 1% a year. In comparison, capital spending grew by about 4% a year on average in the United States. In my view, a weak currency is only one of the factors manufacturers weigh in designing their global production chains. The weak yen makes production in Japan competitive today, but they have also seen the exchange rate swing violently within short periods. Japan also has a shrinking population problem. It started to address it by opening a door to immigration, but the door is only tentatively open. Overall, my view is that the weak yen alone is unlikely to give Japan Inc. sufficient incentive to bring its capital back to Japan and to the yen.
Economic security is bringing some production home
The weak yen and non-economic geopolitical factors do point to a halt in Japan’s four-decade offshoring trend, although it is a stabilization, rather than an economy-wide reversal of past offshoring. Japan Inc. will continue to invest more abroad, rather than within its borders. Given the sizable growth in the stock of cumulative FDI, Japan Inc. no longer needs to convert yen into overseas currency to keep investing abroad though. Net of dividends and interest paid home, Japan’s FDI sold about ¥5 trillion of yen a year, or about 1% of GDP, on average in the 2010s; since 2022 the net flow has been close to zero. There is also an interesting development in an effort to allow more share-exchange based M&A for cross-border deals that will further reduce the need for Japanese companies to spend their yen to purchase overseas assets. In my view, Japan Inc.’s FDI is no longer a factor to drive the yen weaker.
Although significant work remains to harness fusion energy, pursuing the development and deployment of IFE is crucial for the nation’s energy security, enabling the United States to shape implementation worldwide, avoid technological surprises from adversaries, and influence technical leadership in other energy-intensive technologies such as AI, machine learning (ML), and supercomputing.
IFE research stretches back to the early days of Lawrence Livermore, and today the Laboratory is fostering the overall fusion ecosystem. Livermore’s unique capabilities, expertise, and connections will be critical to laying the technical, logistical, and legal groundwork to make IFE possible. “IFE is a grand scientific and engineering challenge, something that is so incredibly difficult and high-risk and takes enormous expertise,” says Tammy Ma, Livermore’s IFE Institutional Initiative lead. “This challenge makes it the right kind of problem for national laboratories to pursue.”
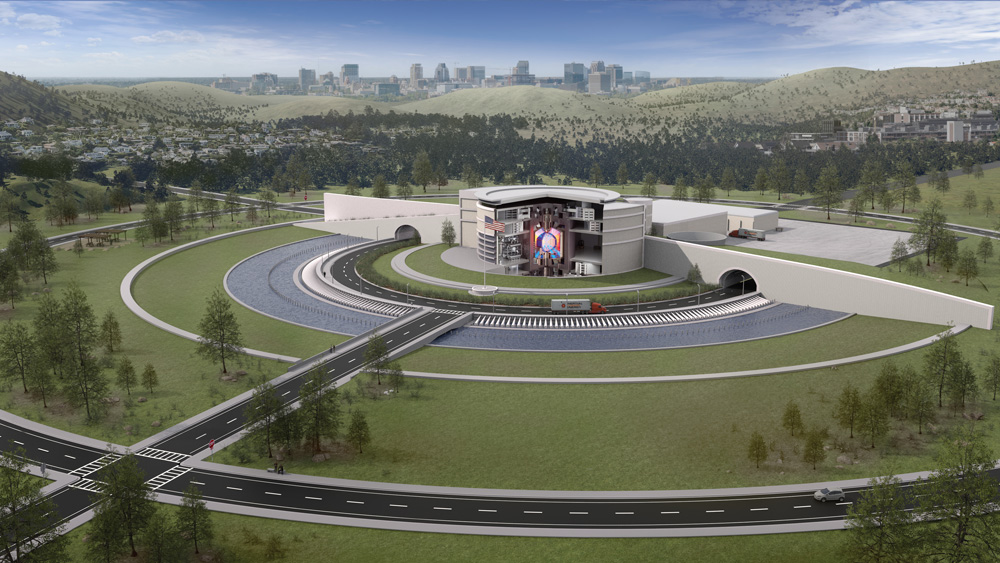
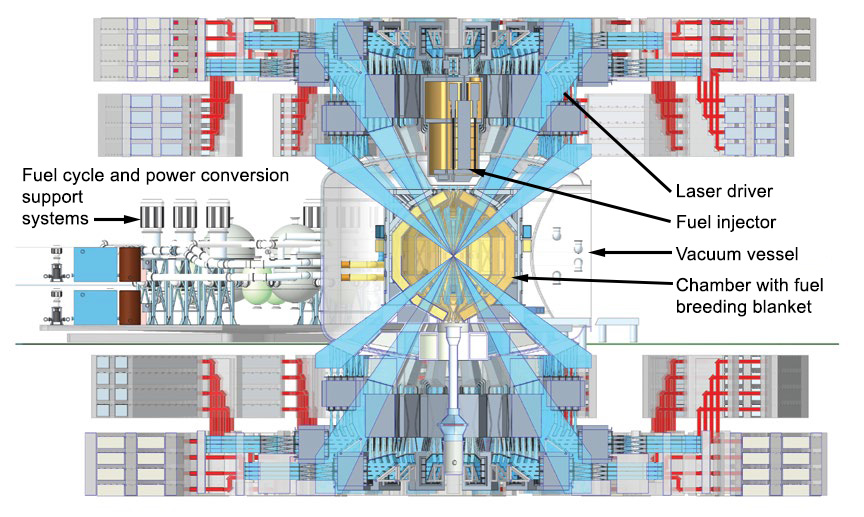
This artist’s rendering shows the concept for an inertial fusion energy (IFE) power plant design, with a cutaway to show the plant’s target chamber in the center. Livermore researchers are laying the groundwork for private fusion companies to build similar designs. (Illustration by Eric Smith.)
Designing for Viability
NIF is the only facility to date to demonstrate the ignition and burning plasma conditions that are prerequisites for IFE, but it is an experimental facility for stockpile stewardship research, not a power plant. To be commercially viable and produce the energy to offset costs and meet demands (baseload power), IFE plants will need to generate more than 30 times the energy they deliver to the fusion target on every shot while firing 10 or more shots per second, compared to NIF’s rate of one or two shots per day.
The Laser Inertial Fusion Energy (LIFE) study, conducted between 2008 and 2013, aimed to build directly on technology developed for NIF to achieve IFE and took a systematic approach to this requirement by developing the Integrated Process Model (IPM). (See S&TR, April/May 2009 [archived PDF], pp. 6-15.)
IPM is a technoeconomic model of an IFE power plant with detailed technical and cost breakdowns and interdependencies of key systems and subsystems. “The work done under LIFE was fantastic,” says Ma. “IPM lays out engineering and physics requirements for the entire system to test out different scenarios and see the impact. Now, we not only get to expand on all that but also leverage 15 years of new data from NIF, better codes, and high-performance computing (HPC), as well as new work in AI, ML, advanced manufacturing, diagnostics, and nonproliferation across the Laboratory.”
IPM describes an IFE power plant that requires a solid-state laser driver system to “pump” lasers with optical energy using laser diodes instead of flashlamps as at NIF. The plant will also need to fabricate and fill target capsules onsite and send them into its target chamber at a high enough frequency to produce baseload power. “We will have to repeatedly inject targets into the chamber, so the targets must be able to withstand and survive that process,” explains Ma. “Then, the lasers will track the moving targets, and when one gets to the center of the chamber, they would fire on the centered target, repeating 10 to 20 times per second.”
The facility would convert fusion energy into heat and then electricity via steam turbines, sending most of the electricity to the power grid and recycling the rest to power operations on subsequent shots. Neutrons from the reaction would produce tritium needed for the DT fuel by bombarding lithium isotopes in a “breeding blanket” material lining its target chamber. By closing both the power and fuel cycles, IFE plants are expected to be self-sustaining.
Thanks in part to IFE STARFIRE (IFE Science and Technology Accelerated Research for Fusion Innovation and Reactor Engineering), a Department of Energy (DOE)-funded multi-institutional IFE research and development hub, researchers across the Laboratory are working to meet the new system’s demands. IPM can help identify key challenges, test the viability of new designs, and direct future research. “Many technical models and cost models exist for IFE, but very few, if any, pair systems and cost models together at the same depth as IPM,” says Mackenzie Nelson, a technoeconomic systems analyst in the Computational Engineering Division. “This type of tool offers such an advantage because we can assess design choices from both a technical and economic standpoint and create blueprints for what an IFE plant could look like.”
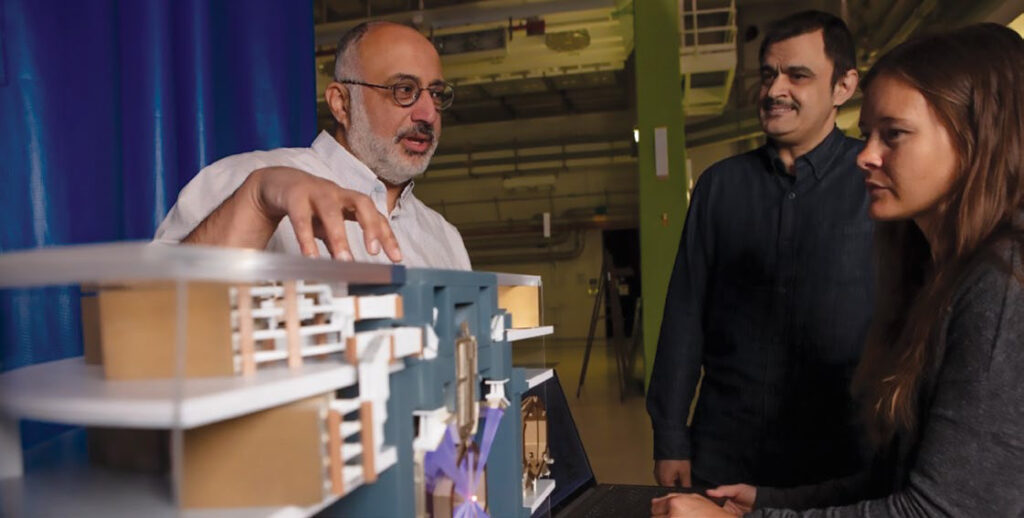
(left to right) Livermore researchers Bassem El Dasher, Claudio Santiago, and Mackenzie Nelson discuss a 3D model of a proposed IFE power plant design alongside the Integrated Process Model (IPM). IPM has more than 270 potential user inputs that researchers and collaborators can use to assess different IFE design choices to see the technical and cost impact on the entire design.
Operational Demands
NIF’s target capsules are extremely precise, fragile, and can take weeks to fabricate, fill, and position. Researchers are trying to reconcile that factor with the estimated demand of more than 800,000 capsules per day produced at less than $0.50 each to achieve IFE plant viability. To do this, they are examining optimal target designs for IFE and exploring advanced manufacturing methods such as microfluidics, volumetric additive manufacturing, and two-photon polymerization. (See S&TR, April/May 2025 [archived PDF], pp. 16-19.) Additional projects involve developing diagnostic instruments that can collect, analyze, and combine data with other diagnostics at the 10 to 20 shot per second frequency and use it to improve lasers in real time.
Nuclear fissionreactors are regulated through international agreements and export control rules, and the independent International Atomic Energy Agency (IAEA) verifies that nuclear material and facilities are only being used for peaceful purposes. Neither treaties nor the IAEA address fusion energy, and no consensus has been reached on whether fusion energy systems need an international verification program. Verification methods for safeguarding tritium are also far less developed than for plutonium and uranium and focus more on contamination and transfers than analytical accounting for discrepancies. The precise scale of allowable tritium unaccounted for without posing proliferation risk is also unclear.
Fusion systems can be designed for proliferation resistance, but not having an existing design remains a challenge.
International security analyst Anne-Marie Riitsaar and her colleagues are exploring these complexities and starting conversations with international fusion experts and private industry to raise awareness. Riitsaar also plans to collaborate with the IPM team to map tritium diversion vulnerabilities and identify high-risk points where researchers could incorporate surveillance methods into plant designs to detect and prevent potential misuse. “People sometimes ask me why I’m thinking about fusion energyregulations and proliferation risks at this point, but it’s not too early,” says Riitsaar. “Reaching a multinational consensus on regulating sensitive technologies takes considerable time and effort.”
The National Ignition Facility is an experimental facility and not a power plant, so a commercial IFE plant design has vastly different requirements—many of which are being studied by Livermore researchers and their collaborators.
The Laser Driven Fusion Integration Research and Science Test Facility (LD-FIRST) is a proposed blueprint for a proof-of-concept IFE facility that will test all the key IFE subsystems in an integrated fashion. A public-private partnership will likely be necessary to build the facility and will help the IFE community address the main subset of risks and the technological challenges of building a commercial plant.
Converging on a Solution
The team seeks to make IPM as accurate and comprehensive as possible by meeting with subject matter experts across the Laboratory to incorporate the latest research. “We’re trying to evolve the model so it has the same level of high detail across every single functional area to tell us where we can focus research and help us find optimized solutions that we could propose to industry,” says Nelson.
Computer scientist Claudio Santiago and his colleagues also modernized IPM by porting its framework from Microsoft Excel to Python in December 2024, making it compatible with AI, ML, design optimization, and HPC to further inform designs. “Once we think about all the forcing functions such as minimum shot yield and materials requirements pinning us in from every direction, we end up with an optimized solution space. As we sharpen the pencil more with these tools, that optimized solution box gets smaller until eventually we’ve converged on a point design,” says IFE lead systems engineer Justin Galbraith. Galbraith and his team’s point design is called the Laser Driven Fusion Integration Research and Science Test Facility, or LD-FIRST, a proof-of-concept physics demonstration facility for IFE. “That point design, we anticipate, will serve as the foundation for a future public-private partnership that would facilitate building and realizing a physical facility to focus the IFE community in pursuit of fusion power on the grid,” says Galbraith.
Ma chaired DOE’s “Basic Research Needs for IFE” workshop and report in 2022 and co-chairs the subcommittee providing recommendations on the nation’s fusion activities through DOE’s Fusion Energy Sciences Advisory Committee. She and her team travel often to Washington, D.C., working with DOE and legislators to expand fusion energyresearch and advocacy in the nation. Livermore also leads a “Collaboratory” with other DOEnational laboratories to connect research project leads and facilitate public-private partnerships. The Collaboratory has hosted multiple events with industry, and the Laboratory has partnered with three private companies who aim to design pilot IFE plants.
Meanwhile, Galbraith and other IFE leaders have served as technical advisors for engineering design teams at Texas A&M University and given them IFE-relevant problems to solve, including advanced chamber and blanket design. Galbraith is working with Nelson to develop the IFE plant design portion of a high-energy-density science summer school program, which Nelson is leading in 2025 at the University of California at San Diego, and they have developed IFE curriculum that has been deployed at six universities starting in spring 2025. “We’re hoping we can get a group of students really excited about fusion and start to build up the next generation of engineers and scientists that will make fusion a reality,” says Galbraith. The team has led IFE strategic planning exercises at the Laboratory, and Lawrence Livermore will stand up a new fusion institute—named “LIFT,” for Livermore Institute for Fusion Technology—a research and development center that will coordinate and centralize institutional fusion energyresearch.
Harnessing IFE will be a massive undertaking, but Livermore’s broad and deep expertise, facilities, and capabilities put the Laboratory in a unique position to lead and play an impactful role. “If we can set it up correctly, IFE will be a big piece of the Laboratory’s long-term vision,” says Ma. “IFE plays off of our history and all of our strengths, and it is critical for long-term national security.”
The key concept in today’s newsletter is 国家重大战略实施和重点领域安全能力建设, in abbreviation in Chinese as 两重 liǎng zhòng.
In English, it is translated officially as the implementation of major national strategies and building up security capacity in key areas, hereinafter referred to as “Two Major Undertakings.”
To systematically address funding shortages facing some major projects for building a great country and advancing national rejuvenation, it is proposed that, starting this year and over each of the next several years, ultra-long special treasury bonds be issued. These bonds will be used to implement major national strategies and build up security capacity in key areas. One trillion yuan of such bonds will be issued in 2024.
As of now, the 700 billion yuan in ultra-long-term special treasury bonds allocated for the “two major undertakings” has been distributed in three batches to specific projects.
A total of 1.3 trillion yuan of ultra-long special treasury bonds will be issued, 300 billion yuan more than last year.
735 billion yuan will be earmarked in the central government budget for investment. We will put ultra-long special treasury bonds to good use, increase ultra-long-term loans and other types of financing support, and strengthen top-down organization and coordination to ensure greater support for the implementation of major national strategies and security capacity building in key areas.
A simultaneous Finance Ministry budget plan [archived PDF] rounds up the overall central government spending for the Two Major Undertakings to 800 billionyuan in 2025.
In yuan terms, the much-touted new governmentsubsidies to households pale in comparison with the two major undertakings.
Ultra-long special treasury bonds totaling 300 billion yuan will be issued to support consumer goods trade-in programs. This represents an increase of 150 billion yuan over the previous year.
Now that the 2025 money has been spent by July and China is drawing up its next Five-Year Plan for 2026-2030, will there be more such projects in the future?
In the next step, during the formulation and implementation of the 15th Five-Year Plan, the “two major undertakings” will continue to occupy an important place, be organically incorporated into the new five-year plan, and form close alignment and sustained momentum with major national strategies, major plans, major projects, and key initiatives…
…Such a major strategy will be pursued with persistence—it will not remain rhetorical, nor will it be reversed abruptly.
He did not cite a source of information in his article.
Continuing with his lecturing style, Dong, now Executive Vice Director of China Institute for Development Planning, Tsinghua University, rebuked some unspecified market analysis that had observed the investments just were a one-time boost shot.
Some market institutions once analyzed that when China’s economy was facing short-term difficulties and challenges, the launch of the “two major undertakings” was mainly aimed at expanding investment in the short term to stabilize growth. Such a view clearly lacks a professional understanding of the decision-making intentions and logic, fails to properly grasp the relationship between the short term and the medium-to-long term, as well as between objectives and means, and inverts the proper order of priorities—a misconception that needs to be pointed out and corrected.
Dong also highlighted what he said was the unusual nature of the “strategic move,” including that central government debts fueled the investments, and they were selected “top-down,” rather than primarily relying on local government proposal or input.
The two undertakings were formally submitted for deliberation at the 2024 National People’s Congress after the central leadership made its decision and arrangements…
The central authorities have shown firm determination in this work, adopting the ultra-long-term special treasury bond—a macro policy tool that has rarely been used. Compared with several past issuances of special treasury bonds, the funding arrangement for the “two major undertakings” spans a longer cycle, has a broader scope of application, and will continue to advance in the next stage. It can be said that the scale and intensity are unprecedented. In 2024, a total of 700 billion yuan in ultra-long-term special treasury bonds was allocated, and in 2025, the figure is 800 billion yuan, all of which have now been fully disbursed.
The organization of the “two major undertakings” construction is top-down, completely different from the past practice in the investmentsector where projects were determined through bottom-up applications. The purpose is to facilitate the smoother downward transmission of the needs of major national strategies. Relevant [central] government departments, by identifying shortcomings and weaknesses, specifying key areas, and refining project requirements, have ensured that the project list is no longer a collection of fragmented local items. Instead, projects are planned in an integrated manner by category and sector, with strengthened guidance for key regions, more targeted measures, and clearer standards.
Although an exhaustive list of the 1,459 projects does not appear to be available to the public, the “security capacity” build-up in the two major undertakings should be understood in broad terms, and Dong claims the investments put China on a sounder footing globally now that Donald Trump rules America again.
In recent years, the central authorities have emphasized security awareness and bottom-line thinking in development planning, a shift closely related to changes in the international situation. The closer China’s economy becomes intertwined with the global economy, the more comprehensive its considerations must be regarding issues such as food security, energy security, industrial security, and ecological security. The second “undertaking” in the “two major undertakings”—the strengthening of security capabilities in key areas—is precisely a forward-looking arrangement. The dramatic changes in the international environment since the beginning of 2025 have further underscored and confirmed the necessity of enhancing security capabilities, fully demonstrating that the central authorities’ thinking and deployment have been prescient and ahead of the curve.
by Dong Yu, Executive Vice President, Institute for China Development Planning, Tsinghua University
The issuance of ultra-long-term special treasury bonds to support the implementation of major national strategies and the building of security capacities in key areas (hereinafter referred to as the “two major undertakings”) has become one of the hottest topics in China’s economy in recent years. Any observation of China’s present and future economic trajectory must include research and analysis of these two undertakings. More than a year has passed since the initiative was launched, making it both necessary and timely to evaluate its effectiveness, understand its operating mechanisms, and look ahead to its prospects.
The “Two Major Undertakings” Are by No Means Ordinary Policy Measures
In terms of decision-making background and process, as well as policy intensity and scope, the launch and implementation of the two major undertakings stand out from other policies. They represent a top-level design initiative.
Understanding a policy starts with its background. From the sequence of events leading to the proposal, this was a proactive, historic choice. The two undertakings were formally submitted for deliberation at the 2024 National People’s Congress after the central leadership made its decision and arrangements. The timing was significant: the 20th Communist Party of China National Congress had laid out a series of major long- and medium-term strategic initiatives that needed concrete engineering projects to push forward. China was midway through two Five-Year Plans, yet strategic advancement could not wait. The central leadership thus introduced the two major undertakings as a groundbreaking initiative.
Strategically, the undertakings directly address the needs of advancing long-term objectives. From the outset, they have been aimed squarely at the goals of Chinese modernization. By breaking down these goals into specific tasks and identifying the most difficult bottlenecks, the undertakings found their points of focus. Some of these tasks might take decades for other countries to achieve, but China has chosen not to delay—tackling them head-on at the starting stage of the new journey toward modernization. This model is uniquely Chinese and has been proven by history to be a key factor in China’s remarkable development successes.
The undertakings are also highly forward-looking—a “first move” by the central leadership. In recent years, national development planning has placed greater emphasis on security and on guarding the bottom line, in response to changes in the international environment. The closer China’s economy is linked to the global economy, the more comprehensive its considerations must be on food security, energy security, industrial security, and ecological security, and other issues. The second “major” in the initiative—security capacity building in key areas—is an arrangement made in anticipation of future challenges. The sharp changes in the international environment since 2025 have only highlighted and validated the necessity of strengthening security capacities, demonstrating that the central leadership’s thinking and arrangements were ahead of the curve.
The undertakings also have a strong overall and systemic quality, constituting a key move in macroeconomic governance. They focus on areas of outstanding importance to economic and social development and have a high degree of relevance to the overall development landscape. The policy toolkit they employ integrates investment, fiscal, science and technology, education, social, and ecological policies. This comprehensive package embodies the use of systems thinking to drive development and will significantly impact all aspects of the economy and society.
A Manifestation of Central Will
Extraordinary measures are for extraordinary tasks. The strategic objectives of Chinese modernization are long-term undertakings, and the two major undertakings provide the foundational support through systematic design and substantial funding.
The central leadership has committed to this initiative by adopting the rarely used macroeconomic tool of ultra-long-term special treasury bonds. Compared with previous special bond issuances, the funding for the two undertakings spans a longer cycle and serves a wider range of purposes, with plans for continued implementation. In both scale and intensity, this is unprecedented: 700 billion yuan in 2024 and 800 billion yuan in 2025, all of which has already been allocated.
In terms of priorities, it vividly reflects the principle of “concentrating resources to accomplish major undertakings.” The focus areas include urban–rural integration, regional coordination, high-quality population development, food security, energy and resource security, ecological security, and self-reliance and strength in science and technology—all crucial to building a strong nation and achieving national rejuvenation. These require coordinated planning and advancement. In just over a year, the high-level requirements have been translated into batches of concrete projects, reflecting the efficiency of implementation.
Project selection is guided by the principle that only the central government can resolve these issues. Some involve urgent development bottlenecks with significant obstacles that cannot be overcome by conventional means, such as scientific and technological breakthroughs, high-standard farmland construction, and upgrading the quality of higher education. Others are long-desired but previously unachievable projects that lack local willingness or capacity to implement, such as major cross-regional infrastructure, cross-basin wastewater treatment, and urban underground utility upgrades.
The organization of the “two major undertakings” construction is top-down, completely different from the past practice in the investmentsector where projects were determined through bottom-up applications. The purpose is to facilitate the smoother downward transmission of the needs of major national strategies. Relevant [central] government departments, by identifying shortcomings and weaknesses, specifying key areas, and refining project requirements, have ensured that the project list is no longer a collection of fragmented local items. Instead, projects are planned in an integrated manner by category and sector, with strengthened guidance for key regions, more targeted measures, and clearer standards.
A Combination of “Hard” and “Soft” Measures
From the start, the undertakings were designed not only to fund “hard” engineering projects but also to include comprehensive arrangements for “soft” institutional and policy measures—an important innovation.
The emphasis on soft measures is pragmatic. Given the high importance and public nature of the projects, long-term mechanisms must be designed to ensure smooth progress during construction and sustainable operation thereafter. This includes drafting specialized plans to provide strategic guidance, introducing targeted policies to improve funding efficiency, and innovating institutional arrangements to safeguard implementation.
Similarly, in the quality undergraduate expansion program, mechanisms play a guiding role: schools effectively implementing expansion plans receive increased support, while those performing poorly see reduced support; universities without expanded undergraduate admission plans are generally excluded from special bondfunding. Disciplines and programs are adjusted dynamically to align talent training with economic and societal needs.
Directly Relevant to Everyone
The nature of the undertakings is not determined by project size but by their strategic objectives and significance. As long as they align with major national strategies, they are included—whether as large standalone projects, such as high-speed rail along the Yangtze River, or as “project packages,” such as Yangtze Riverwastewater treatment composed of multiple treatment facilities. This flexible, problem-oriented approach allows better alignment with public needs.
As projects break ground and enter operation, their benefits to people’s livelihoods will become increasingly evident. Observers should not see the undertakings as distant from daily life; they will bring tangible improvements to everyone’s quality of life.
For example:
Urban underground pipelines: Upgrades to gas, water, and heating systems will greatly improve safety and resilience. Renovation of old gas pipelines is nearing completion, reducing accident rates by over 30%. Eliminating hidden risks in unseen places increases residents’ sense of security.
Food security: Gradually converting all permanent basic farmland into high-standard farmland will stabilize grain output and enhance food safety. Higher standards mean safer products, so people will eat with greater confidence.
Yangtze River protection: Building or upgrading over 60,000 kilometers of sewage pipelines in the Yangtze Economic Belt will greatly improve the river’s ecological environment and resolve long-standing public concerns.
Transportation: Creating the shortest Shanghai–Chengdu high-speed rail corridor (approx. 1,900 km) will connect the Yangtze River Delta, the middle Yangtze region, and the Chengdu–Chongqing area more quickly, cutting travel time nearly in half and boosting east–west connectivity.
Ecological security: Implementing the “Three-North” shelterbelt project over 130 million mu (93 million hectares), with good survival rates for trees, shrubs, and grasses, will safeguard northern ecological security and create new income opportunities.
Higher education: “Double First-Class”universities will see markedly improved conditions, with over 500,000 new standard dorm beds. Quality undergraduate enrollment will rise by 16,000 in 2024 and over 20,000 in 2025, giving more students access to quality education and ensuring basic living needs for those from low-income families.
A Bold Stroke in the History of Development
The two major undertakings are a major decision by the CPC Central Committee and the State Council, aimed at the overall strategy of building a strong country and achieving national rejuvenation. They play an irreplaceable role in advancing Chinese modernization.
They are not short-term measures but focus on medium- to long-term development. Some market institutions once analyzed that when China’s economy was facing short-term difficulties and challenges, the launch of the “two major undertakings” was mainly aimed at expanding investment in the short term to stabilize growth. Such a view clearly lacks a professional understanding of the decision-making intentions and logic, fails to properly grasp the relationship between the short term and the medium-to-long term, as well as between objectives and means, and inverts the proper order of priorities — a misconception that needs to be pointed out and corrected.
Since implementation began, the undertakings have provided important support for economic stability. Although their starting point was not short-term growth, the resulting investment has boosted employment and consumption, helping to expand domestic demand and stabilize growth. In the next step, during the formulation and implementation of the 15th Five-Year Plan, the “two major undertakings” will continue to occupy an important place, be organically incorporated into the new five-year plan, and form close alignment and sustained momentum with major national strategies, major plans, major projects, and key initiatives.
They will also bolster the country’s core competitiveness. As foundational support for Chinese modernization, they will strengthen factor security and resolve long-term bottlenecks, with far-reaching significance for shaping China’s development prospects. In an era of intensifying major-power competition, they will provide stable expectations and significantly enhance China’s capacity to manage international uncertainty. Such a major strategy will be pursued with persistence—it will not remain rhetorical, nor will it be reversed abruptly.
Though implementation has only recently begun, the undertakings’ historic role will continue to grow over time. In the future, looking back, they will surely stand as an important part of the “China story” and leave a bold stroke in the history of the People’s Republic’s development.
by Emmanuel A. San Andres and Glacer Nino A. Vasquez
Harnessing new tools to strengthen transparency and accountability can help APEC economies combat corruption and build public trust.
The Code of Hammurabi is one of humanity’s oldest surviving legal texts. Etched in basalt nearly four millennia ago, one of the many crimes it proscribes is corruption by a judge, for which the punishment is a hefty fine—“twelve times the fine set by him in the case”—plus removal and perpetual disqualification from office. Today, laws are published online rather than on stone tablets, but corruption remains a scourge across societies.
APECeconomies have long relied on oversight mechanisms such as audits, procurement rules, and internal checks to prevent, detect and prosecute corruption. These tools have been effective in fighting corruption, and they remain essential. But at the same time, new technology has also opened new pathways for corruption: The discreet meeting at a coffeeshop may now occur over an encryptedmessaging app, and the cash-filled envelope replaced by a cryptocurrency transfer.
It is also important to recognize the central role of human and institutional elements in anti-corruption efforts. Emerging technologies are not a silver bullet; they will only be effective if they are well integrated into government processes and are aligned with the skills of the people who need to use them. Training and capacity building will be essential to bridge capability gaps, while a committed leadership will be needed to implement the legal reforms and oversight structures needed to ensure effective adoption.
Buy-in from anti-corruption stakeholders across government, the private sector and civil society is also crucial to this pursuit. Technologies like AI/ML and advanced analytics require large volumes of reliable data, requiring cooperation and information sharing. Public understanding and trust, ethical use of data and equitable access to technology are all essential to ensuring long-term success.
APECeconomies are at different stages of readiness to adopt these emerging technologies. While some economies have yet to develop adequate digital infrastructure, human capital and institutional structures, others are already in a position to expand or integrate more advanced anti-corruption tools into their day-to-day processes. Capacity building, information sharing and dialogue can help narrow this gap while learning from the experiences of those ahead.
by Mohammad Al-Shehri, Assistant Economist & Omar Al-Nakib, Head of MENA Research
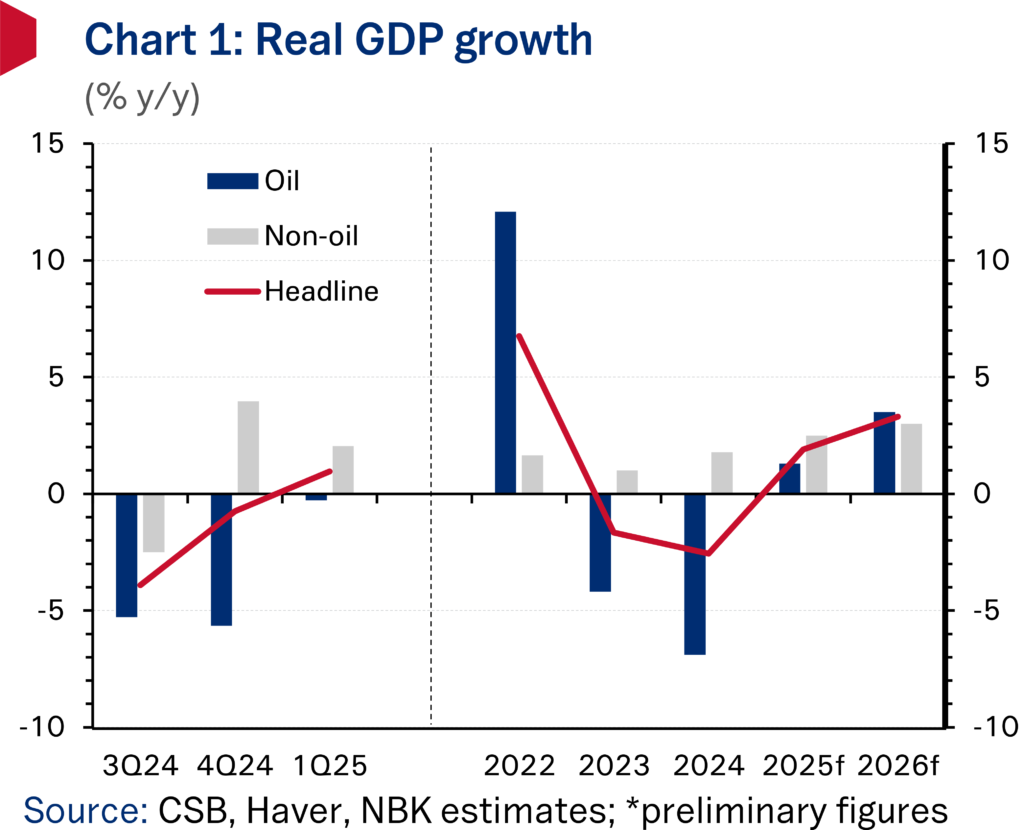
Preliminary official figures show GDP expanding 1% y/y in Q1 2025 following seven consecutive quarters of contraction, helped by a less severe downturn in oil output. With the negative effects of earlier voluntary oil production cuts beginning to fade, oilGDP recorded only a marginal decline, the softest since Q2 2023. Growth in non-oil activity remained positive though eased, weighed by a moderation in the manufacturing, real estate, and transportsectors. The near-term outlook for GDP is one of positive growth, lifted by rising oil production after Kuwait started to restore 135 kb/d of oil output cuts between April and September 2025, while the non-oilsector should also register further steady gains.
Non-oil GDP growth softens in Q1 2025 after strong performance in Q4 2024
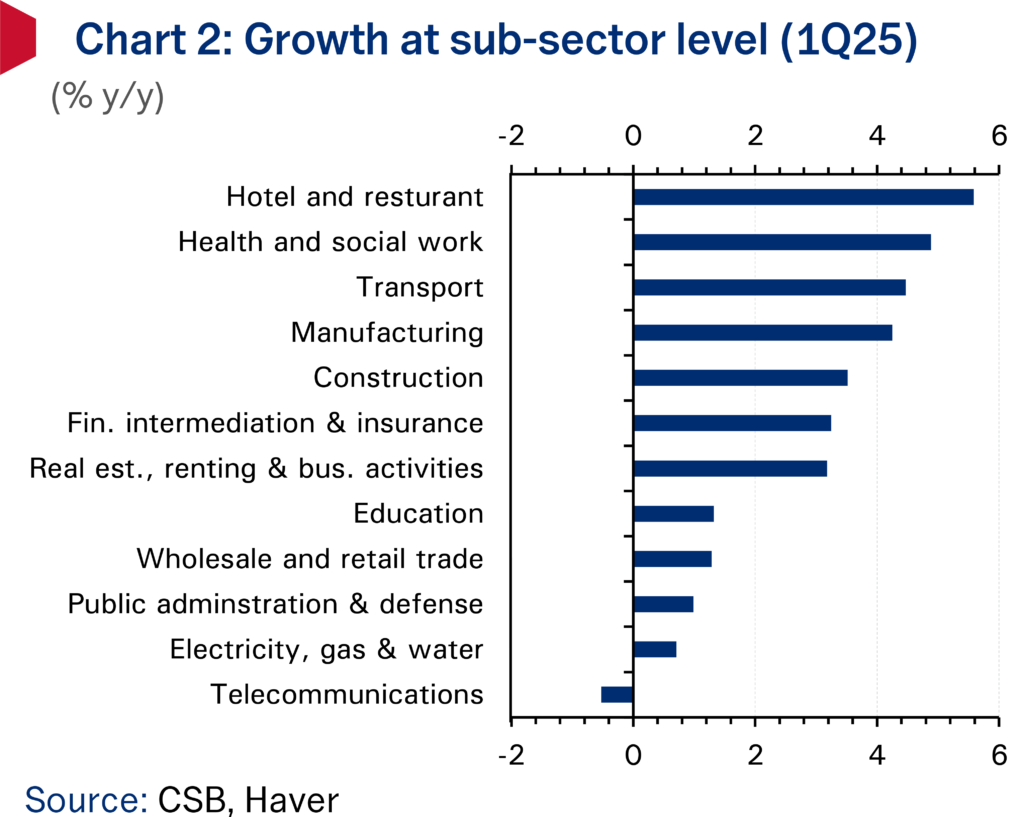
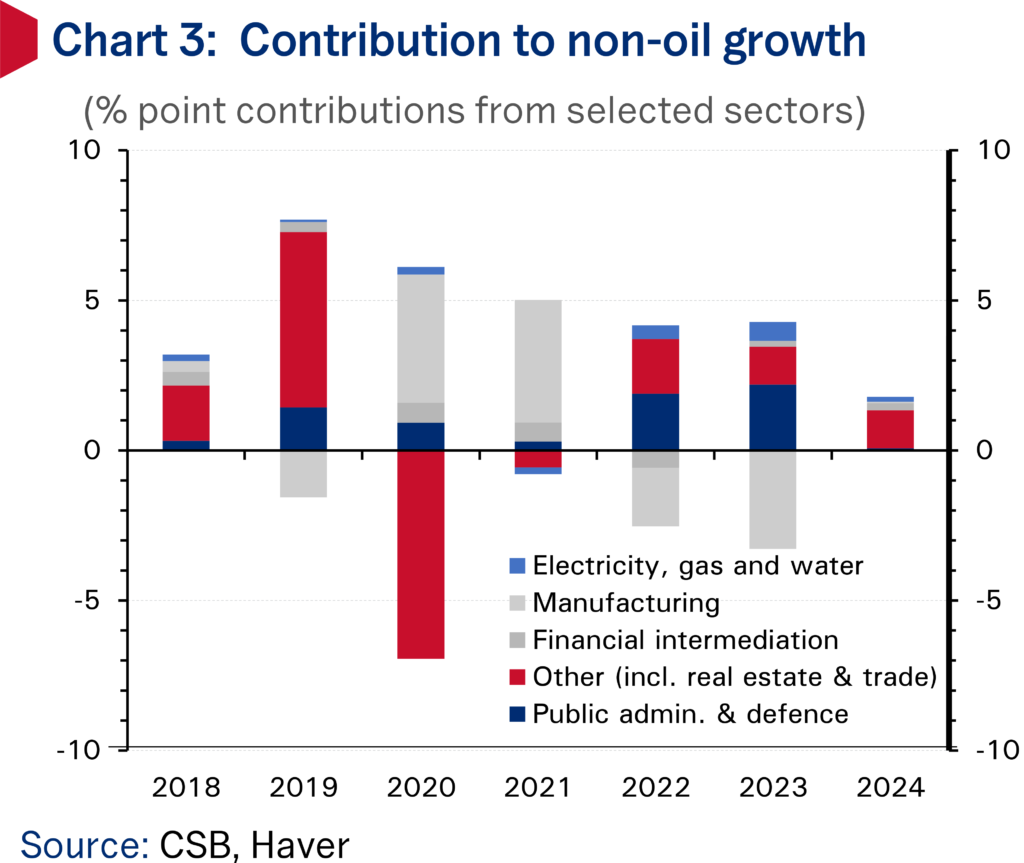
Growth in the non-oilsector weakened in Q1 2025, slowing to 2% y/y compared to 4% recorded in the prior quarter. (Chart 1.) The softer expansion in non-oil activity reflected, among other things, a moderation in the manufacturingsector, where activity grew at a still-solid 4.3% despite a decline in refined petroleum products output but slowed notably from the 12.2% reading registered in Q4 2024. Growth in other sectors including real estate, wholesale & retailtrade, transport, and education also slowed. Offsetting the slowdown was stronger expansion in the non-oileconomy’s largest segments: public administration and defense as well as financial intermediation and insurance, which grew 1% and 3.2% y/y, respectively. (Chart 2.)
Oil sector logs marginal contraction, set to return to growth in Q2
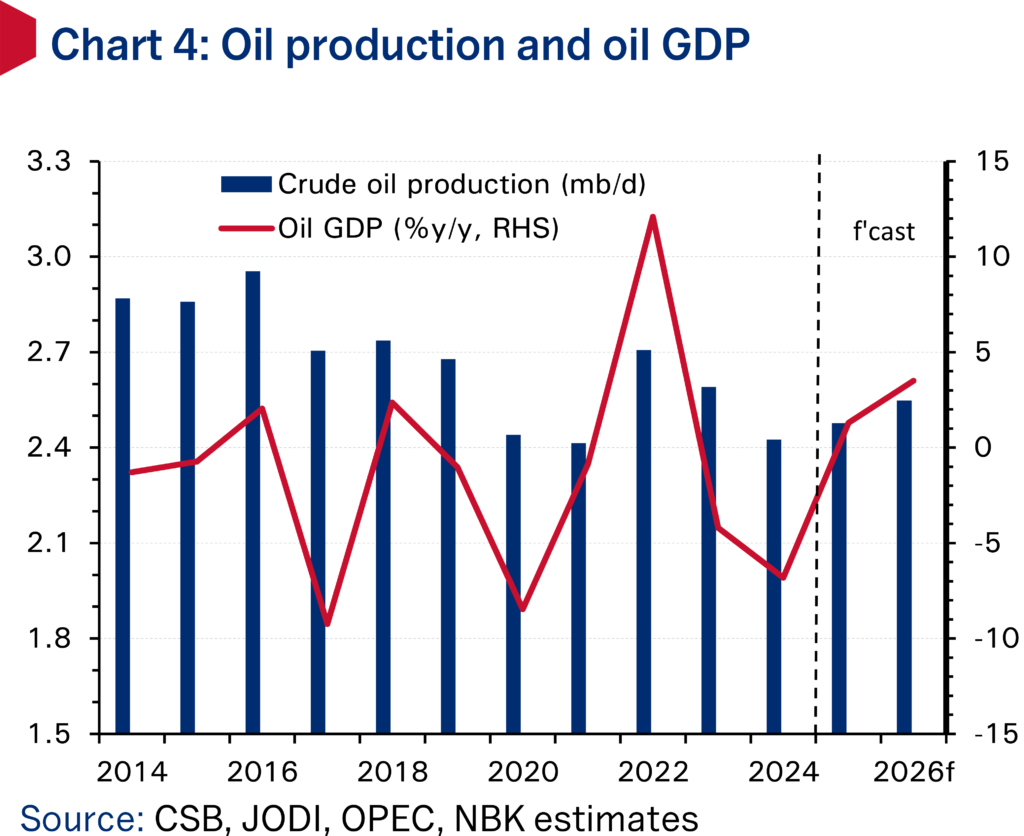
The contraction in oilGDP eased significantly to -0.3% y/y from -5.7% y/y in Q4 2024, registering the softest rate of decline since Kuwait embarked on cutting oil production in Q2 2023 after participating in the voluntary cuts scheme with 7 other OPEC+ members. (Chart 4.) Kuwait’s oil production averaged 2.415 mb/d in Q1 2025, a 0.7% decline from the same quarter last year, according to OPEC secondary sources. However, oilsector fortunes are set to shift in Q2 2025 and thereafter, after the OPEC-8 member alliance started unwinding the 2.2 mb/d voluntary cut tranche in April 2025. Originally planned to be unwound over the course of 18 months, OPEC+ has accelerated the pace of supply hikes with output now on a path to be fully restored in September, a full year ahead of schedule. For Kuwait, crude production rose by 0.5% q/q in Q2 to 2.426 mb/d and is set to accelerate further to average 2.533 mb/d in H2 2025. With the oil market so far able to absorb the additional OPEC and global supply and oil prices currently holding near $70/bbl, an upside risk to our oilsector outlook involves the potential unwinding of the outstanding OPEC-8 voluntary cuts (1.66 mb/d), of which Kuwait’s share is 128 kb/d.
Growth heading back into positive territory in 2025
Growth in total GDP is set to remain on a positive trajectory in the near term, buoyed by further steady expansion in non-oileconomic activity and increased oil production. Non-oilGDP is set to benefit from the government’s reform drive which includes the recent passing of the debtlaw that could catalyze the implementation of key development projects and the potential approval of the ‘mortgage’ law later in 2025, which could spur higher household borrowing and consumer spending. Economic indicators for Q2 2025 pointed to a healthy pace of non-oileconomic activity. The key ‘output’ and ‘new orders’ balances in the non-oilprivate sectorPMI gauge both averaged a very robust 57+ in Q2 2025, real estate activity continued to expand at a robust pace with earlier price falls in the residentialsector abating, while credit growth stood at a healthy 5.5% y/y in May, and could benefit in coming months if interest rates are reduced further.
Nonetheless, there are also downside risks to the outlook. Local consumer spending growth (according to central bankcardtransactions data) turned negative in Q1 2025, extending the weakening trend now observed for more than a year. The government’s ongoing fiscal consolidation push will also weigh on wage and job growth. Overall, we see GDP growing 1.9% this year, boosted by expansions in both the oil and non-oilsectors of 1.2% and 2.5%, respectively.
[from NBK Group’s Economic Research Department, 21 November, 2024]
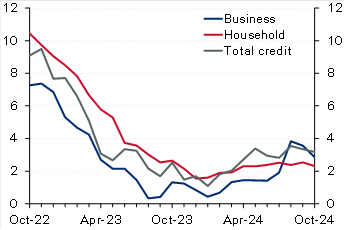
Kuwait: Solid credit growth in October driven by household credit. Domestic credit increased by a solid 0.4% in October, driving up YTD growth to 2.9% (3.2% y/y). The recovery in household credit continued, with growth in October at a solid 0.5%, resulting in a YTD increase of 2.4%. While y/y growth in household credit remains a limited 2.3%, annualized growth over the past four months is a stronger 4.7%. Businesscredit inched up by 0.2% in October, pushing YTD growth to 3.6% (2.9% y/y). Industry and trade drove businesscredit growth in October while construction and trade are the fastest growing YTD at 17% and 8%, respectively. In contrast, the oil/gas sector continued its downtrend, deepening the YTD decrease to 13%. Excluding the oil/gas sector, growth in business credit would increase to a relatively good 5% YTD. Looking ahead, the last couple of months of the year (especially December) are usually the weakest for businesscredit, likely due to increased repayments and write-offs, but it will not be surprising if the recovery in household credit is generally sustained, especially given the commencement of the interest rate-cutting cycle. Meanwhile, driven by a plunge in the volatile public-institution deposits, resident deposits decreased in October, resulting in YTD growth of 2.4% (4.2% y/y). Private-sectordeposits inched up in October driving up YTD growth to 4.5% compared with 10% for government deposits while public-institution deposits are a big drag (-14%). Within private-sector KD deposits, CASA showed further signs of stabilization as there was no decrease for the third straight month while the YTDdrawdown is a limited 1%.
Chart 1: Kuwait credit growth
(% y/y)
Source: Central Bank of Kuwait (CBK)
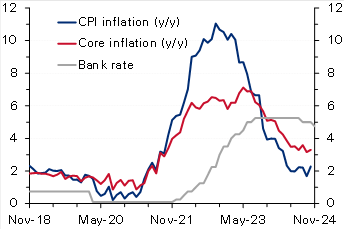
Chart 2: UK inflation
(%)
Source: Haver
Egypt: IMF concludes mission for fourth review, sees external risks. The IMF concluded its visit to Egypt after spending close to 2 weeks, holding several in-person meetings with the Egyptian authorities, private sector, and other stakeholders. The IMF released a statement mentioning that the current ongoing geopolitical tensions in the region in addition to an increasing number of refugees have affected the external sector (Suez Canal receipts down by 70%) and put severe pressure on the fiscal front. The Fund acknowledged the Central Bank of Egypt’s commitment to unify the exchange rate, maintain the flexible exchange rate regime, and keep inflation on a firm downward trend over the medium term by substantially tightening monetary policy. It also highlighted that continued policy discipline was also a key to containing fiscal risks, especially those related to the energy sector. The Fund, as always, re-iterated the need for promoting the private sector mainly through an enhanced tax system and accelerating divestment plans of the state firms. Finally, it also said that the discussions would continue over the coming days to finalize the agreement on the remaining policies and reform plans. However, the release did not provide any clear hints about the conclusion on the government’s earlier request to push the timeline of some of the subsidy moves.
Oman: IMF completes article IV with a strong outlook for the economy in 2025. Oman’s economy continued to expand with growth reaching 1.9% in the first half of 2024 (versus 1.2% in 2023), despite being weighed down by OPEC+ mandated oil production cuts as non-oil GDP grew a stronger 3.8% y/y in H1 (versus 1.8% in 2023). The fiscal and current account balances remain in a comfortable situation evident by a decline in public sectordebt and the recent rating upgrade to investment grade. The Fund expects Oman’s economic growth to see a strong rebound in 2025, supported by higher oil production. It also believes that fiscal and current account balances will remain in surplus but at lower levels. Key risks to the outlook stem from oil price volatility and intensifying geopolitical tensions. The IMF also mentioned that further efforts are needed to raise nonhydrocarbon revenues through more tax policy measures and the phasing out of untargeted subsidies which should help in freeing up resources to finance growth under the government’s diversification agenda.
UK: Inflation rises more than forecast, reinforcing BoE’s caution on rate cuts. UKCPIinflation increased to 2.3% y/y in October from 1.7% the previous month, slightly above the market and the Bank of England’s forecast of 2.2%. On a monthly basis too, inflation rose to 0.6%, a seven-month high, from September’s no change. The steep rise was mainly driven by an almost 10% rise in the household energy price cap effective from October. Core inflation also accelerated to 3.3% y/y (0.4% m/m) from 3.2% (0.1% m/m). While goods prices continued to fall (-0.3% y/y), service prices rose at a faster rate of 5% from 4.9%. Recently, the Bank of England had cautioned about inflation quickening next year (projecting a peak rate of 2.8% in Q3 2025), citing the impact of higher insurance contributions and rising minimum wages as outlined in the latest government budget. Therefore, with inflation rising above forecast, the bank will likely slow the pace of monetary easing after delivering two interest rate cuts of 25 bps earlier, with markets now seeing only two additional cuts by the end of 2025.
Eurozone: ECB warns of fiscal and growth risks in its latest Financial Stability Review [archived PDF]. In its most recent Financial Stability Review (November) [archived PDF], the European Central Bank warned that elevated debt and fiscal deficit levels and anemic long-term growth could expose sovereign debt vulnerabilities in the region, stoking concerns of a repeat of the 2011 sovereign debt crisis. Maturing debt being rolled over at much higher borrowing rates raising debt service costs poses risks to countries with little fiscal space and leaves certain governments exposed to market fluctuations. The bank also emphasized the risks of high equity valuations, low liquidity and a greater concentration of exposure among non-banks. Moreover, it sees current geopolitical uncertainties and the possibility of more trade tensions as heightening risks. The Eurozone’s current government debt-to-GDP ratio stands at 88%, but the underlying data suggest a much more precarious situation with Greece, Italy, and France’s ratios at 164%, 137% and 112%. Recently, concerns about France’s high fiscal deficit (around 5.9% of GDP) and elevated debt levels saw yields on the country’s bonds rise steeply, widening the spread gap with Germanbonds to the highest level in over a decade.
Disclaimer: While every care has been taken in preparing this publication, National Bank of Kuwait accepts no liability whatsoever for any direct or consequential losses arising from its use. Daily Economic Update is distributed on a complimentary and discretionary basis to NBK clients and associates. This report and previous issues can be found in the “News & Insight / Economic Reports” section of the National Bank of Kuwait’s web site. Please visit their web site, nbk.com, for other bank publications.
There is much debate about the effectiveness of Western sanctions, the Ukraine war’s implications for markets and the global economy, and what the West’s next steps should be. While there are few good options, some are clearly worse than others.
On the first question, although the sanctions have been less effective than Europe and the U.S. had hoped, they also are proving more onerous than the Kremlin claims. Russia’s central bank expects GDP to contract by 8-10% this year, while other forecasters expect a larger fall, together with longer-lasting damage to growth potential. Imports and exports have been severely disrupted, and inflows of foreign investment have essentially stopped. Shortages are multiplying, pushing inflation higher. At this point, the country no longer has a properly functioning foreign-exchange market.
The sanctions would have bitten much harder had the West not opted for a carve-out of Russia’s energy sector, and had many more countries joined the U.S. and Europe in the effort. Because that didn’t happen, Russia has not felt nearly as much pressure as it would have. Moreover, it has been able to continue trading through various side and back doors that will likely become increasingly important as long as the sanctions regime, as currently designed, continues.
Nonetheless, it is only a matter of time before the Russian economy experiences a harder hit. Inventories of imported goods – including many critical technological and industrial inputs – are dwindling fast, and many sectors are becoming less resilient. The cumulative damage to Russia’s economy over time will be significant and long-lasting – a fact that has not yet been fully captured by consensus medium-term forecasts.
The second question concerns global spillovers from the war and the sanctions regime. Most observers agree that Russia’s invasion has increased not just energy insecurity but also food insecurity, highlighting the fallout from the war’s disruption to Ukrainian agricultural exports. But there is still much debate about the West’s use of the economic nuclear sanctions option: the curbs placed on Russia’s central bank and on Russia’s use of the international payments system.
These curbs are far more intrusive than the usual mix of restrictions on sanctioned government and private sector trade and on individuals’ financial dealings. Yet, because they are not subject to any internationally agreed standards, guidelines, or checks and balances, they fall outside the purview of relevant global-governance bodies such as the Bank for International Settlements, the International Monetary Fund, and the World Trade Organization.
In a time of war, such oversight might seem like a nicety. But some worry that the sanctions could significantly reduce the dollar’s role as the world’s reserve currency and the U.S.financial system’s role as the primary global intermediary for other countries’ savings and investments. After all, a growing number of countries undoubtedly now feel more vulnerable to the reach of U.S. sanctions.
But it is impossible to replace something with nothing, which means that no significant loss of dollar or U.S. financial primacy will occur in the immediate future. Rather, the sanctions will lend further momentum to the gradual process of global economic fragmentation, which was also fueled a few years ago by the tariffs imposed by the Trump administration. More countries now have even more of a reason to pursue greater financial resilience and inherently inefficient forms of self-insurance.
That brings us to the third debate. With no end in sight for the war, what should the West do next? Fearing the implications for energy prices and the supply of gas to Europe, many in the West are tempted to call for a moratorium on any new sanctions – or even for additional carve-outs. Others, however, favor additional measures to hold Russia accountable for its indiscriminate attacks on Ukrainian civilians.
In any case, maintaining the current sanctions regime is not problem-free, owing to the twin objectives of pressuring Russia and limiting the economic disruption to Europe. Moreover, as European Commission President Ursula von der Leyen recently said, it feels as if Russia is “blackmailing” Europe by threatening to disrupt gas supplies at any moment. No wonder the Commission is urging member countries to cut consumption by 15%.
Doing so would undoubtedly have a severe short-term economic impact on European economies and the rest of the world, amplifying the “little fires everywhere” syndrome that I warned about in May. It is therefore critical that governments use their available fiscal space to provide targeted support to vulnerable segments of the population, as well as to fragile countries; and multilateral agencies must support developing countries through aid and a more operational debt relief framework. If done properly, this option would yield better outcomes in the medium and long term than the current strategy.
Muddling through risks bringing about the worst of all possible worlds. It is insufficient to dissuade Russia from continuing its illegal war; it is fueling deeper fragmentation of the international monetary system; and it is not even protecting Europe from a winter gas disruption.
Oman shipyard Asyad Dry Dock is expanding its capacity by 20% with a new floating dock as its current facilities are fully utilized.
by Marcus Hand
The shipyard, formerly Oman Drydock Company, is now part of the Asyad Group, the logistics arm of the Oman government. Management of the yard has been combined with shipowner Oman Shipping Company, and overseen by Dr. Irbahim Al Nadhairi, Chief Executive Officer, Shipping & Drydock.
“We have integrated the shipping and drydocking as the shipping service. The companies are still two legal separate entities but then we share the same executive team to be more efficient,” Dr. Ibrahim told Seatrade Maritime News in an interview at Posidonia 2022.
On the shipping side of the business the group owns a fleet of 65 ships with plans to increase the fleet to over 100 vessels over the next five years. He explains that with such a size of fleet the shipowner needed a quality shipyard so it made sense to work together.
Asyad maintains most, if not all its fleet at the shipyard in Oman, accounting for around 15% of its business. While part of the same group Dr. Ibrahim says it does not send its ships to the yard “by default,” and they have to make sure it is competitive as it needs to be for their third-party customers.
Business has been growing for the shipyard and it experienced a spike in the first half of this year as Chinese capacity has been taken out of the market by COVID restrictions pushing work to yards in other parts of the world. “So, we could see there was a big hike in the number of ships, not only for Asyad Dry Dock, but the entire region as well,” Dr. Ibrahim said.
“The next 12 months I believe the ship repair industry will still continue to flourish on our side.”
The shipyard’s two 600,000 DWTdrydocks are already operating at full capacity and this year sees it adding a floating dock with the capacity to handle vessels up to Panamax size.
“We’ve recently acquired a floating dock which is of Panamax size and we reckon that about 40% of the business in ship repair is within that Panamax size. The floating dock gives us around 20% extra capacity,” he said. It will increase the number of ships the yard can repair from 200 to around 240.
The floating dock is expected to arrive in Oman in the next six weeks, and following some dredging works be operational by the start of Q4 this year.
Greek owners are major clients of the shipyard and account for around 40% of business, and Dr. Ibrahim said they added two more Greek clients last week. “It seems we have a good reputation in the Greek market and between now and end of Q3 we have 27 ships in orderbook from the Greek market.”
Being able to deliver services efficiently and on time is of critical importance in the financially booming container sector.
“Today when you talk about bringing a container ship into a shipyard time really is money,” Dr. Ibrahim said. If a container ship owner says a ship will be in the yard for 15 days the owner will expect work to be completed in 12 days.
‘Further Action Is Needed’ As MEPC 78 Gets Underway
IMO Secretary General Kitack Lim hailed the 78th session of the Marine Environment Protection Committee as an opportunity to be brave and lead by example on decarbonization.
by Gary Howard
MEPC 78 has a packed agenda with the opportunity to consider and progress IMO’s work on cutting greenhouse gas emissions from ships.
At the last MEPC meeting, a revision process was agreed to strengthen the IMO’s initial GHG strategy which was adopted in 2018. A strengthened version of that initial strategy is due in mid-2023 at MEPC 80.
“Whilst progress has been made on many of the measures set out in the Initial Strategy, I am sure that we can all agree that further action is needed. Your discussions this week will chart the way forward for the decarbonization of international shipping,” said Lim.
“It is therefore of utmost importance that IMO continues to deliver concrete progress in transitioning international shipping from fossil fuels to low and zero-carbon alternatives.”
Member states at MEPC 78 will also consider adoption of guidelines to support short-term measures on GHG emissions, including correction factors for carbon intensity, EEXI calculation methodology and revised SEEMP.
Calculations on the GHG impact of fuels will be discussed, as ISWG-GHG 11 reports progress on developing lifecycle GHG assessment guidelines. Well-to-wake and tank-to-wake calculations are in scope, with the aim of giving fuel users a full picture of the impact of the production and use of the fuels they choose.
“Your constructive discussions on these topics will enhance the Committee’s evidence-based decision making when further considering proposals for mid-term GHG reduction measures,” Lim told Member States.
“I would like to take this opportunity to express my deepest appreciation to all Member States, and observer delegations, and especially the Chair of the Working Group on reduction of GHG emissions from ships, Mr. Oftedal of Norway, for the extraordinary effort and dedication in ensuring the successful outcome of both intersessional meetings.”
Houston Begins $1.1Bn Ship Channel Widening
The Port of Houston kicked off its the long-awaited billion dollar dredging scheme, the Houston Ship Channel Widening and Improvement Project 11 last week.
by Michele Labrut
The $1.1bn expansion of the Houston Ship Channel, which has been in planning for more than a decade is finally underway.
After more than a decade of planning, Project 11 will allow the ship channel to accommodate an additional 1,400 vessels per year and could generate up to $134bn more annually in economic impact once completed. The channel currently accommodates about 8,200 vessels and 215,000 barges each year, hauling more than 247m tons of cargo.
“This project will enable Port of Houston to continue to grow and respond effectively to whatever the future demand in the supply chain has to offer,” Port of Houston Executive Director Roger Guenther said in a statement.
Port of Houston is a 40-2 km-long complex of nearly 200 private and public industrial terminals along the 583.6 km-long manmade Houston Ship Channel, which connects the port to the Gulf of Mexico.
Port of Houston and the Army Corps of Engineers signed an agreement in August giving the port permits to start dredging the federal waterway. Great Lakes Dredge and Dock Co. was awarded a $95m contract in October, which also includes oyster mitigation and construction of a bird island. The channel widening and deepening project is scheduled to be completed in 2025.
EU Transport Commissioner Focuses on ‘Solidarity Lanes’ and Sanctions
As the global food crisis deepens and millions of tons of Ukraine’s grain remain blocked in the Black Sea, EU Transport Commissioner Adina-Ioana Vălean has declared that all transport modes will be considered in setting up new Solidarity Lanes that bypass the Black Sea.
by Paul Bartlett
Her comments come as disrupted grain movements risk a global food crisis.
Speaking to journalists immediately prior to yesterday’s opening ceremony at Posidonia, she said that trucks, tracks, trains, transshipment and storage facilities will all contribute to new supply chains to ensure that exports from one of the world’s largest grain exporters can resume, at least in part, as soon as possible.
She said that the setting up of Solidarity Lanes would have important commercial implications for shipping and could even lead to changes in the sector’s business models.
Vălean also rejected criticism from prominent Greek shipowners who had claimed earlier in the day that sanctions imposed on Russia in the wake of its invasion on Ukraine won’t work. At a Maritime Leaders Summit staged by Capital Link on Monday, George Prokopiou and Evangelos Marinakis had both said that sanctions against Iran and Venezuela had been shown not to work and similar moves against Russia would not be effective either.
However, other sources pointed to the scale of the sanctions package that has severely impacted the Russian economy by disrupting key revenue generating sectors. Energy exports are the most obvious example and although Russian oil is still easily sold in India and China, for example, it is at deep discounts to global prices.
Meanwhile, LNG exports have also been hit and development of Arctic LNGsupply chains have also been severely affected. Within the next few months, Vălean said that Russian oil exports would be further disrupted by the withdrawal of insurance cover on shipping and transport arrangements.
UK’s climate change readiness has made ‘significant progress’
by Renee Karunungan on May 4, 2022
There is significant progress in the UK for reporting and implementing climate change adaptation, according to a new study led by TyndallUEA’s Katie Jenkins. Katie has created an Adaptation Inventory of adaptation actions happening based on official records of adaptation projects being implemented by both public and private sector, accompanied by a systematic review of the peer-reviewed literature of adaptation case studies.
Adapting to climate change means taking action to prepare for and adjust to current and predicted effects of climate change. Adaptation plays an important role in managing past, present and future climate risk and impacts. However, there is an “adaptation gap” where the distance between existing adaptation efforts versus adaptation needs is widening, according to the United Nations Environment Programme’s Adaptation Gap Report. Tracking national adaptation plans is deemed critical to support future decision-making and drive future actions.
According to the Committee’s assessment, adaptation planning for 2C and 4C global warming is not happening, and that the gap between future risks and planned adaptation has widened, delivering the minimum level of resilience.
Katie’s new Adaptation Inventory provides insight on what is currently being implemented, which helps policymakers and practitioners learn from existing knowledge and practical case studies.
“The Adaptation Inventory provides a consistent and easily searchable database which will continue to evolve. It can provide evidence on the specific types of adaptation implemented on the ground as well as provide more detailed insight into the specific examples of action being implemented. This has the potential to help and inform UK-based decision-making,” Katie said.
The Adaptation Inventory identifies and documents current and planned adaptation in the UK, and how it is being implemented through adaptation actions, the sectors where adaptation is occurring, and where the gaps remain. There were 360 adaptation actions identified in the Inventory, comprising 134 adaptation types. Out of these 360 adaptation actions, 80% have already been implemented.
The private sector accounts for 74% of the actions with water companies dominating. Regulatory frameworks, standards, and reporting requirements are key drivers required by water companies by the Regulator. For example, water companies are already required to plan their resilience to drought.
The most common types of adaptation actions are flood protection (12%), leakage reduction (4%), water metering (3%), property level flood protection (3%), operational improvements (3%), and back-up generators (3%). Most actions were categorized as structural and physical interventions. Other interventions were categorized as technological and ecosystem based.
The Adaptation Inventory also looks at the types of climate hazards being addressed. It found that 76% of the actions were in response to drought, 26% for extreme rainfall, 13% for flooding, and 11% for higher temperatures. One example of adaptation for drought is rainwater recovery using storage facilities available on the site, reducing the demand for fresh water during drought. For alleviating flooding, a water company is using afforestation. The London Underground has doubled the capacity of ventilation shafts on the Victoria line, which provide more air flow on hot days.
The Brain Bank has released findings from its first three years of operation, analyzing the brains of professional and non-professional athletes who donate them after death.
The researchers say 12 of the athletes’ brains showed signs of chronic traumatic encephalopathy (CTE), a condition associated with a range of psychiatric problems, ranging from mood and behavior disorders to cognitive impairment and dementia.
“CTE was identified in the brains of older former professionals with long playing careers, but also in younger, non-professional sportsmen and in recent professionals who had played under modern concussion guidelines,” the authors found.
“Screening for CTE in all deaths by suicide is probably impractical, but our finding suggests it should be undertaken if a history of repetitive head injury is known or suspected,” the authors say.
The authors note that brains donated to the bank are more likely to show signs of trauma because donation is often done when an athlete’s family have concerns about the role head trauma may have played in a person’s death or condition.
Nonetheless, they say: “Our findings should encourage clinicians and policymakers to develop measures that further mitigate the risk of sport-related repetitive head injury.”
One Step Closer to Hydrogen-Fueled Planes
Airbus to Test Zero-Emissions Aircraft, but How Does It Work?
Hydrogen fuel, touted by some as the fuel of the future, is seen as a potential solution for the deeply polluting aviation and shipping industries in a net-zero world: hydrogen burns cleanly, producing just energy and water vapor.
But while engineers have promoted hydrogen as a possible transport fuel since at least the 1920s, real-world technologies are still in their infancy, thanks to the destructive dominance of fossil fuels over the last century.
Airbus’ announcement, then, marks an important early step in a move towards making the sector compatible with net-zero.
“This is the most significant step undertaken at Airbus to usher in a new era of hydrogen-powered flight since the unveiling of our ZEROe concepts back in September 2020,” said Sabine Klauke, Airbus Chief Technical Officer, in a statement.
“By leveraging the expertise of American and Europeanengine manufacturers to make progress on hydrogen combustion technology, this international partnership sends a clear message that our industry is committed to making zero-emission flight a reality.”
“Our ambition is to take this aircraft and add a stub in between the two rear doors at the upper level,” said Glenn Llewellyn, Airbus’ Vice President of Zero Emissions Aircraft, in a promotional video on YouTube. “That stub will have on the end of it a hydrogen powered gas turbine.”
There will be instruments and sensors around the hydrogen storage unit and engine, to monitor how the system functions both in ground tests and in-flight. Up in the cockpit, instruments will need to be modified with a new throttle to change the amount of power the engine operates at, and a display for pilots to monitor the system.
Why Hydrogen Fuel?
Hydrogen, the most abundant element in the Universe, burns cleanly, and can be produced using renewable energy through the electrolysis of water (though it can be produced using fossil fuels, too).
Given that it’s so abundant, can be made from water, and combusts to produce water vapor, it can be a closed-loop energy system; the definition of renewable.
It’s also highly reactive: hydrogen gas, made up of two hydrogen atoms, can combust at extremely low concentrations. It can combust in response to a simple spark, and it’s even been known to combust when exposed to sunlight or minor increases in temperature. That’s why it’s a suitable replacement fuel for kerosene, but it’s also why the system needs to be tested for safety.
“Aviation is one of these things that everyone agrees needs hydrogen for decarbonization, because it’s not going to be possible to electrify long distance air travel in the next few decades,” explains Fiona Beck, a senior lecturer at ANU and convener of the Hydrogen Fuels Project in the University’s Zero-carbon energy for the Asia Pacific grand challenge. “We just don’t have the battery technologies.
“One kilogram of hydrogen has 130 times the energy of one kilogram of batteries, so in something like air travel, where weight is really important, there’s just no way you’re going to get batteries light enough to directly electrify air travel.”
That’s a very high-profile incident in which hydrogen proved deadly, but a proverbial boatload of hydrogen gas encased within a fabric covering is nothing like the fuel cells proponents of hydrogen fuel are creating in the modern era.
Nonetheless, the incident demonstrates why it’s important to ensure the safety and impregnability of fuel storage; a single spark can prove fatal (though that’s the case with existing fuels, too).
“The key will be to have really good storage containers for the hydrogen, and you’re going to have to re-engineer all the fuel delivery lines,” says Beck, “because you can’t assume that the systems that deliver kerosene safely to an engine are going to be suitable for delivering hydrogen.”
Ultimately, Beck says pre-existing, sophisticated hydrogen technologies, even if they aren’t derived from aviation, mean engineers aren’t going into this blind.
“We already use quite a lot of hydrogen in industry, which is very different than flying a plane full of hydrogen, but still, we know how to handle it relatively safely.
“So, it’s just about designers and engineers making sure that they consider all the safety aspects of it. It’s different, but not necessarily more challenging.”
Two Paths to a Hydrogen Fueled Future of Flight?
Beck notes that Airbus aren’t the only commercial entity exploring hydrogen as a fuel type. In fact, Boeing are incorporating hydrogen into their vision of a cleaner future, but in a different way.
“There’s a difference between just getting hydrogen and burning it in a modified jet engine and what Boeing are doing, which is using sustainable air fuels,” she says.
But what are sustainable air fuels (SAFs)? Beck says they’re made by combining hydrogen with carbon dioxide to make a sustainably-produced kerosene.
“The difference is that instead of getting fossil fuels and refining them, you start with hydrogen, which you would hope comes from green sources, and then you take some carbon dioxide captured from another industrial process, and you’re cycling the carbon dioxide one more time before it gets released.”
So, CO2 is still released into the atmosphere, but the individual flight is not adding its own new load of greenhouse gases to the amount. Instead, it essentially piggy-backs off a pre-existing quantity of emissions that were already produced somewhere else.
The type of fuel that wins out remains to be seen.
“It’ll be really interesting to see which approach we go for in the longer term,” Beck muses. “With synthetic air fuels, your plane engine doesn’t need to change at all, nothing about the demand side needs to change–it’s just kerosene.
“But then there’s issues, because you’re still using carbon dioxide.”
Some commentators see Boeing’s bet on SAFs as a more pragmatic approach that may help us usher in a less polluting age, quicker. On the other hand, if successful, the Airbus system can be fully carbon-neutral from fuel production through to combustion.
“Climate Adaptation by Itself Is Not Enough”: The Latest IPCC Report Installment
The Second of Three Reports Shows Our Vulnerabilities and How We Can Protect Them.
In the next part of its Sixth Assessment Report, released today, the IPCC has examined the world population’s vulnerability to climate change, and what must be done to adapt to current and future changes.
It’s the second of three sections of this report (Working group II)–Working Group I’s section, released last August, demonstrates that anthropogenic climate change is continuing, while Working Group III’s component, on mitigation, will be released in April. An overall report is coming in September.
The IPCC reports represent a phenomenal amount of work from hundreds of researchers and government officials. It synthesizes information from over 10,000 studies, with over 62,000 comments from expert peer reviewers.
Literally every sentence of the summary for policymakers has been agreed upon by consensus from a group of experts and government delegations–the line-by-line approval process alone takes a fortnight. The report in its entirety is a product of several years.
Given the time and expertise involved in making the report, its conclusions aren’t revelatory: the world is becoming increasingly vulnerable to the effects of climate change, poorest people are often the most at risk, and adaptation to these effects will force changes in our lifestyle, infrastructure, economy and agriculture.
While adaptation is necessary, it’s also insufficient. “It’s increasingly clear that the pace of adaptation across the globe is not enough to keep up with climate change,” says Professor Mark Howden, Working Group II’s vice-chair and director of the Institute for Climate, Energy & Disaster Solutions at the Australian National University.
Under the IPCC’s projected emissions scenarios, the climate could warm much more or slightly more, based on the volume of greenhouse gas released into the atmosphere.
“Depending on which of those trajectories we go on, our adaptation options differ,” says Howden.
On our current, business-as-usual trajectory, we can’t avoid the crisis, no matter how much we change our human systems to prepare for or recover from the ravages of climate change.
“Climate adaptation, risk management, by itself is not enough,” says Howden.
The report comes at a pertinent time for Australia, as southern Queensland and northern New South Wales experience dramatic flooding from high, La Niña-related rainfall.
“One of the clear projections is an increase in the intensity of heavy rainfall events,” says Professor Brendan Mackey, director of National Climate Change Adaptation Research Facility at Griffith University, and a lead author on the Australasian chapter of the report.
Mackey also notes that he has extended family members in Lismore, NSW, who today needed to be rescued from their rooftops as the town floods.
Howden says that while it’s hard to link individual disasters to climate change as they occur, he agrees that there are more floods projected for northern Australia.
“I think we can say that climate change is already embedded in this event,” adds Howden.
“These events are driven by, particularly, ocean temperatures, and we know very well that those have gone up due to climate change due to human influence.”
He points out that flooding is a common side effect of a La Niña event, of which more are expected as the climate warms.
Flooding is not the only extreme weather event that can be linked to climate change.
“We’ve observed further warming and sea level rise, we’ve observed more flood days and heat waves, we’ve observed less snow,” says Mackey.
“Interestingly, [we’ve observed] more rainfall in the north, less winter rainfall in the southwest and southeast, and more extreme fire weather days in the south and east.”
All of these trends are expected to continue, especially under high-emissions scenarios.
For Australians, the predictions the IPCC has made with very high or high confidence include: both a decline in agricultural production and increase in extreme fire weather across the south of the continent; a nation-wide increase in heat-related mortality; increased stress on cities, infrastructure and supply chains from natural disasters; and inundation of low-lying coastal communities from sea level rise.
The final high-confidence prediction is that Australian institutions and governments aren’t currently able to manage these risks.
“Climate change impacts are becoming more complex and difficult to manage,” says Professor Lauren Rickards, director of the Urban Futures Enabling Capability Platform at RMIT, also a lead author on the Australasian chapter.
“Not only are climatic hazards becoming more severe–including, sometimes, nonlinear effects such as, for example, tipping over flood levees that have historically been sufficient–but also those climatic hazards are intersecting in very, very complex ways. And in turn, the flow-on effects on the ground are interacting, causing what’s called cascading and compounding impacts.”
She adds that many local and state governments and the private sector have both recognized the importance of changing their practices to prepare for or react to climate extremes.
“We have these systems, these infrastructural systems–energy, transport, water, communications, for example–and it’s the need to adapt those at the base of a lot of the adaptation that’s needed,” says Rickards.
Australia is missing a large investment in research on how different places and systems can adapt to the changing climate.
“We’ve seen a really significant reduction in the research into what actions different individuals, communities, sectors, can take,” says Howden.
“And what that means is we don’t have the portfolio of options available for people in a way that is easily communicable, and easily understood, and easily adopted.”
Without this research, as well as work from local and Indigenous experts, some adaptations can even risk worsening the impacts of climate change.
“The evidence that we’ve looked at shows really clearly that adaptation strategies, when they build on Indigenous and local knowledge and integrate science, that’s when they are most successful,” says Dr. Johanna Nalau, leader of the Adaptation Science Research Theme at Cities Research Institute, Griffith University.
While the risks Australia faces are dramatic, things are much worse for other parts of the world. Nalau, who was a lead author on the report’s chapter on small islands, says that “most of the communities and countries are constrained in what they can do in terms of adaptation”.
In April, we will have access to the IPCC’s dossier on mitigating climate change and emissions reduction. But in the meantime, Working Group II’s battalion of researchers advocate for better planning for climate disaster, more research into ways human systems can adapt, sustainable and just development worldwide, and rapid emissions reduction.
“Adaptation can’t be divorced from mitigation, conceptually or in practice,” says Rickards.
“We need adaptation to enable effective mitigation. We need effective mitigation to enable adaptation to give it a chance of succeeding. At present, we’re not on track and we need to pivot quickly.”
Piecing Together Pandemic Origins
New Research Asserts Market, Not Laboratory, Is the “Unambiguous” Birthplace of SARS-CoV-2
by Jamie Priest
Now in our third year of woe, most of us are naturally focused on the end of the pandemic. The global death toll is approaching 6 million, and the world is desperately searching for signs the ordeal’s over.
But amid the future watching, a team of researchers have turned their attention back to the beginning, tackling the question that was once on everyone’s lips: where did SARS-CoV-2 originate?
Outlining their evidence in two preprints, researchers assert an “unambiguous” origin in the Huanan market in Wuhan, spilling over not once, but twice into the human population and kicking off a global health crisis.
The paired papers, which have yet to undergo peer review and publication in a scientific journal, critically undermine the competing, and controversial, alternative origin story that involves a leak–intentional or otherwise–from a nearby Wuhan virology lab where scientists study coronaviruses.
The Huanan market was an immediate suspect when COVID first emerged in late 2019. Workers at the market were amongst the first individuals to present with the pneumonia that was quickly linked to a novel coronavirus, and Chinese officials, fearing a repeat of the 2002 SARS epidemic that killed 774 people, were quick to close the market down.
But by the time Chinese researchers descended on the Huanan market in 2020 to collect genetic samples, they found no wildlife present at all. Although they were able to detect traces of the virus in samples taken from surfaces and sewers in the market, the lack of direct evidence of infection in market animals sparked a debate over whether this truly was the epicenter of the outbreak. Alternative theories centered around the Wuhan Institute of Virology.
In the face of this absence of evidence, researchers working on the new reports turned to alternative information sources.
Using data pulled from the Chinesesocial media app Weibo, they were able to map the location of 737 COVID-positive Wuhan residents who turned to the app to seek health advice during the first three months of the outbreak.
Plotting the geographic concentrations of cases through time, the researchers clearly identified the market as the centre of origin, with the virus spreading radially through surrounding suburbs and across the city as time progressed. Through statistical analysis, the researchers demonstrated that the chances of such a pattern arising through mere chance was exceedingly unlikely.
However, the pattern alone was open to interpretation, with questions remaining about pathways of introduction to the market–was the virus carried in inside a caged animal, on the coat of an unwitting scientist, or via some as-yet unidentified vector?
To dig further into the mystery, the researchers looked at the genetic samples obtained from market surfaces in January 2020 by Chinese scientists, tracing the locations of individual positive samples to their exact location within the market complex.
This second map revealed a strong concentration of positive samples in one corner of the market, a sector that had been previously documented to house a range of wild mammals that are considered potential coronavirus hosts.
Finally, the researchers created an evolutionary family tree of the earliest coronavirus lineages that emerged in the first few panicked weeks of the pandemic.
Even in its very earliest stages SARS-CoV-2 was a variable beast, with evidence of two distinct lineages, dubbed A and B. Looking closely at the mutations that separate the two, the researchers found something surprising–rather than one descending from the other, it appears that they had separate origins and entries into the human population, with lineage B making the leap in late November and lineage A following suit shortly afterwards.
Initial studies of the Huanan market genetic samples found only lineage B, but this latest investigation detected the presence of lineage A in people who lived in close proximity to the market–a finding corroborated by a recent Chinese study that identified lineage A on a single glove collected from the market during the initial shutdown.
Questions remain about the identity of the intermediary animal host species. But by narrowing research focus to the most likely centre of origin, this research will significantly aid efforts to understand the process that saw COVID-19 enter the world, and hopefully help avert future pandemics.
Fake Viral Footage Is Spreading alongside the Real Horror in Ukraine—Here Are 5 Ways to Spot It
Manipulated or Falsified Videos and Images Can Spread Quickly—but There Are Strategies You Can Take to Evaluate Them.
By TJ Thompson, Daniel Angus and Paul Dootson
Amid the alarming images of Russia’s invasion of Ukraine over the past few days, millions of people have also seen misleading, manipulated or false information about the conflict on social media platforms such as Facebook, Twitter, TikTok and Telegram.
One example is this video of military jets posted to TikTok, which is historical footage but captioned as live video of the situation in Ukraine.
Visuals, because of their persuasive potential and attention-grabbing nature, are an especially potent choice for those seeking to mislead. Where creating, editing or sharing inauthentic visual content isn’t satire or art, it is usually politically or economically motivated.
Disinformation campaigns aim to distract, confuse, manipulate and sow division, discord, and uncertainty in the community. This is a common strategy for highly polarized nations where socioeconomic inequalities, disenfranchisement and propaganda are prevalent.
How is this fake content created and spread, what’s being done to debunk it, and how can you ensure you don’t fall for it yourself?
What Are the Most Common Fakery Techniques?
Using an existing photo or video and claiming it came from a different time or place is one of the most common forms of misinformation in this context. This requires no special software or technical skills—just a willingness to upload an old video of a missile attack or other arresting image, and describe it as new footage.
Another low-tech option is to stage or pose actions or events and present them as reality. This was the case with destroyed vehicles that Russia claimed were bombed by Ukraine.
Using a particular lens or vantage point can also change how the scene looks and can be used to deceive. A tight shot of people, for example, can make it hard to gauge how many were in a crowd, compared with an aerial shot.
Taking things further still, Photoshop or equivalent software can be used to add or remove people or objects from a scene, or to crop elements out from a photograph. An example of object addition is the below photograph, which purports to show construction machinery outside a kindergarten in eastern Ukraine. The satirical text accompanying the image jokes about the “calibre of the construction machinery”—the author suggesting that reports of damage to buildings from military ordinance are exaggerated or untrue.
Close inspection reveals this image was digitally altered to include the machinery. This tweet could be seen as an attempt to downplay the extent of damage resulting from a Russian-backed missile attack, and in a wider context to create confusion and doubt as to veracity of other images emerging from the conflict zone.
Journalists and fact-checkers are also working to verify content and raise awareness of known fakes. Large, well-resourced news outlets such as the BBC are also calling out misinformation.
Social media platforms have added new labels to identify state-run media organisations or provide more background information about sources or people in your networks who have also shared a particular story.
They have also tweaked their algorithms to change what content is amplified and have hired staff to spot and flag misleading content. Platforms are also doing some work behind the scenes to detect and publicly share information on state-linked information operations.
What Can I Do about It?
You can attempt to fact-check images for yourself rather than taking them at face value. An article we wrote late last year for the Australian Associated Press explains the fact-checking process at each stage: image creation, editing and distribution.
Here are five simple steps you can take:
Examine the metadata
This Telegram post claims Polish-speaking saboteurs attacked a sewage facility in an attempt to place a tank of chlorine for a “false flag” attack.
But the video’s metadata—the details about how and when the video was created—show it was filmed days before the alleged date of the incident.
To check metadata for yourself, you can download the file and use software such as Adobe Photoshop or Bridge to examine it. Online metadata viewers also exist that allow you to check by using the image’s web link.
One hurdle to this approach is that social media platforms such as Facebook and Twitter often strip the metadata from photos and videos when they are uploaded to their sites. In these cases, you can try requesting the original file or consulting fact-checking websites to see whether they have already verified or debunked the footage in question.
If old content has been recycled and repurposed, you may be able to find the same footage used elsewhere. You can use Google Images or TinEye to “reverse image search” a picture and see where else it appears online.
But be aware that simple edits such as reversing the left-right orientation of an image can fool search engines and make them think the flipped image is new.
Look for inconsistencies
Does the purported time of day match the direction of light you would expect at that time, for example? Do watches or clocks visible in the image correspond to the alleged timeline claimed?
You can also compare other data points, such as politicians’ schedules or verified sightings, Google Earth vision or Google Maps imagery, to try and triangulate claims and see whether the details are consistent.
Ask yourself some simple questions
Do you know where, when and why the photo or video was made? Do you know who made it, and whether what you’re looking at is the original version?
Using online tools such as InVID or Forensically can potentially help answer some of these questions. Or you might like to refer to this list of 20 questions you can use to “interrogate” social media footage with the right level of healthy skepticism.
Ultimately, if you’re in doubt, don’t share or repeat claims that haven’t been published by a reputable source such as an international news organization. And consider using some of these principles when deciding which sources to trust.
By doing this, you can help limit the influence of misinformation, and help clarify the true situation in Ukraine.