CCG’s President says there will be no diplomatic masterstroke in Ukraine’s absence, but serious consideration of a ceasefire can lay the groundwork for peace
Putin was receptive, warmly welcoming the idea of a China-hosted meeting. Trump, too, has expressed a willingness to meet Xi and Putin. These expressions of openness offer an opportunity we must seize in pursuit of peace.
Some in the United States and Europe question the value of such a summit. They may fear restoring Putin’s standing or normalising the conflict without yielding any real progress towards an end to the war. That risk is still real but these largely Western fears must be tempered by the very real, very human cost of letting the war continue unabated.
In August last year, I extended that train of logic in Foreign Policy, where I proposed a seven-party format for peace negotiations and suggested that a peacekeeping force include troops from European and BRICS countries. A meeting of the three leaders in Shenzhen could help lay the groundwork for these broader diplomatic and peacekeeping efforts.
Without Ukraine’s participation, such a meeting is unlikely to produce a diplomatic masterstroke that ends the war. But the three leaders need not put the war to rest at a table in Shenzhen to make progress. Serious consideration of a ceasefire along the current line of contact—an approach Ukrainian PresidentVolodymyr Zelenskyy has supported—could give peace efforts fresh momentum, leaving the final status of disputed territories for subsequent negotiations.
Further agreement could be sought on the protection of nuclear facilities, or a mutual end to strikes on energy infrastructure, new prisoner exchanges or improved humanitarian access. Of course, issues of sovereignty, security guarantees, Russia’s security concerns and Europe’s security commitments would remain. But these need not all be resolved at once before a ceasefire can begin.
Already, years of war have inflicted immense suffering on both Russia and Ukraine. Neither side achieved its objectives, and both need a dignified way out that protects their core interests. Thus, we must open a path towards peace without requiring either side to concede defeat. China could help bridge this gap by bringing Xi, Trump and Putin together in Shenzhen to explore how a ceasefire and wider negotiations involving Ukraine might work.
The United Nations could stand at the core of such an arrangement by monitoring any ceasefire and preventing a return to fighting by physical peacekeeping if the parties are so inclined.
For a broader negotiation on settlement, I find myself returning to a seven-party format that would bring together the five permanent members of the UN Security Council—China, France, Russia, Britain and the U.S.—alongside Ukraine and the European Union. An understanding reached in Shenzhen could give momentum to this broader negotiating process and free up the Security Council for action.
A peacekeeping force composed entirely of NATO or European troops might be unacceptable to Russia. Yet a mission without European participation would struggle to reassure Ukraine and its neighbours. Any workable arrangement would need to address both concerns.
In my Foreign Policy article, I proposed a peacekeeping force drawing troops from five European countries—Germany, France, Britain, Poland and Italy—and five members of the BRICS grouping, such as China, India and Brazil. And while the exact formulation, from the composition and mandate to the terms of deployment, would need to be negotiated with the consent of Russia and Ukraine, and the agreement of the contributing countries, the core idea remains sound.
As a permanent member of the UN Security Council and the largest contributor of peacekeeping personnel among the five permanent members, China is well positioned to help. Its distinctive role in the global economy and dialogue with Russia, Ukraine, the U.S. and Europe, give it channels through which to coax the parties towards peace. But this process must begin somewhere, and that somewhere could be Shenzhen.
Nor should APEC be the end of the diplomatic effort. With an understanding reached by the leaders in Shenzhen, the Security Council may pick up the momentum by advancing ceasefire and peacekeeping proposals. The Group of 20 could then join the effort to rally support from major economies with an interest in maintaining the deal. Each would play a different role and would not be tasked with settling the entire conflict.
China’s role in the Saudi Arabia-Iran rapprochement in 2023 showed Beijing’s ability to open a door after years of enmity. The Ukraine war is different, and there can be no guarantee of a similar outcome. But diplomacy must begin somewhere, particularly when fighting has brought such destruction.
The central question is whether such a meeting could help bring the war to an end. In that light, any gain in prestige for an individual leader is almost irrelevant. And if the three leaders could agree on practical steps towards peace, they would give the United Nations and the wider international community a material basis upon which peace could be built.
[from APEC News, by María Gloria Riethmüller Harland, Singapore]
Every day, I pass by small businesses that bring life to our neighborhoods. A corner café with its own blend, a family bakery known for its special recipe, a local designer selling clothes under her own brand. Few of them would think of themselves as intellectual property owners, yet in many ways they are.
Over the last two years of chairing the APECIntellectual Property Rights Experts’ Group (IPEG), one conviction has only grown stronger. Intellectual property should not be a privilege for a few. It should be the foundation that lets anyone with a good idea earn from its expression and grow. It should spark more creativity across our region. It should help build new businesses, new jobs and shared prosperity.
In practice, for a small business owner, the system can feel complex, costly and hard to navigate. The landscape is also changing quickly, as new technologies and online trade reshape how ideas are made, shared and protected.
When IPEG was created in 1997, its focus was making global trade rules on intellectual property work between economies. Over time, its work has grown to place small businesses, along with women, young innovators and local communities, at the center.
Our work over the past two years has been about making that shift real.
Small businesses, big ideas
Micro, small and medium enterprises (MSMEs) account for more than 97 percent of businesses in the APEC region. The challenge is not whether they have valuable ideas, they do. The challenge is turning those ideas into growth.
Some of the most valuable lessons came from simply listening. Last year August in Incheon, I moderated our Policy Dialogue on Intellectual Property for Business, with a focus on SMEs. Our conversations were honest and practical, from making the system more user-friendly for small business owners to the opportunities e-commerce opens for them.
Conversations matter, but only if they lead to change. This one did. Following the dialogue, the World Intellectual Property Organization (WIPO) offered member economies the opportunity to embark on a project, asking small businesses directly how they understand, use and perceive intellectual property, and what stands in their way. Such projects aim to help offices and policymakers across the region build systems and support around real needs, not assumptions.
When we met in Dalian this August, the progress was clear. Some economies shared how they are running training workshops that help firms, especially technologystartups, identify and actively manage their intellectual property strategically. Others are offering support in valuing patents, so small businesses can use their inventions to secure loans.
Technology is changing how ideas come to a reality and are sold. But it is also changing how we protect those inventions, giving intellectual property offices new tools to work faster, smarter while making systems simpler for business owners.
Artificial intelligence search tools can now help compare applications more thoroughly rather than simple keyword matches. Chatbots walk first-time applicants through the search process. New translation tools make it simpler to understand patents filed across the region.
For a small business, this is far from a technical detail. Faster and more accurate searches mean knowing early whether an idea is genuinely new, before spending money on an application and investing in their venture.
Used well, technology can turn a complex process into a quicker, clearer path to protection.
Every idea counts
But a system is only as strong as the people it reaches.
Women, for example, accounted for just 18 percent [archived PDF] of inventors named in international patent applications in 2024. For the people and communities behind unprotected good inventions, that means missed income, missed recognition and missed growth.
Every region also has its own valuable cultural or geographical assets, while communities also carry traditions passed down over generations, from recipes and crafts to songs and stories. They are not just part of communities’ heritage and pride. For many, these traditions and assets can become sources of income. Intellectual property plays a vital role here too.
Geographical indications, labels that tie a product’s name to its place of origin, are one way to do that. Across the region, they are helping more small local businesses and women-led enterprises stand out from imitations, reach new buyers and become more competitive.
Copyright is reaching folk art too, from traditional stories to music and designs. Clear rights give communities the confidence to share their traditions widely and give new generations a reason to keep creating with them.
Inclusion is not a side project for intellectual property. It is the test of whether the system works at all. When intellectual property reaches more people, more creations reach the world, benefiting workers, MSMEs, communities and consumers. That simple belief has guided IPEG’s work for the past two years.
In August, I chaired my final IPEG meeting in Dalian. What I value most is not any single outcome, but the spirit behind our work.
That space matters more than ever. New technologies, new business models and new forms of creativity are creating both opportunities and challenges. I encourage IPEG to keep using this forum not only to exchange information, but to thinking creatively about where APEC cooperation can make more tangible differences.
Because in the end, the measure of our work is simple. It is whether the corner café, the family bakery and the young designer down the street can turn their innovations into a lasting livelihood.
María Gloria Riethmüller is the Chair of the APECIntellectual Property Rights Experts’ Group (IPEG) and Legal Advisor at the Intellectual Property Department of Chile’s Undersecretariat of International Economic Affairs.
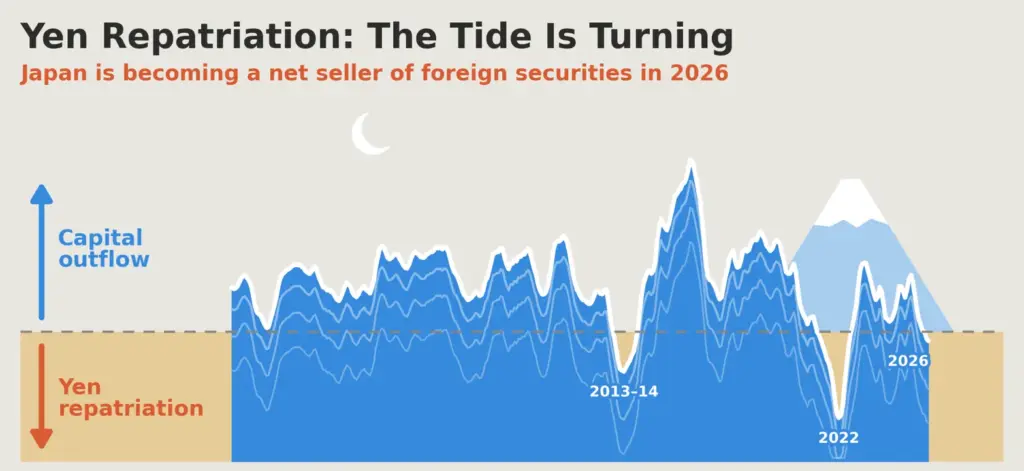
From 2014 to 2025, Japan bought foreign securities worth about 2% of GDP a year. In 2026 the tide is turning. Banks are selling foreign bonds and capital flow has turned to a small net inflow.
[by OKUBO Takuji]
Key takeaways
Japan has been an exporter of capital since the 1980s, purchasing 2–3% of GDP worth of foreign assets every year, interrupted by episodes of yen repatriation from time to time. 2026–27 may be turning into such an episode.
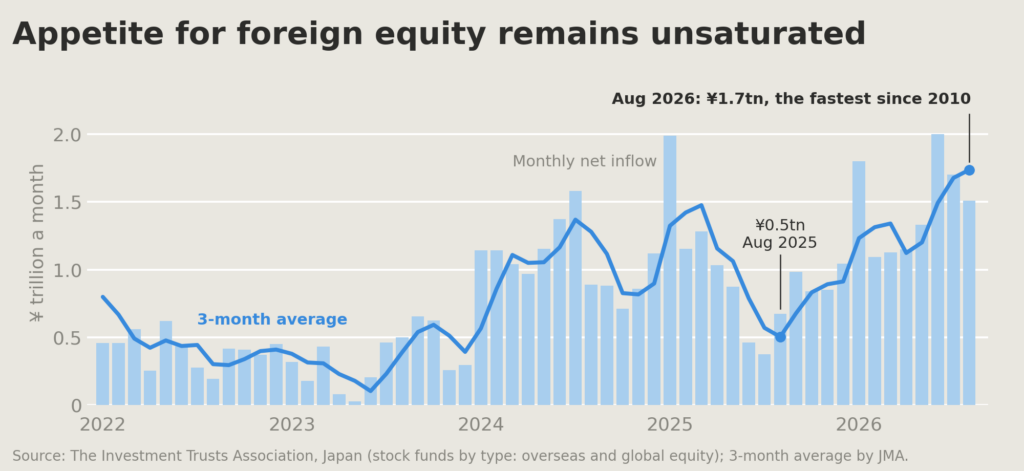
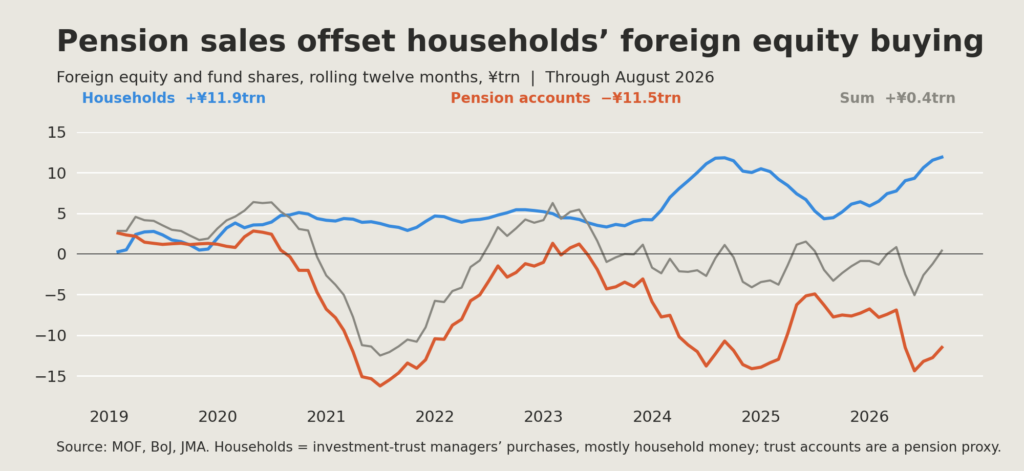
Households keep buying foreign stocks, but pension funds are selling against them, offsetting the net purchase of foreign equities.
Pension funds are likely to put more money into yen. On my replication of GPIF’s allocation rule, its domestic-bond weight should be much higher than today’s 25%, and foreign bonds are the likely asset class to give way.
The weekly survey to 10 October shows foreign-bond selling continuing. In my view, yen repatriation in 2026–27 is a question of how large, not whether.
Japan’s outward flow has turned into a net sale
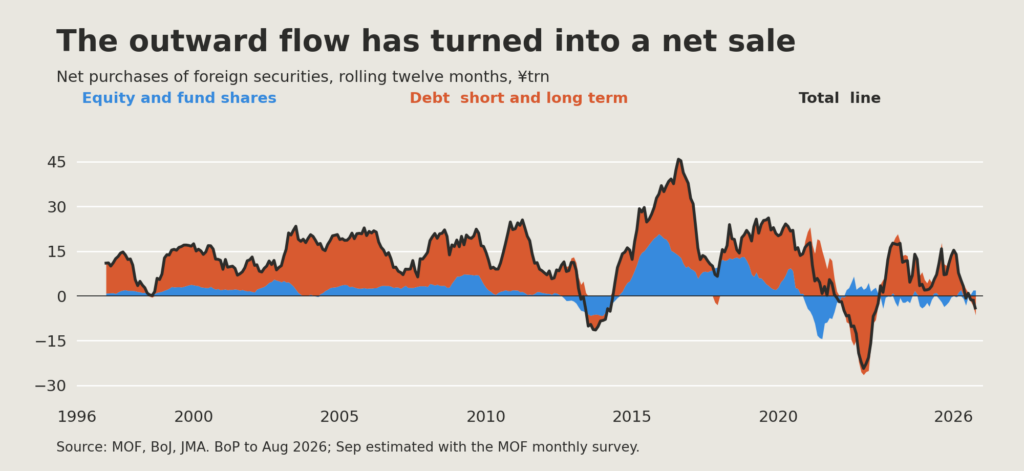
Japan has been a large provider of capital to the rest of the world since the 1980s. The latest wave began in 2014. From 2014 to 2025, residents bought ¥13.6trn a year on average, about 2.3% of GDP.
Chart 1 shows the flow as a rolling twelve-month sum. The one large exception was 2022, when bond yields rose sharply abroad and Japaneseinvestors sold their holdings, realizing losses on their foreign bonds. They went right back into purchasing foreign securities in 2023 when yield curves in major foreign bondmarkets stabilized, while domestic bond yields remained close to zero. How Japaneseinvestors behave now that yen yields are respectable is the big question.
Chart 1: Rolling twelve-month flows, stacked separately above and below zero. Short- and long-term debt combined; black line is the net total. BoP through August 2026; September estimated from the MOF monthly survey. Source: MOF, BoJ, JMA.
The flow is turning again in 2026. By August 2026 the rolling total was a small net sale of ¥1.5trn (see chart 1 above). September’s balance of paymentsstatistics are not out yet, but based on the International Transactions in Securities Survey for September, I estimate that the rolling total would be a net sale of ¥4.5trn. September itself was a small net sale; most of the drop comes from September 2025’s ¥2.8trn of buying leaving the window.
Foreign bonds and foreign equity have different investors
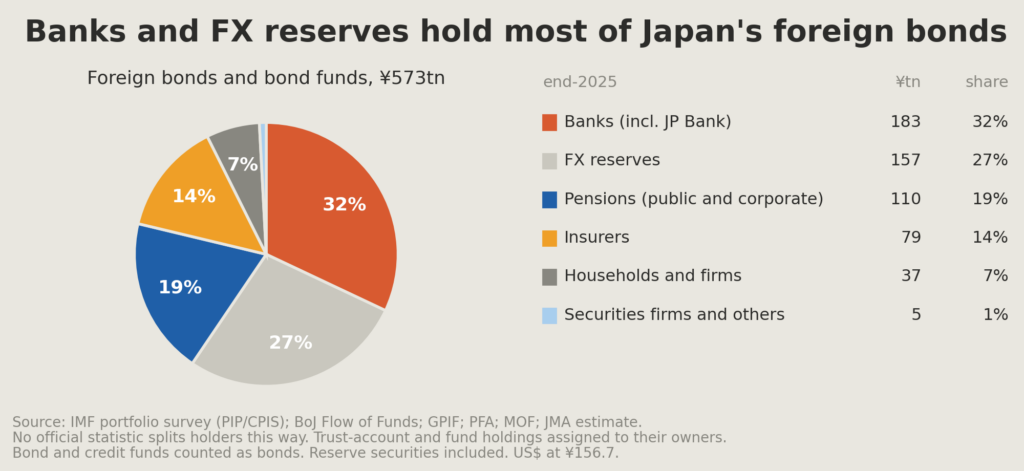
In the rest of the report, I discuss recent developments in Japan’s capital flows. I have organized the discussion by asset class because the investor bases differ. Banks, the FX reserves managed by the government, pensions and insurers hold foreign bonds. In foreign equity, households are now the key investors, alongside pensions and other traditional investors. GPIF and other pensions sit in both markets, so I discuss them in a part of their own.
Japan holds 147% of GDP worth of securities abroad
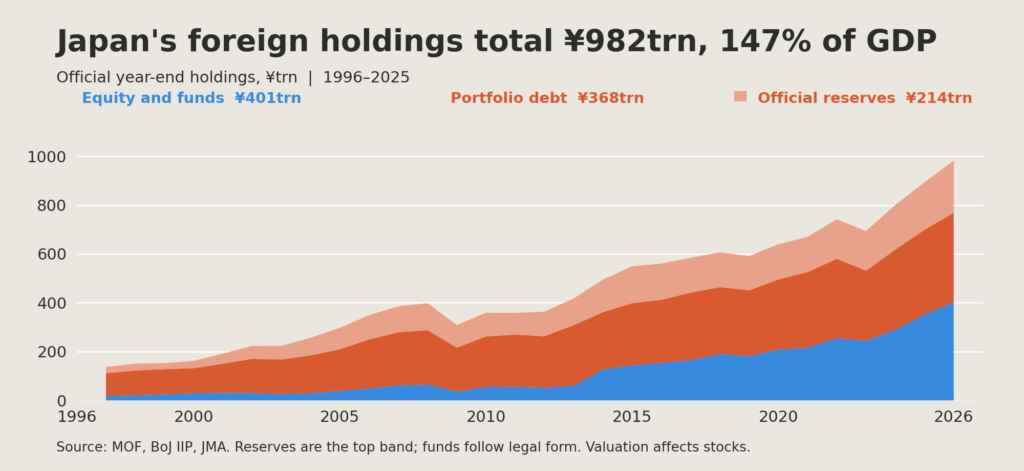
Before moving to discuss recent developments, let me give you a brief historical perspective on Japan’s outward investment. Japan has been a creditor nation since the 1980s. In 1985–89, Japan invested 3–5% of GDP, as Japan was awash with bubblemoney. Since then, Japan has typically invested 2–3% of GDP a year in foreign securities, with some episodes of repatriation from time to time. At end-2025, Japan held ¥982trn in foreign portfolio securities and official reserve assets: ¥401trn of equity and fund shares, ¥368trn of portfolio debt and ¥214trn of reserves (chart 2). Reserves are mostly US Treasuries plus some deposits and gold. The ¥401trn in equity and fund shares actually includes some bond funds that are categorized inside “equity and fund shares” in official statistics, so we will make some adjustments when we discuss investor behavior by asset class in later parts.
Chart 2: Official year-end holdings, 1996–2025. Equity is the bottom band, portfolio debt the middle band and official reserves the top band. Debt and reserves use related colors. Current BPM6-rearranged IIP; funds classified by legal form. Source: MOF, BoJ, JMA.
Part 1. Selling foreign bonds in 2026
Banks, reserves, pensions and insurers own the bonds
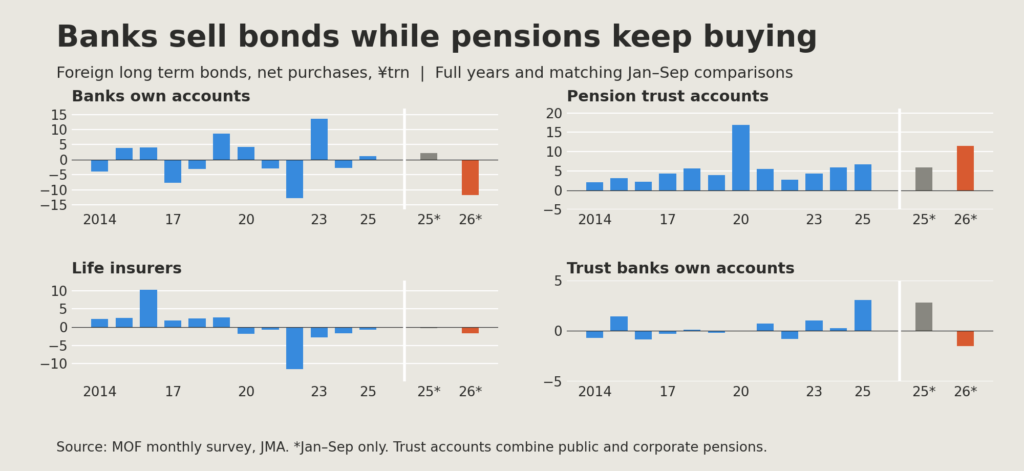
Chart 4 shows movements in foreign long-term bond flows by investors since 2014. We see pension funds as the consistent buyer, with an elevated purchase in 2020 when GPIF raised its foreign-bondasset allocation target from 15% to 25% (see the Japanese Macro Advisors GPIF report for details). On the other hand, life insurers have been consistent net sellers in recent years. Banks seem to be opportunistic swing players. This year’s foreign-bond sale so far is a bank story.
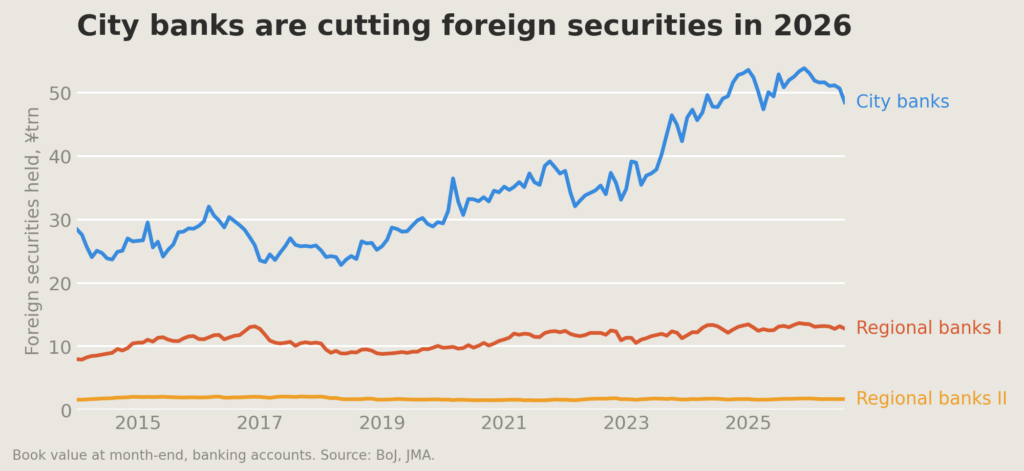
The bankbalance sheets show who is selling. City banks are the dominant players: their foreign securities reached about ¥53trn in late 2024, moved sideways with some swings in 2025, and then fell in 2026. Regional banks’ foreign holdings are small and little changed (chart 5).
2026 is different from 2022: Yen rates are at 30-year highs
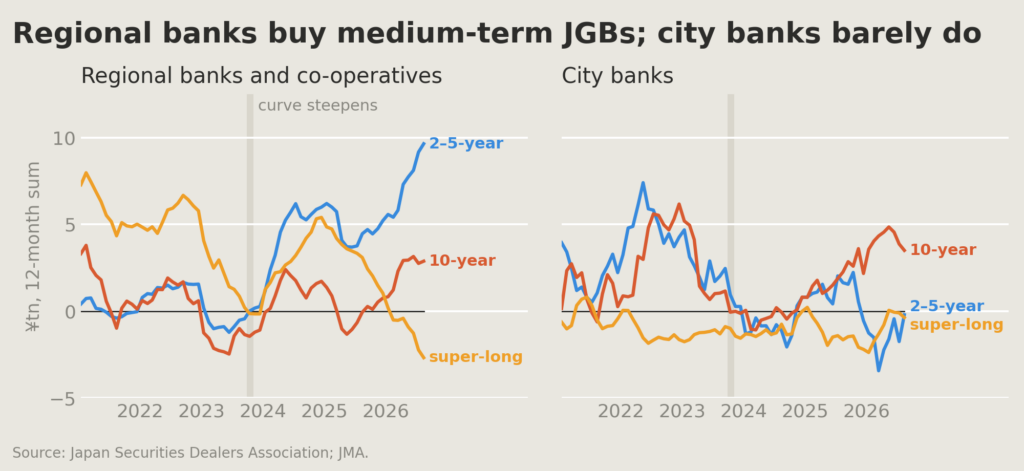
City banks went through a similar repatriation episode in 2022 (see chart 5), but went right back to buying foreign bonds in 2023 as soon as the overseas yield curve stabilized. 2026 offers a different environment. Both city banks and regional banks are buying JGBs, although in different parts of the yield curve. City banks are stepping up their purchases of 10-year bonds on a rolling 12-month basis (chart 6). They were selling the 2–5-year and super-long sectors in early 2026, but their rolling 12-month figures have just come back to neutral. Regional and co-operative institutions are showing strong appetite for the 2–5-year and 10-year sectors. Banks buying at home does not necessarily mean selling bonds abroad, but their JGB purchases do leave less room for duration risk in foreign bonds.
Chart 6: Net secondary-marketOTC purchases, twelve months through August. Regional/co-operative group includes regional banks, shinkin and agricultural institutions; auctions and bills excluded. Source: JSDA, JMA.
Part 2. Pension funds are selling foreign equity, offsetting households’ buying
Why do pensions sell what households buy? Pension funds typically manage their assets to target weights. When foreign equities outperform, they sell some and buy other assets to restore the balance.
Part 3. Pension funds to put more money in yen
GPIF likely to raise its asset allocation into yen bonds
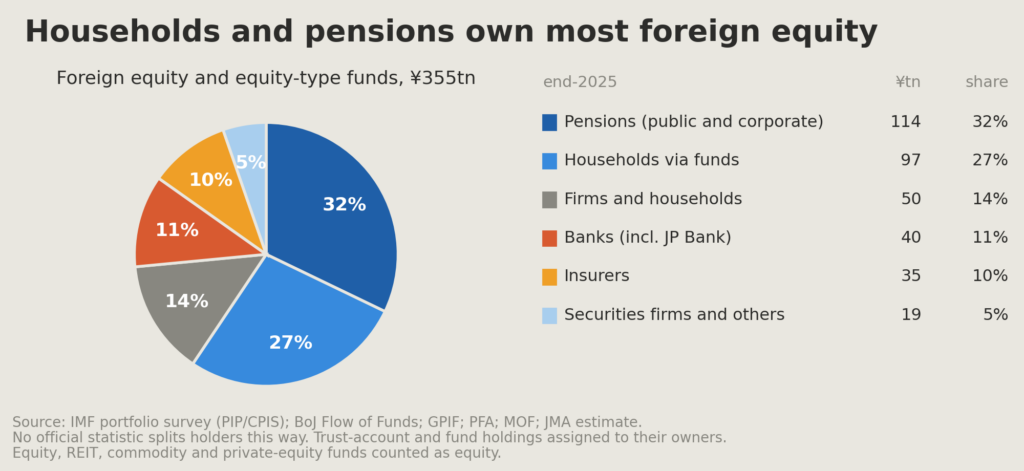
As you can see in the two pie charts (charts 3 and 7), GPIF and other pension funds are key players in Japan’s investments in foreign bonds and equity. GPIF, with ¥320trn of assets under management, is the big whale, and changes in its asset allocation have played a significant role in defining Japan’s cross-border capital flows in recent years.
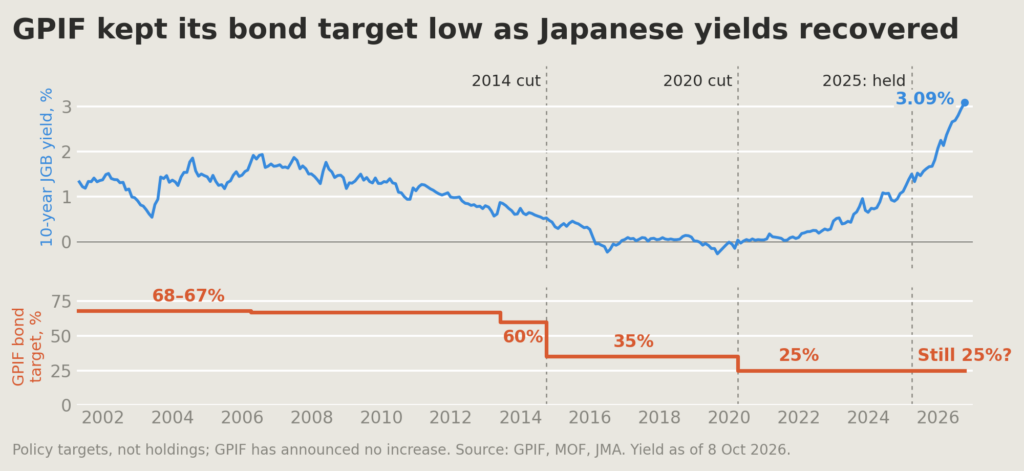
For details on my views on GPIF, I refer readers to the “GPIF the Whale” report. Here is the gist. GPIF reduced its domestic-bond allocation target from 60% to 35% in 2014 and to 25% in 2020, partly to protect the fund from a JGB crash it saw coming (chart 10). The crash has already happened, in slow motion over the last two years. When GPIF last reviewed the asset allocation in early 2025, maintaining the target unchanged at 25% made sense. At the time, JGB yields had more room to “normalize”, and they did. Please see my report The Long Climb in JGB Yields Is Nearly Over (20 July) for why I think the normalization is largely over.
On my simplified replication of GPIF’s allocation rule, a zero expected real return on JGBs points to a domestic-bond weight of about 50%, against 25% today. A move to 50% means about ¥80trn of assets shifting toward yenbonds, and foreign bonds are the likely asset class to give way. For more details, please see Yen Repatriation Starts with the Whale (10 September). It is a tricky shift, as GPIF is a classic whale in financial jargon, and there is a legitimate concern that other investors could front-run it. But GPIF cannot ignore the asset-allocation arithmetic. GPIF’s July–September results, due in early November, are the first place a shift could show, but even if it doesn’t, it is just a matter of time in my view, as GPIF would be doing Japanesepensioners a disservice if it did not change the allocation.
Chart 10: GPIF policy targets for domestic bonds and 10-year JGB yield, through 8 October 2026. Source: GPIF, MOF, JMA.
Part 4. Recent development and what to watch
Weekly data shows bond selling continuing into October
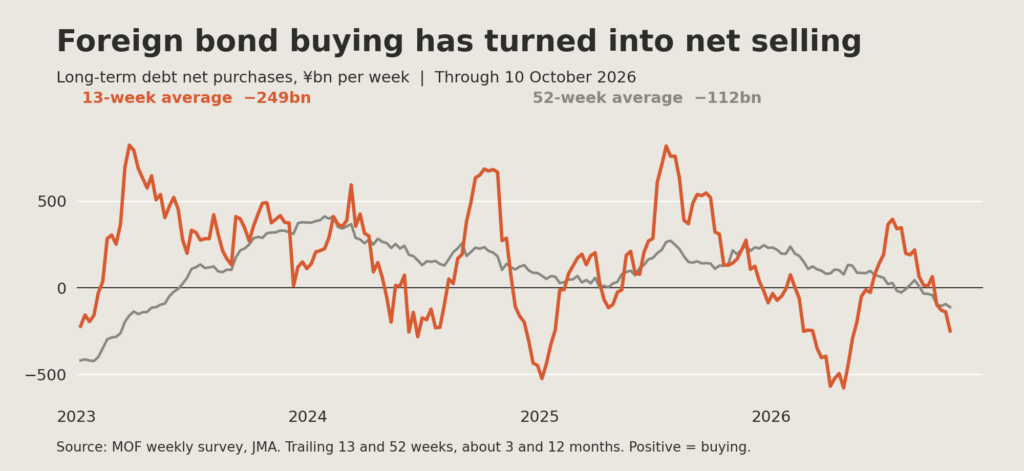
The balance of payments is the key statistic for monitoring cross-border capital flows, but as of mid-October it runs only to August. The Ministry of Finance’s weekly survey of large investors is a good leading indicator and runs to 10 October. In the four weeks to 10 October, Japaneseinvestors sold a net ¥3.3trn of foreign long-term bonds. Chart 11 shows the 52-week and 13-week averages.
Chart 11: MOF weekly survey of designated major investors. 13- and 52-week trailing averages, approximately three and twelve months, through 10 October. Both lines show average net purchases per week, not cumulative totals. Source: MOF, JMA.
Equity flows have no sustained direction
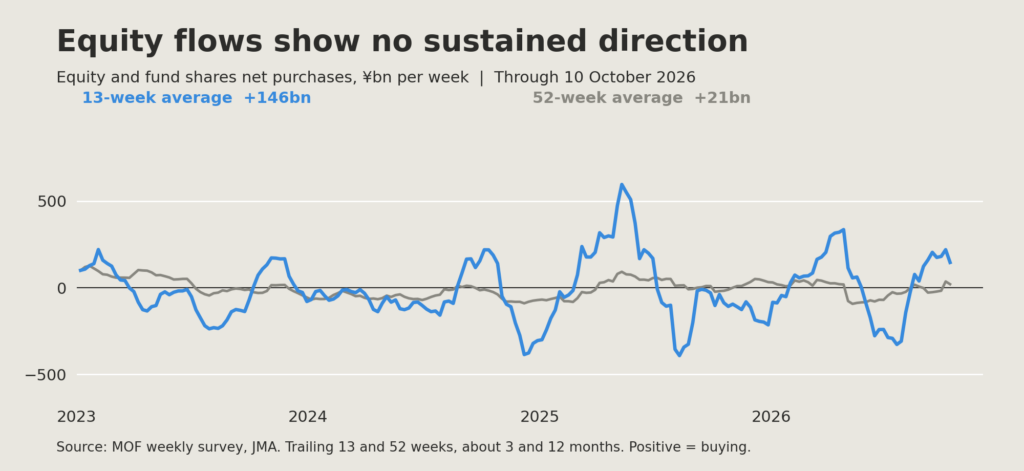
The same weekly survey includes equity flows. They have some ups and downs, but the 52-week average is hugging the zero line, and I do not see any particular trend upward or downward (chart 12). The equity data add no repatriation signal to the bond evidence.
Chart 12: Same weekly survey, smoothing windows, dates and vertical scale as Chart 11; foreign equity and fund shares. The 13-week line shows recent swings; the 52-week line shows the smaller underlying net flow. Source: MOF, JMA.
What to watch
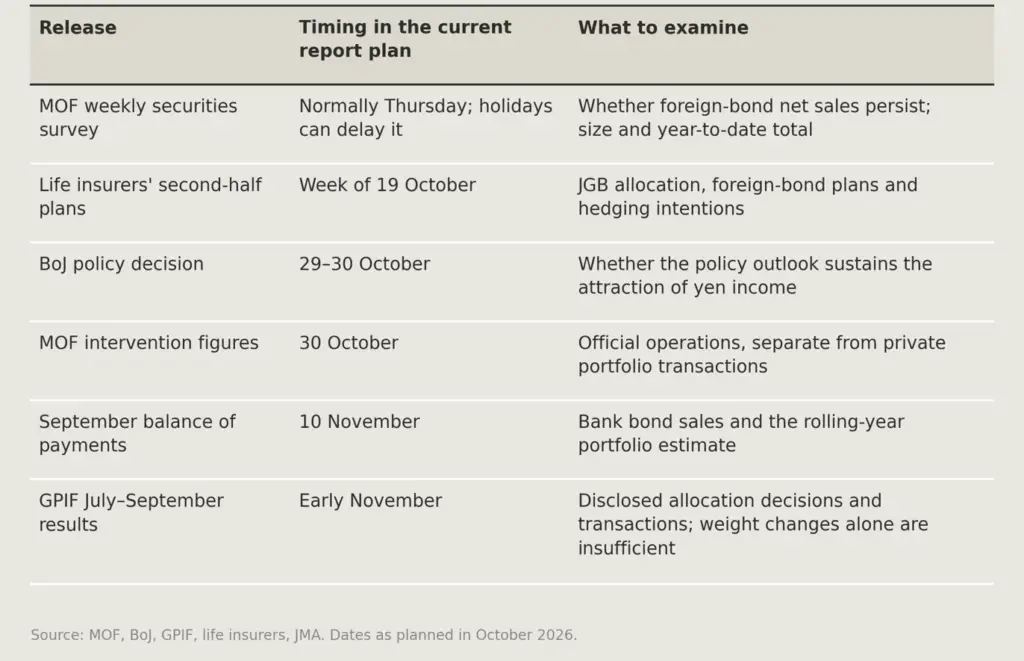
The weekly survey is the first test of whether bond sales persist. The September balance of payments, due in early November, will test the estimate in the opening. The other releases are in the table below.
Conclusion
The capital-flow tide is turning
As this report showed, Japan has been a broadly consistent provider of capital to the rest of the world, and Japan will continue to play that role for many years to come. However, the tide turns from time to time, and 2026 seems to be such a year. Net portfolio flow has narrowed from a sizable outflow in 2024–25 to a small net sale in the latest months, even while households continued to show strong appetite for foreign equity. Banks seem to be increasing their appetite for yenbonds, with good reason. JGB yields have risen to a 30-year high. Some may claim the rise has to do with higher fiscal premia, but my yield-curve analysis in Japan’s Fiscal Vigilantes Are Misreading the Curve (16 July) shows otherwise.
In my view, this shift weakens one of the forces behind the weak yen. Higher yen yields give investors a reason to keep shifting toward domestic bonds. I see a moderate chance that the turn in foreign bonds develops into a larger net repatriation, with GPIF’s asset allocation decision as a potential key mover. If global financial markets were to suffer a setback, whether in the euro bondmarket or the USstock market, it would further strengthen the case for yen repatriation. In my view, Japan’s capital flows are likely to show yen repatriation in 2026–27; the question is how large, rather than whether it will happen.
In the plains of Assam, different kinds of rain are often distinguished through vivid local expressions that reflect their intensity and impact on everyday life. One such term is “sagoli-kheda-borokhun” (the rain that chases goats). It refers to a light shower, enough to send goats hurrying into their sheds while people continue with their daily activities. As the rainfall intensifies, it may be described as “goru-kheda-borokhun” (cow-chasing rain), followed by “manuh-kheda-borokhun” (people-chasing rain), when even humans seek shelter from the downpour. At the extreme end of this scale of vernacular expressions of rainfall intensity lies “gor-kheda-borokhun” (the rain that chases away rhinos), evoking a deluge so intense that even Assam’s iconic one-horned rhinoceroses would retreat and look for shelter. With rapid urbanization and changing rainfall patterns, such beautiful expressions of rain have lost continuous usage, especially among the younger generation, who no longer name types of rains.
These expressions reveal the richly textured ways in which communities inhabiting the water-abundant landscapes of Northeast India have understood and interpreted rainfall. Their environmental imagination is shaped not only by the rains themselves but also by the sounds, movements, and rhythms of the ecosystems around them. Among the most evocative signs of the approaching monsoon was the chorus of frogs inhabiting the “pukhuris” (ponds), “khaals” (natural drainage channels), and “beels” (wetlands). Their persistent croaking, described locally as the rhythmic “tur-tu-rai” of an assembled army of frogs, would fill the night air. Hearing this familiar symphony, people would often remark that the rains were on their way.
In today’s times, such soundscapes have diminished considerably and the traditional knowledge of being able to predict rains by observing sounds and signs in nature have not been passed on. The familiar chorus of frogs on humid nights has grown noticeably quieter as ponds have deteriorated, wetlands have been drained, and traditional water bodies have gradually disappeared from the landscape. Here, I look at the languages and imaginations of communities, and how these interact with the annual rains and storms along the Eastern Himalayas, how they keep record of the changes in the climate patterns in their community lives through their vernacular depictions of storms and rains, and how the current climate crisis has clouded their traditional communication methods.
Water-Abundant Worlds
The Himalayan river-systems and the plains they nourish have always been regarded as a water-abundant environment, with monsoons, storms and rains forming an essential part of the lives and imaginations of communities living there. Nation-state borders, which straddle river-systems and regions across the Himalayas, bring in an additional layer of complexity to the various discourses of climate change disasters and patterns in the region, which are already exacerbated by infrastructural interventions on the river systems.
The languages and imaginations of Himalayan communities through which they describe the monsoons, climate change, storms, and rainfall patterns in their daily lives and natural environment, and how they are shaped by the interventions and narratives deployed by the nation-state in the Eastern Himalayas serve as critical crisis communication, often proving more useful and timely than governmentcommunication. The monsoon rains that stream in from the Indian Oceancurrents and extend up to the heights of the easternmost fringes of the Himalayas bring most of the Himalayan river-systems to life. The monsoon clouds, after they enter Northeast India, play a veritable ping-pong between the low-lying rolling hills of the Patkai ranges and the towering eastern Himalayan mountain ranges, and the rains and storms that ensue from this match nourish the various communities, sustain the forests, and shape the landscape. This interaction forms an archive of climate disasters in the region.
Modern meteorological forecasting methods have greatly improved with scientific progress and modelling and availability of long-term data. However, from my research, it has been evident that the medium-range and long-range predictions of storms and rainfall patterns have low reliability at the local level, meaning state-led communication methods are not effective or timely. There are externalities of data collection challenges and reliability of what actually constitutes long-term data and the rapid infrastructure push and anthropogenic changes in the context of the fragile and ever-crumbling-and-forming Eastern Himalayas.
Bordoisila is the personified name given to an annual spring storm that ravages the foothills of the Eastern Himalayas, often spanning across Assam, Meghalaya, Arunachal Pradesh, Nagaland, and Bhutan. The community memory of Bordoisila is archived over time through stories of the storm returning to “her maternal home,” Assam, to celebrate Bohag Bihu, the mid-April spring festival, and accounting for the ferocity and devastation it regularly brings along, as well as the variation in timing of the storm’s arrival and when “she returns” after celebrating. Communities provide token offerings of festive food and clothing to Bordoisila, imploring the storm to pass by gently in “her path.” The variation in timing and ferocity of the storm is recorded in recent community memory as the personified storm managing to come home early this year as “she got to leave early from her workplace.” Originating in the Chotanagpur plateau and gathering force from the Bay of Bengal, she again returns in an angry mood as if “she was not treated well by her mother” with festive goodies and good food.
Personified Storms
Over years of research in the region, I have noted that communities rarely rely on modern meteorological forecasting information for the stormy season. They know it only by community memory and their sense of the ferocity of the storm when it passes by—among a series of spring storms—and declare that “she has finally arrived” and “she will soon return after celebrating Bihu.” It is along the trail of Bordoisila that the first wave of floods also arrives in Assam, and the traditional knowledge repository known as “Dakor Boson,” a collection of vernacularprose and poetrysayings, depicting how the coming monsoon and the ensuing agricultural cropping cycle will span out. The first floods were always celebrated with the Bihu dance, and the storm Bordoisila is revered despite its ferocity, as it brings the rain and nutrient-rich silt to nourish the overall landscape. However, with climate change and anthropogenic interventions, the language of climate crises has changed from a sense of celebration and reverence to utter despair.
Over the past several decades, Northeast India has witnessed profound shifts in its monsoon patterns. Periods of unusually intense rainfall have triggered devastating floods, while prolonged dry spells have brought drought-like conditions to many areas. In response to persistent droughts, communities across Assam have continued to observe customs such as frog-marriage ceremonies, invoking these creatures regarded as messengers of the rain-gods, to restore the rains through their renewed croaking. In Meghalaya, rainfall that used to last nine nights and days in a continuous rhythmic pattern, known as “slap-khyndai-miet-khyndai-sngi,” has, over recent years, lost its original community language emphasis, as such long-enduring rainfall patterns have diminished greatly.
Among the Idu-Mishmi of eastern Arunachal Pradesh, traditional ritual specialists are called upon to communicate with rain spirits, seeking their intervention both when the rains fail to arrive and when incessant downpours raise fears of catastrophic flooding. The Idu-Mishmi term for rain, “ayyo or ayyoyo,” carries deep cultural significance within these practices. Jibi Pulu, an Idu-Mishmi community leader and environmental activist, points to how different kinds of rainfall were once understood to perform distinct ecological functions in the forests of the Dibang Valley. Certain rains signaled the shedding of leaves, others supported flowering cycles, while some heralded the arrival of migratory birds that seasonally visited the region’s rich forest ecosystems. However, he observed that such patterns have become increasingly difficult to anticipate, as deforestation, climate change, and human intervention have disrupted environmental rhythms that earlier generations could interpret with a high confidence.
Many Idu-Mishmi elders similarly attribute the growing unpredictability of rainfall and the increasing occurrence of extreme floods on the Dibang River and its tributaries to a deterioration in the relationship between people and the natural world. They regard practices such as the indiscriminate slaughter of animals and the growing trend of winter picnics on dry riverbeds (where meals are prepared directly on the exposed riverbed) as acts that offend river spirits. In their understanding, these transgressions disturb the balance between humans and the spiritual forces inhabiting the landscape, contributing to erratic weather patterns and destructive flooding events. Some historic flooding events are referred to by communities with names of where such flooding originated, such as the “China-paani” of the year 2000 and the recent episodes of “Bhutan-baanpaani” along the Bhutan–Assam border. This vocabulary has expanded to include specific dam-induced floods such as Ranganadi-floods in Assam.
Culturally Grounded Approaches
The diverse linguistic expressions, traditional knowledge systems, and lived experiences through which indigenous communities across Northeast India understand rainfall, storms, climate variability, and recurring flood events deserve to be documented, connected, and amplified within broader conversations on environmental democracy and transboundary cooperation. Bringing these perspectives together can help foster more inclusive dialogues across the Eastern Himalayas and the Patkai mountain ranges, enabling local communities to participate meaningfully in decision-making processes concerning ecology, environmental governance, infrastructure development, disaster preparedness, crisis communication, and other issues that directly shape their everyday lives and livelihoods. For generations, communities have relied on close observation of their surroundings to interpret changes in weather and rainfall patterns, rhythms of rivers, and flood cycles.
As environmental transformations become more pronounced and traditional indicators grow increasingly uncertain, their ability to understand and articulate these changes offers valuable insights into the realities of climate change on the ground. Recognizing and engaging with such lived experiences, local knowledge, and environmental imaginations is, therefore, essential to strengthening civil society participation and building more democratic, responsive, and culturally grounded approaches to environmental governance in the region. Modern meteorological forecasting methods need to learn from traditional wisdom and social innovation and the vast archive of knowledge which have recorded past disasters and also can predict future ones. The rapid pace and scale of transformation along the Eastern Himalayas are rendering traditional knowledge systems incapable of providing climate solutions.
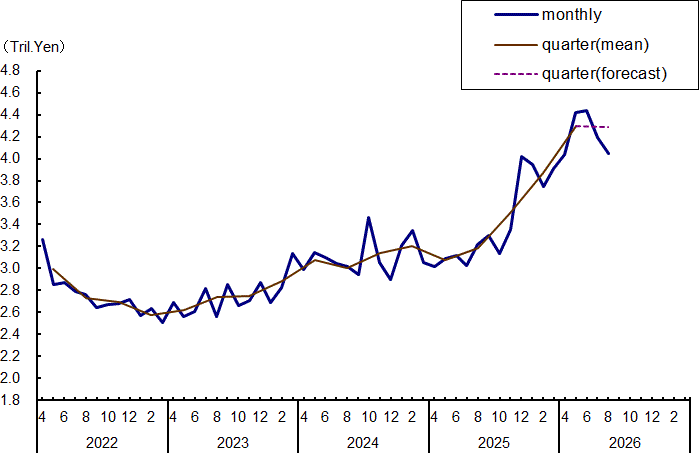
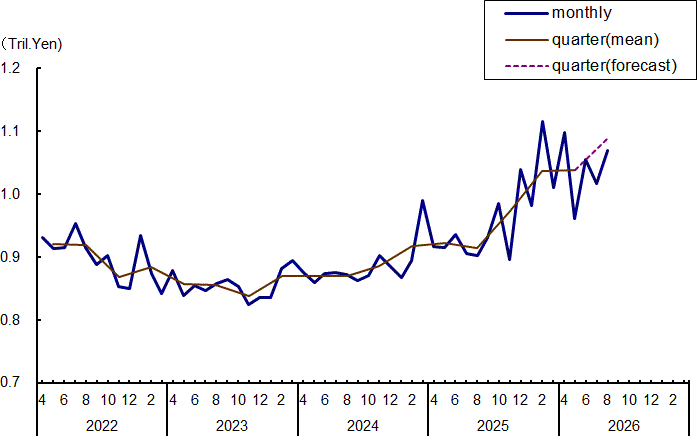
The total value of machinery orders received by 280 manufacturers operating in Japan decreased by 3.7% in August from the previous month on a seasonally adjusted basis.
Private-sector machinery orders, excluding volatile ones for ships and those from electric power companies, increased a seasonally adjusted by 5.2% in August.
Percentage change from previous quarter (month)
(%)
2025 Jul-Sep
Oct-Dec
2026 Jan-Mar
Apr-Jun
Jul-Sep (forecast)
2026 May
Jun
Jul
Aug
Total
3.5
10.2
10.3
11.3
-0.1
9.5
0.4
-5.5
-3.7
private sector
-1.3
6.2
2.6
14.6
-3.8
37.4
-26.0
1.5
-4.2
(exc. volatile orders)
-1.0
6.6
6.4
0.2
4.9
-12.4
9.7
-3.7
5.2
manufacturing
5.3
-0.8
10.0
-1.3
4.0
-14.9
19.9
-1.0
1.6
non-manufacturing (exc. volatile orders)
-4.4
11.3
6.2
-2.3
5.9
-9.3
4.5
-2.6
2.9
governments
-14.7
57.7
-21.3
-17.8
28.5
-5.0
10.5
-9.2
-6.1
from overseas
14.5
3.6
31.0
10.4
1.3
-4.4
19.9
-8.2
-7.7
through agencies
0.3
2.6
4.8
6.7
11.1
-5.8
7.2
1.3
-6.3
Note
Seasonally adjusted series. As all series are seasonally adjusted individually, a sum of seasonally adjusted individual/component series does not equal to seasonally adjusted totals.
Seasonally adjusted series. As all series are seasonally adjusted individually, a sum of seasonally adjusted individual/component series does not equal to seasonally adjusted totals.
Figures in () represent the percentage change from the previous quarter (month). Figures in [] are the percentage change from the corresponding quarter (month) of the previous year in original series.
Her potential-growth example implies a neutral rate around 2.8%, above the Bank’s published 2.5% ceiling and well above today’s 1.25% policy rate.
[by OKUBO Takuji]
Key Takeaways
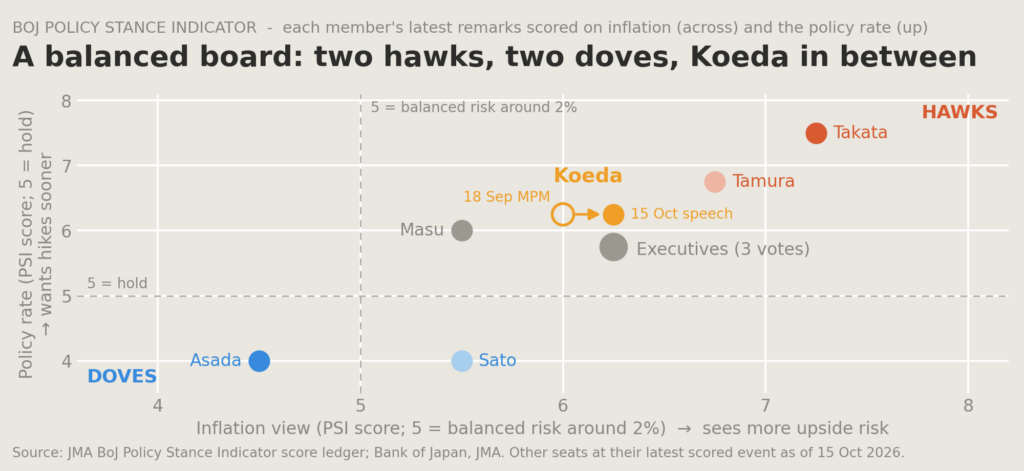
Koeda, probably the most influential swing vote on the board, seemed slightly more hawkish in her speech on October 15. She stopped just short of calling the 2% target achieved.
Her conceptual example of a neutral rate, potential growth plus 2%, points to a neutral rate well above 2%. While she is not in a hurry to push for hikes as the two hawks are, she seems open to a protracted hiking cycle.
I continue to think an October hike is out of the question. Koeda’s openness to a hike marginally raises the possibility of a December hike. I still consider it highly unlikely, though.
Why Koeda matters
On October 15, 2026, KOEDA Junko [小枝淳子] made her 3rd speech since she joined the BoJ policy board in 2025. She is an ex-IMF academic and yield curve specialist. She is probably the most important and influential swing vote in the current BoJ board. In her speech [archived PDF] and the following press conference (Japan Macro Advisors’ unofficial transcript), she sounded more open to continued rate increases than the three BoJ executives, although she was careful not to give any indication of the timing of the next move.
The board is balanced at both ends
As you can see in chart 1, the board is evenly balanced with two hawks at top-right and two doves at bottom-left (if you are unfamiliar with the BoJ-Policy Stance Indicator framework, please see the Japan Macro Advisors primer). That leaves KOEDA Junko [小枝 淳子] and MASU Kazuyuki [増 一行] between the two ends, sitting with the three BoJ executives: the Governor and two Deputy Governors. As BoJ executives tend to vote together, Koeda and Masu cast critical swing votes.
Chart 1
Koeda sounded more hawkish than before
In her speech [archived PDF] and the following press conference (see the Japan Macro Advisors unofficial transcript), she seemed slightly more hawkish than I anticipated. Koeda judges trend inflation to be already about 2% overall and increasingly well-anchored. She stopped just short of saying the 2% target has been achieved. She said:
“For about a year now I have described underlying inflation as roughly 2% on the whole, and I have kept checking how firmly it is taking hold. On the CPI, as I noted at Chart 11, broad-based price increases have continued for several years, and the distribution of year-on-year changes by item also suggests that this is becoming established. Wages, too, have shown stable increases overall. For these reasons, I think Japan’s inflation is becoming more persistently entrenched than before.” [Kumamoto speech, 15 October 2026, Japan Macro Advisors translation]
Koeda also offered a simplified concept of the neutral rate as the potential growth rate plus the 2% inflation target. As the Bank’s latest potential-growth estimate is about 0.8%, this could put the nominal neutral rate at 2.8%, exceeding the top of the Bank’s published nominal range of 1.1–2.5%. She did offer another version that put the neutral rate at a lower level, but it was clear that she wanted to give a higher version of a potential neutral rate.
To be clear, she did not endorse 2.8% as a policy-rate destination. At the press conference, she said the potential-growth rule does not always hold and declined to give a point estimate. But her intention was most likely to nudge the neutral rate range higher.
Koeda was clear in her message that she is open to a rate hike. She said: “I do not think we need to be overly cautious about raising rates.” [speech, Japan Macro Advisors translation]
But she was quite evasive regarding the timing of the next hike. In the press conference, reporters repeatedly asked for her view on a back-to-back rate hike, a veiled way of asking whether an October hike is possible. She was quite firm in repeating her stance that she does not have any particular pace in mind. This was an interesting contrast with Governor Ueda’s dismissive comment on the possibility of a successive or oversized rate hike (see the Japan Macro Advisors September 18 report). That does not mean she endorsed consecutive hikes. It means she left the option more open than Ueda did.
Conclusion: More open to multiple hikes
By choosing potential growth plus 2% as an example of the neutral rate, Koeda seems to be creating more space for the policy rate to eventually rise above 2%, in my view. In terms of the timing for the next hike, she was non-committal. I would still consider an October hike out of the question, but her non-committal attitude does marginally raise the possibility of a December hike, although I still consider it highly unlikely.
Prime MinisterTAKAICHI Sanae [高市 早苗] faced questioning in the House of Representatives budget committee Tuesday, with opposition and ruling party lawmakers questioning whether Agriculture MinisterYANA Kazuo [簗 和生] needs to quit or be dismissed as allegations of political misconduct mount. The prime minister was also pressed for more details on plans to finance the consumption tax cut. A new poll showed that the Yana scandal could be beginning to hurt the government’s support. [Update: On 14 October, 2026, Yana submitted his resignation to Takaichi, which was accepted.
Japanese lawmakers returned to the business on Tuesday, 13 October following a holiday weekend and resumed their questioning of Prime MinisterTAKAICHI Sanae in a meeting of the lower house’s budget committee. Asahi provided a timeline of the day’s deliberations here.
The calls for Takaichi to dismiss Agriculture MinisterYANA Kazuo [簗 和生] – in the event that he does not resign voluntarily – have continued to grow. The opposition parties have continued to threaten an upper housecensure motion if he does not leave, though they appear to be inclined to wait to see whether he or Takaichi will take the decisive step first (and they may also see some value in Yana staying around longer to give them additional opportunities to attack the government). A censure motion is also not guaranteed to pass the upper house since the opposition parties would need to bring along some of the upper house’s independents.
It is possible that, in response to reporting that Yana violated election law in providing free transportation to his supporters during campaigns, Takaichimay be backing away from her support for her embattled agriculture minister. Shesaid in the committee hearing Tuesday that if Yana had engaged in any illegal activities, she would not hesitate to remove him and suggested that she is seriously considering whether he can contribute to her government’s work, though she also said that she wanted to give him a little more time to account for his actions. Yana, for his part, denied that he had broken election law and also apologized again for the remarks about withholding road funds that started the scandal.
The Liberal Democratic Party (LDP) has not necessarily abandoned Yana, though senior party officials have continued to emphasize that he needs to do more to take responsibility for his actions and provide a full explanation of what happened. Former prime minister Ishiba Shigeru, however, has sharpened his criticism of both Yana and Takaichi, condemning his attitude as “highly questionable” for someone involved in politics. With Takaichiexpected to meet with Yana on Wednesday, 14 October following the budget committee hearing, his fate could be decided sooner rather than later. But the longer he remains, the greater the attention not just on his own conduct but on the LDP more broadly.
Takaichi questioned on tax cut funding
While the Yana scandal consumed significant oxygen Tuesday, the prime minister also faced questioning about the consumption tax cut bill that was submitted to the Diet last Friday.
Takaichi has encountered particularly insistent questioning on her government’s plans to fund the estimated JPY 5tn per year bill for the two-year tax cut on foodstuffs. She has repeatedly stated that the tax cut will not be funded by deficitbond issuance, but her government has avoided outlining plans for financing the tax cut until the FY2027 budget is drafted.
She alluded Tuesday to the possibility of using higher tax revenues or proceeds for currency intervention in the Foreign Exchange Fund Special Account (FEFSA) — both options that have been floated before — though it is unclear whether tapping the FEFSA for this purpose is strictly legal (or advisable).
Takaichi was also criticized for the government’s failure to provide details about how it intends to distribute additional payments to low-income households to compensate for the government’s decision to lower the tax to 1% instead of 0%.
The legislation’s path through the Diet is still uncertain as no opposition party has indicated its support. OKAMOTO Mitsunari [岡本 三成], leader of Kōmeitō, reiterated Tuesday that while his party is open to discussions with the government on the bill’s provisions related to the refundable tax credit to be introduced in 2029, it is still opposed to the temporary consumption tax cut and therefore cannot support the legislation.
First post-scandal poll suggests Yana could cost Takaichi
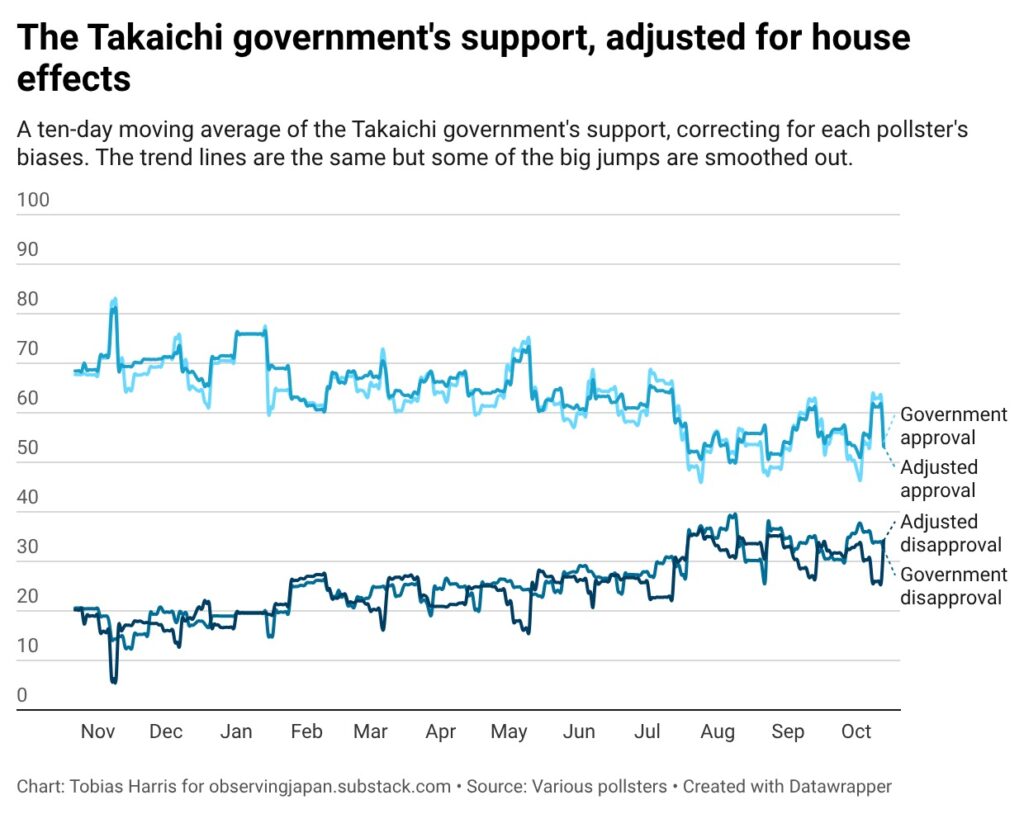
NHK released its latest poll on 13 October, which showed a slight decline in the government’s net approval – down three points, to +19 – and suggested that the Yana scandal could be beginning to weigh on the government’s support. The NHK poll is the first poll in nine days and the first since the scandal emerged. The entrance of the NHK poll into my ten-day moving average, which since 8 October had only included a fairly favorable JNN poll, brings the government’s weighted average support down to +21 (+19 adjusted for pollster bias).
The poll found that the public is relatively dissatisfied with the new cabinet lineup – 42% strongly (4) or somewhat (38%) in favor, 48% strongly (15%) or somewhat (33%) opposed – and overwhelmingly dissatisfied with Yana’s response to the allegations thus far. Only 8% said that they were persuaded by his comments, while 78% said that they were not.
Meanwhile, the poll also recorded one of the more negative findings about the consumption tax cut that I have seen, with only 38% in favor and 44% opposed.
While government supporters back the proposal by a 51% to 35% margin, independents oppose the tax cut by sizable margin, with 50% opposed and only 31% in favor. Support is polarized by age, with voters under 40 the most favorable (56% support); voters in their forties are slightly in favor (47% support to 44% oppose) and voters in their fifties are barely in favor (45% to 44%).
Voters over 60, who have the most to lose from cutting a tax that generates revenue earmarked for social security, are firmly opposed. Finally, 78% of respondents said that they are greatly (34%) or somewhat (44%) affected by rising prices.
In the first part of an interview with Tōyō Keizai, Economic Revitalization Minister KIUCHI Minoru [城内 実] explains that the Takaichi government’s goal has never been reflation but rather using fiscal measures to mobilize private investment as part of a strategy of enabling Japan to compete with other industrial powers.
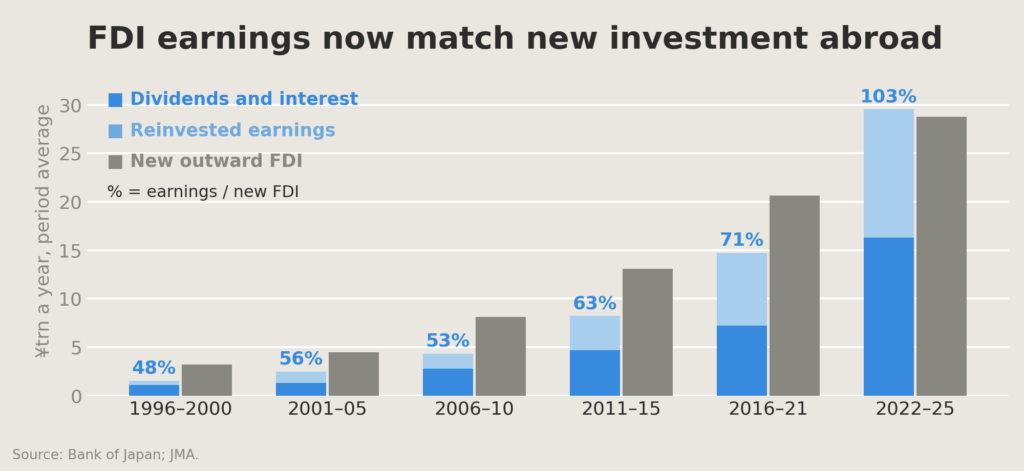
Earnings on Japan’s foreign direct investment (FDI) reached 103% of new FDI in 2022–25. With dividends and retained earnings counted together, Japan Inc. now needs to sell little yen to invest abroad.
[by OKUBO Takuji]
Key takeaways
Foreign affiliates now earn about as much as Japan invests abroad each year. Reinvested earnings, dividends and interest together reached 103% of new outward FDI in 2022–25, against 48% in 1996–2000.
Dividends from foreign affiliates account for a growing share of Japanese corporate profit. We estimate that foreign affiliates contributed 13.4% of Japan Inc.’s earnings in FY2025, up from 1.7% in FY1996.
Corporate investment abroad now involves little net yen selling. After dividends and interest paid home, the estimated outflow has been close to zero since 2022, down from about ¥5 trillion a year, or about 1% of GDP, on average in the 2010s.
Japan’s FDI stock now earns 103% of new investment
“Japan’s ageing and shrinking population depresses expected demand at home. Expected returns remain higher abroad, so Japanese companies have accelerated outward direct investment” (my translation). — MATSUBAYASHI Yōichi [松林 洋一], MOF PRI, chapter 8, p.136.
“Companies invested abroad because they saw no promising investments in Japan; they are unlikely to bring back every return. On a cash-flow basis, the external balance is in deficit and is one factor behind the weak yen” (my translation). — KARAKAMA Daisuke [唐鎌 大輔], MOF PRI, chapter 10, pp.178 and 175.
However, my review of recent data shows that while their premise of low growth prospects in Japan is probably still right, the direct investmentJapan has accumulated abroad has reached a level where it earns enough to cover Japan’s new investment abroad. This changes the exchange-rate implication even if Japan keeps investing abroad.
Overseas affiliates pay interest and dividends to their parent companies in Japan. Those dividends have become a sizable part of corporate Japan’s income: we estimate that they made up 13.4% of Japanese corporate profit in FY2025, up from 1.7% in FY1996.
When foreign affiliates retain their earnings on their balance sheets, Japan’s balance of payments statistics record them as FDI from Japan, even though no money crosses the border. While the companies receiving FDIdividends and the companies paying for new FDI are not necessarily the same, Japan Inc. as a whole is now financing its FDI almost entirely from the earnings of its overseas affiliates. At the current level of FDI, little new yen needs to be converted into foreign currencies as Japan goes about investing abroad.
A strong yen helped drive Japan’s first outward FDI boom
Japan’s outward investment was heavily restricted after WWII, requiring case-by-case permission from the government. Approvals became more and more automatic over the years until outward investment became “free in principle” in 1980. Trade friction with the US-led Japanese carmakers to restrain their exports from 1981, pushing them to build factories abroad. The rapid appreciation of the yen was also a factor. The yen strengthened from ¥242 per dollar before the Plaza Accord in September 1985 to ¥121 by the end of 1987. Japanese producers had to move lower value-added work abroad. The strong yen also gave Japanese financial institutions sizable purchasing power for a while, until the stock and property bubbles burst in 1990 and 1991.
All of these factors contributed to a rapid increase in outward FDI through the 1980s and 1990s (chart 2).
The next phase was sustained by a different pressure. With weak growth and low interest rates at home, Japan Inc. kept investing abroad, across a broader range of industries. Between 1995 and 2025, the stock of FDI rose from 9% of Japan’s GDP to 58% (chart 4). In 2025, it is as large as about 38% of the private sector’s domestic fixed capital, on our estimate.
Chart 4
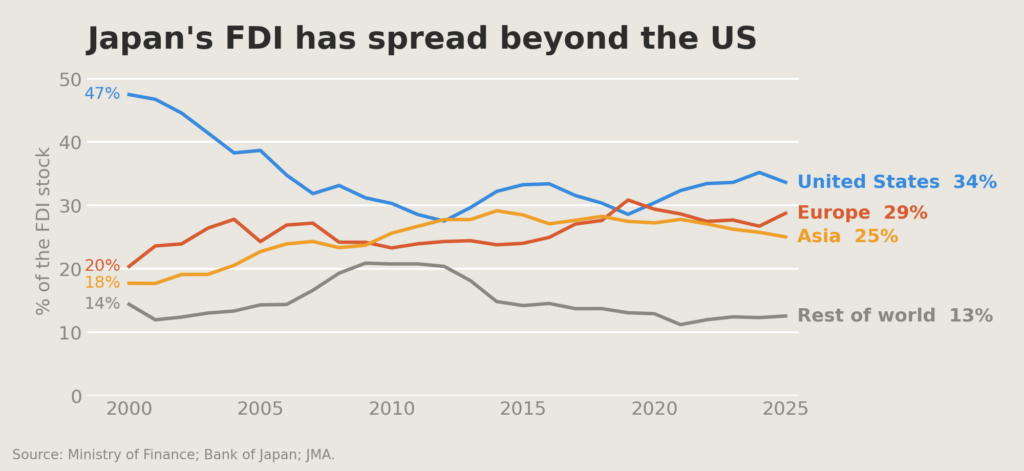
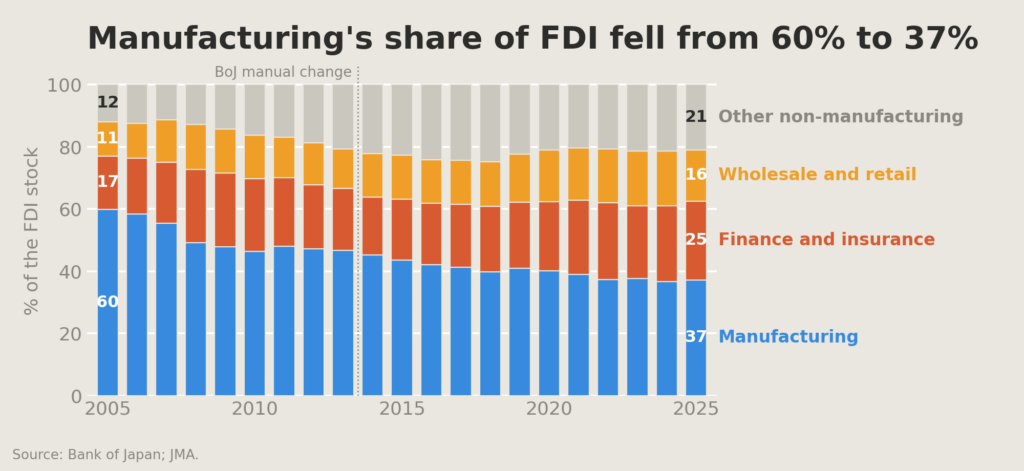
By industry composition and by destination compositions changed over time. Manufacturing’s share of the FDIstock had fallen to 37% by 2025, giving Japan’s FDI more breadth. By destination, we are seeing a revival of FDI toward the United States. It accounted for 34% of the stock in 2025, Europe 29% and Asia 25% (see earlier chart 3).
Thus, after decades of overseas investment, Japan’s FDI stock is now large enough that its earnings are sufficient to finance new investment abroad, at least for now. In the next section, I consider whether this will continue, and in particular whether Japanese companies may bring an even larger share of their overseas earnings back to Japan, given the weak yen, higher borrowing costs in yen and possibly better investment opportunities at home.
The weak yen has slowed offshoring, not reversed it
The real depreciation of the yen over the past 15 years made production in Japan more competitive. There is some evidence that manufacturers are considering bringing production back to Japan. The 2023 manufacturingwhite paper found more firms shifting production back from China than moving there, and they named the weak yen as one reason. We see some signs of reshoring. Japanese manufacturers’ overseas production ratio rose from 18.0% in FY2011 to 27.2% in FY2023, but it may have started to decline or at least stabilize. The ratio fell to 26.7% in FY2024. A Cabinet Office survey of listed manufacturers puts the ratio at 24.5% in FY2025, and their plan for FY2030 is broadly unchanged at 24.7%. The weak yen seems to have stabilized the wave of offshoring, but I see no firm evidence of a move back onshore yet.
Domestic investment has grown slowly despite the weak yen
There are tentative signs that domestic capital spending is starting to grow again. For three decades it grew at a very low speed. In real terms, private business investment rose only 26% between FY1997 and FY2025, less than 1% a year. In comparison, capital spending grew by about 4% a year on average in the United States. In my view, a weak currency is only one of the factors manufacturers weigh in designing their global production chains. The weak yen makes production in Japan competitive today, but they have also seen the exchange rate swing violently within short periods. Japan also has a shrinking population problem. It started to address it by opening a door to immigration, but the door is only tentatively open. Overall, my view is that the weak yen alone is unlikely to give Japan Inc. sufficient incentive to bring its capital back to Japan and to the yen.
Economic security is bringing some production home
The weak yen and non-economic geopolitical factors do point to a halt in Japan’s four-decade offshoring trend, although it is a stabilization, rather than an economy-wide reversal of past offshoring. Japan Inc. will continue to invest more abroad, rather than within its borders. Given the sizable growth in the stock of cumulative FDI, Japan Inc. no longer needs to convert yen into overseas currency to keep investing abroad though. Net of dividends and interest paid home, Japan’s FDI sold about ¥5 trillion of yen a year, or about 1% of GDP, on average in the 2010s; since 2022 the net flow has been close to zero. There is also an interesting development in an effort to allow more share-exchange based M&A for cross-border deals that will further reduce the need for Japanese companies to spend their yen to purchase overseas assets. In my view, Japan Inc.’s FDI is no longer a factor to drive the yen weaker.
GPIF, one of the largest national pension funds in the world, is likely to rebalance its assets from non-yen bonds to yen bonds, signaling a big turn in Japan’s cross-border capital flows.
[from Japan Macro Advisors, 10 September, 2026]
Key takeaways
In 2013, GPIF’s investment committee, chaired by UEDA Kazuo [植田和男], now the BoJ governor, saw a fair chance of a JGB crash within five to ten years. Its CEO priced the crash as the 10-year rising from 0.5% to 3%. Subsequently, GPIF cut its target weight for domestic bonds from 60% to 25% as an emergency measure against abnormally low yields.
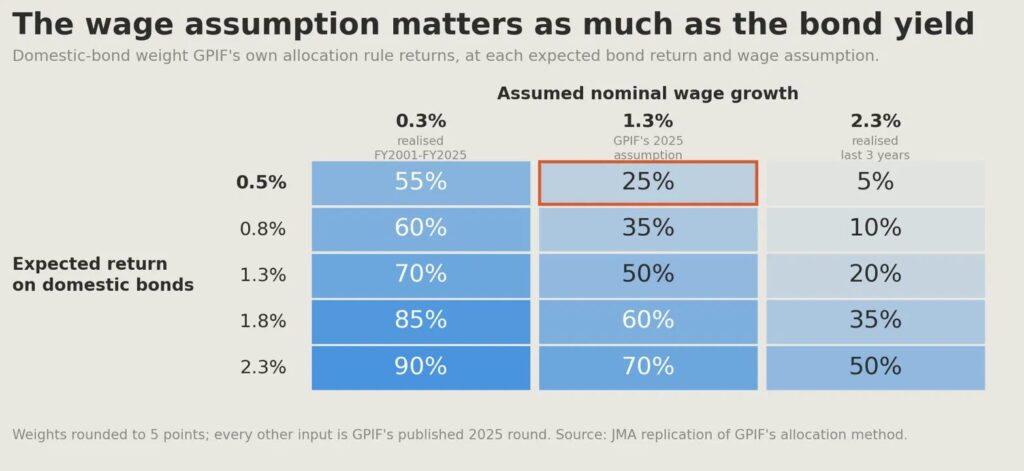
The 10-year is now at 3%. On my replication of GPIF’s own allocation rule, a real return on JGBs near zero points to a 50% weight in domestic bonds, against 25% today. I expect GPIF to raise the weight, if it has not already started in the September quarter.
How GPIF decides its asset allocation and communicates it publicly is a very delicate and political issue. But regardless of how it communicates it, a change in asset allocation is inevitable. In my view, it signifies a big turn in Japan’s cross-border capital flows.
Japan has one of the Largest Pension Funds in the World
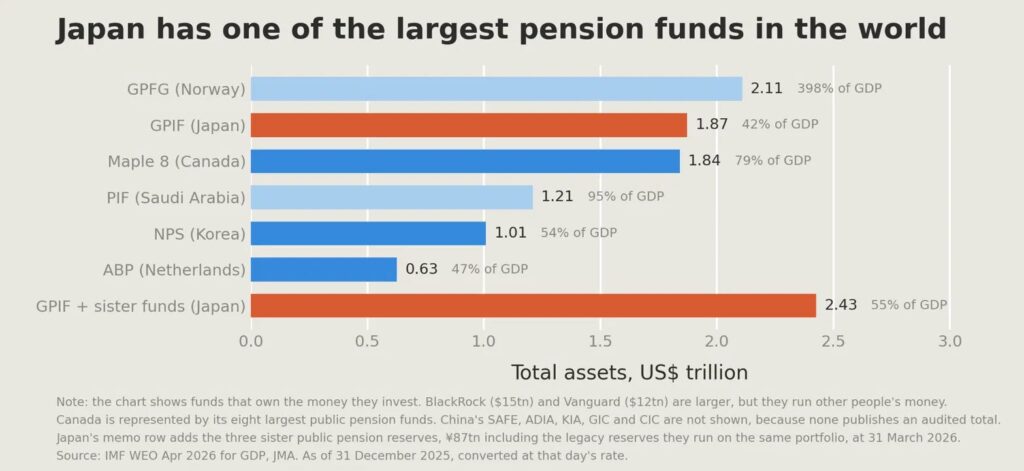
Japan has the second largest public pension fund in the world. Norway’s is the biggest, although it is not strictly a pension fund. Canada’s pension funds, when all eight of its variants are added together, come a close third.
Japan set up its first national pension fund in 1961 and it has since gone through various reforms and reorganization over the last 65 years. Its current form is called the Government Pension Investment Fund (GPIF). As explained in a later section, GPIF has a few siblings, and when we add them together, Japan’s public pension funds can be said to be the largest in the world.
Chart 1
GPIF used to invest most of its asset into JGBs
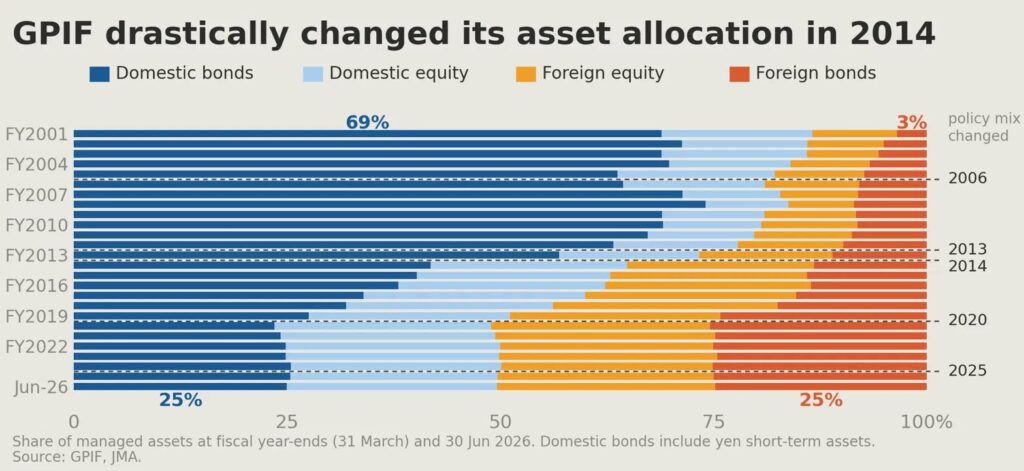
GPIF used to invest the majority of its fund as loans to the national government and into Japanese government bonds (JGBs). At the end of FY2012, 62% of its assets consisted of domestic bonds. However, in 2014 it went through a radical asset reallocation and the target weight for domestic bonds was reduced from 60% to 35%, and then further down to 25% in 2020. Its current target allocation is a clean four-way 25% split into domestic bonds, domestic equity, foreign equity and foreign bonds.
As one of the largest pension funds in the world, its asset allocations attract market attention and there is speculation that it is about to raise its allocation into domestic bonds. In my view, there is indeed a very high chance that GPIF will be raising its allocation into domestic bonds, if it has not already started to do so in the current quarter ending in September 2026.
Chart 2
UEDA in 2013 Saw a Bond Crash Coming
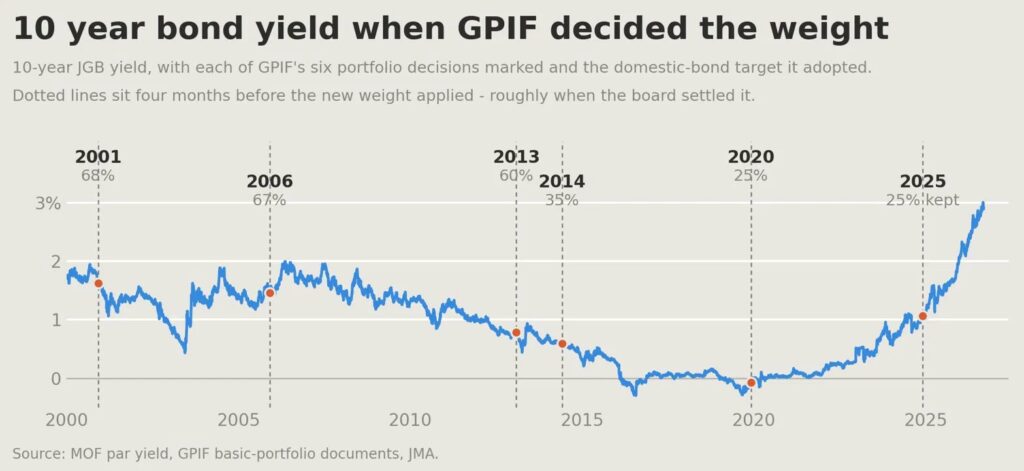
To understand why GPIF is highly likely to raise its allocation into domestic bonds, we need to go back in history to 2013. Why 2013? Of course, it is the year the Bank of Japan (BoJ) started its massive quantitative easing. The 10-year JGB yield started 2013 at 0.8% and it fell to 0.3% by the end of 2015 before briefly hitting a negative rate of -0.3% in 2016. If you were the chairperson of the GPIFinvestment committee, you would have been concerned about the wisdom of continuing to invest in JGBs at such a policy-driven low rate. The actual chairperson was UEDA Kazuo [植田和男], the current BoJ governor. In the minutes for October 2013, UEDA said, “I think there is a fair chance that bonds will crash at some point in the next five to ten years [unofficial translation].”
The minutes were released only seven years later; otherwise the use of the word “crash” would have been controversial.
GPIF CEO Priced the Crash at 3% in 2014. We Are There Now
If you read through the GPIF minutes between 2013 and 2014, you would see that GPIF officials were increasingly conscious of the precariousness of investing in JGBs. Long story short, as this process was highly political and a sensitive subject, they decided to radically lower the target allocation weight for JGBs to 35% in 2014, presented it as the result of a philosophical change in the way GPIF is managed and how the concept of “risk” should be considered. Investment in JGBs was no longer considered low risk in real terms. The asset allocation for domestic bonds was further lowered to 25% in 2020. The following is what MITANI Takahiro [三谷隆博], the GPIF CEO at the time and an ex-BoJ senior official, said in the October 2014 GPIF minutes.
“Yields are just under 0.5% now, so a move to near 3% would mean a loss of about ¥25 trillion. (…). So I think the clearest way to explain it is that reducing the weight on JGBs to some degree is simply unavoidable [unofficial translation]”
The 2014 cut in the weight was partly an emergency escape
As I wrote earlier, the radical asset reallocation in 2014 was part a shift in the concept of risk from “nominal” to “real”, so that JGB is no longer risk free assets. But the change was also at least partly an emergency measure to escape the abnormally low-yield environment. Then the next natural question is, now that the JGB yields are no longer abnormally low, what should happen to its asset allocation? Pensions are paid in yen, so long-duration Japanese government bonds are a natural match, while GPIF should also be holding some non-yenassets and equities to diversify its assets and protect the overall balance sheet from inflation. In the next section, I will show you a simplified replication of how GPIF decides its asset allocation and what GPIF’s asset allocation could be now that JGB yields are normal.
How GPIF decides its weights
Put simply, GPIF’s target weights are the output of an optimizer with a few rules. Find the portfolio that, at the required real return, has the smallest average shortfall below wage growth in the years when it falls short, and round it to the nearest 5%.
When GPIF last decided to keep the current 25% weight for domestic bonds in 2025, JGBs were assumed to produce a nominal return of 0.5% against wage growth of 1.3%, so a real return of minus 0.8%. Exhibit 1 shows a simplified matrix of weights depending on expected nominal return on bonds and wage growth. The red box shows the assumption behind the 2025 weights decision mentioned above. If we use a higher wage growth assumption of 2.3%, an expected nominal return of 1.8% on bonds gives a weight of 35%. GPIF’s bondportfolio has an average maturity around 10 years, and the 10-year bond is yielding 3% now. A lot of thought and estimation is needed to form a view on the expected real return on domestic bonds, but in my view, it is clear that the minus 0.8% used in their last review is too low given where bond yields are.
Why GPIF kept the weight in 2025 and why circumstances changed
In late 2024 when the GPIF was reviewing the weight as part of its five-year plan, the BoJ was already in the process of exiting from QE and raising its policy rate. However, the JGBmarket was still in the process of adjustment and bond yields had a lot of room to rise. For example, the 10-year yield was 0.89% at the end of September 2024, rose to 2% by the end of 2025 and now, in September 2026, stands at 3%. You can understand why GPIF decided to keep its weight on domestic bonds unchanged as it would have incurred capital losses on bond purchases in 2025. But in my view, as I wrote in the report “The Long Climb in JGB Yields Is Nearly Over” [archived PDF], long bond yields are getting closer to a stability point. If the GPIF board shares my view, it is a good time to think about raising its target weight into domestic yenbonds.
The Whale Problem and the Washington Problem
How high should the new weight be for domestic bonds? The reality of determining appropriate weights and how to announce it is a lot harder than the simplified model I explained above. Other than forming a reasonable view on the expected real return on asset classes, there are a few factors that complicate the process.
Firstly, GPIF needs to think about how such an announcement would affect the market. GPIF is what financial market professionals call a whale, a massive investor whose investment decisions sway market prices. There is also a related argument that given the dominance of GPIF in the domestic market, GPIF should be increasing its asset weight abroad to reduce its impact on domestic assetmarkets.
Secondly, changing asset allocation weights carries political considerations. If GPIF decides to raise the target weight for domestic bonds, foreign bonds are the likely asset class whose weight will go down. More than 50% of its foreign bonds are in US dollars. With all the news circulating in the market now, Scott Bessent will not like a public announcement that one of the largest pension funds in the world is reducing its purchase of US treasuries. There are domestic political considerations as well, as the Takaichi government contemplates how best to fund its deficits.
These are the issues GPIF officials must be debating. How GPIF decides its asset allocation in the near future will be a revealing case study for those who want to study how policy-making works in Japan. Those who are interested in this topic should read the transcripts of an interesting government committee in 2014 that focused on how GPIF could shield itself from political meddling. Guess who chaired the committee? UEDA Kazuo [植田和男].
Whatever the near-term decision GPIF makes regarding its target weight, I think it is fairly clear that GPIF should be increasing its investment into domestic bonds. The following table shows how much GPIF could buy in net terms, depending on the eventual rise in the target weight.
Additional domestic-bond holdings from re-weighting the fund at 30 June 2026 (managed assets ·317.8tn). Foreign bonds sold first. Source: GPIF, JMA.
Three things in this table matter for the market. GPIF is allowed to deviate its asset allocation by six points either side of 25% without any announcement, so 39% target is already possible without any public announcement. In 2014 GPIF moved inside its band first and announced the new portfolio afterwards, and I would expect the same sequence this time. Second, these are static figures, which do not account for the growth of the fund over time.
The sister funds move with the whale
As mentioned earlier, GPIF has a few siblings. The Pension Fund Association for Local Government Officials (¥35.5tn), the Federation of National Public Service Personnel Mutual Aid Associations, known as KKR (¥11.5tn), and the Promotion and Mutual Aid Corporation for Private Schools of Japan (¥4.9tn) manage the pension reserves of local government employees, national government employees and private-school teachers. These sisters run their funds on the same 25/25/25/25 model, and with the legacy reserves they also run, they hold a further ¥87tn on top of GPIF’s.
Conclusion
GPIF cut its domestic bond weight from 60% to 35% in 2014, and later to 25%, to safeguard its assets from the manipulated low JGB yields at the time and the eventual crash they foresaw. That crash, as GPIF’s CEO MITANI defined it in 2014, has now happened with the 10-year yield rising to 3%. In my view, JGB yields have largely normalized and there is no emergency reason to avoid domestic bonds. It is only natural that GPIF would raise its allocation into domestic bonds, although how GPIF communicates this publicly is a touchy issue they need to figure out. When GPIF raises its domestic bond allocation, foreign bonds are the likely asset class to take the hit. GPIF publishes quarterly results and the next publication for the end-September 2026 quarter, expected in early November 2026, will be closely watched. Judging from market movements in the last few weeks, the market has started to sense that what I described in this article is already happening and Japanese money is starting to come back to the yen. While it should be characterized as rebalancing, rather than a repatriation, it seems we are observing a big turn in Japanese cross-border capital flows.
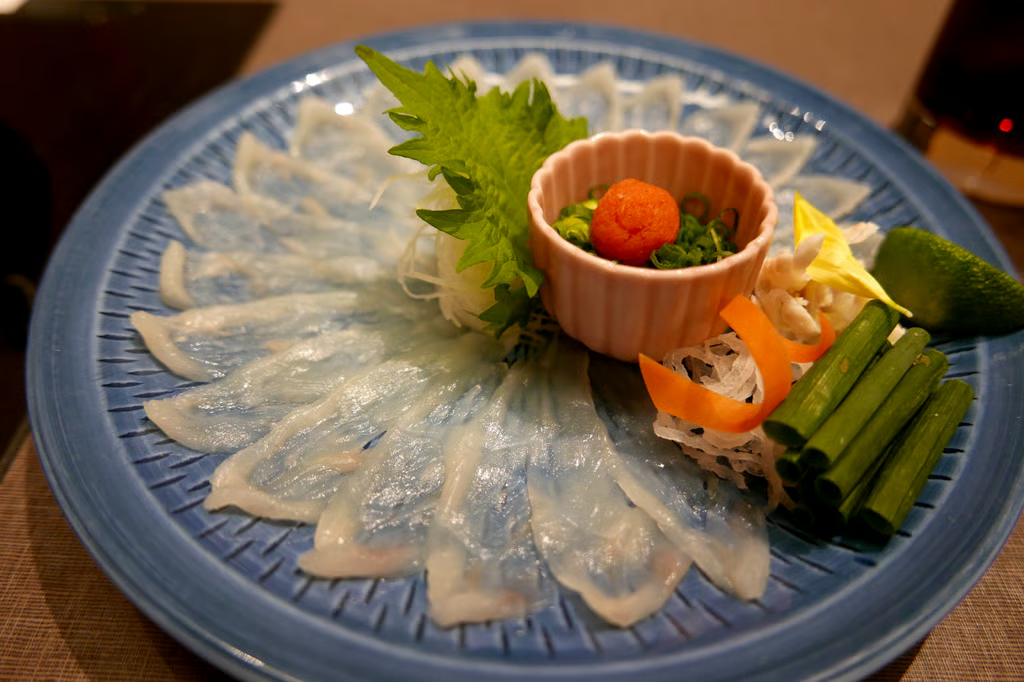
Japan’s most dangerous delicacy is getting harder to prepare safely as warming seas push different pufferfish species into the same waters, where they are inbreeding to produce hybrids whose lethal toxins are not yet fully understood.
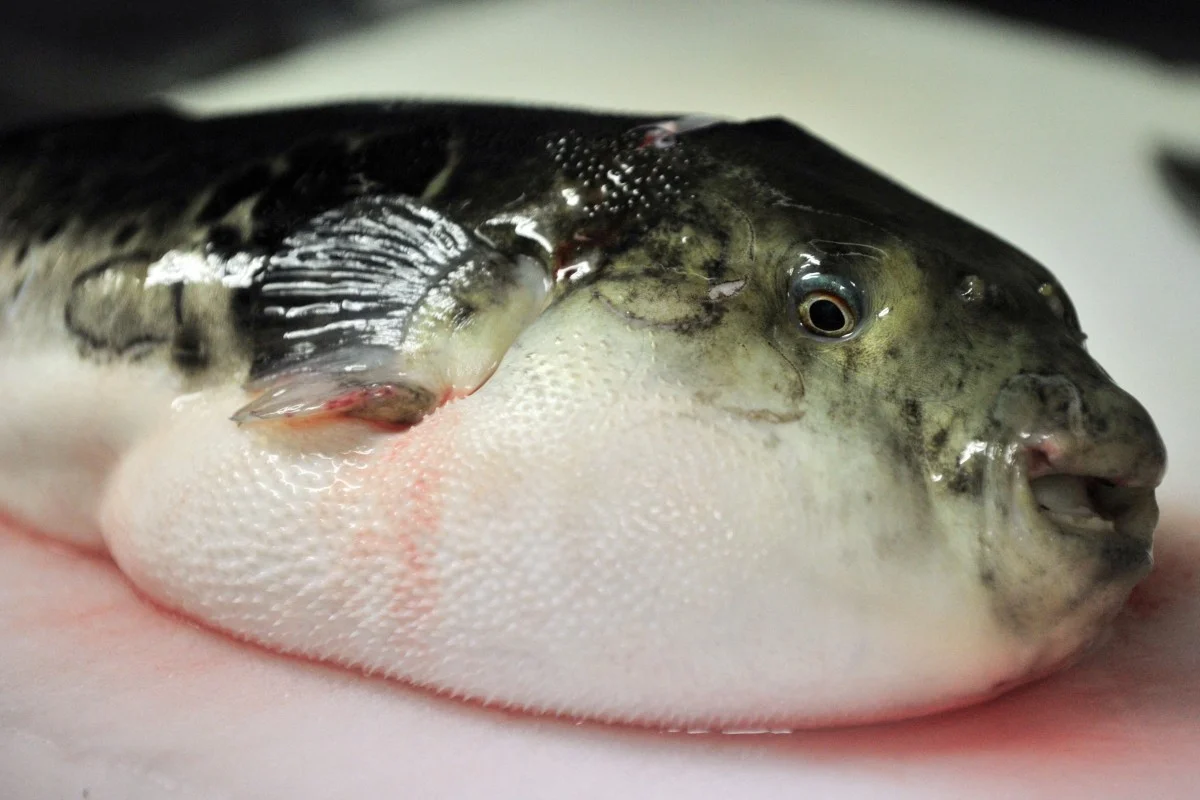
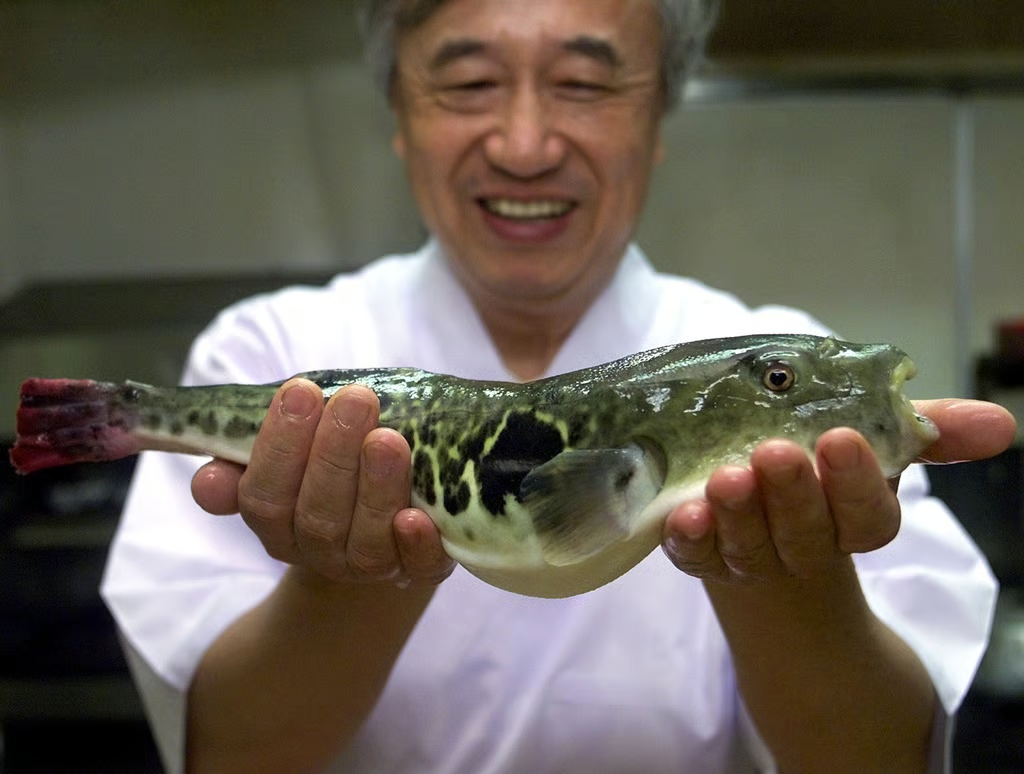
Fugu – the collective Japanese name for several species of edible pufferfish – is prized as much for the danger surrounding its preparation as for its subtle flavour.
Many species contain tetrodotoxin, a powerful neurotoxin with no known antidote that can cause paralysis, respiratory failure and death.
Since 1958, anyone wishing to prepare pufferfish for public consumption has had to obtain a licence first, a process that takes at least two years and defeats roughly two-thirds of those who attempt it.
Chefs learn to strip out the fish’s liver, ovaries, eyes and skin – tissues where the poison concentrates – with the precision of a brain surgeon and the nerve of a bomb-disposal technician.
But that hard-won expertise is now being undermined by climate-induced interbreeding, as experts say Japan’s coastal waters are heating up at roughly twice the global average rate.
Spotted pufferfish, once largely confined to the Sea of Japan, have spent the past decade steadily pushing northward in search of cooler currents. Some slipped through the Tsugaru Strait – the channel separating Honshu from far northern Hokkaido – where they have met and mated with the region’s native pufferfish species.
The resulting hybrids now make up as much as 40 per cent of local catches, according to a recent study of fish caught off Fukushima and Ibaraki prefectures.
“We started seeing these spotted fugu on the Pacific coast in 2012 as temperatures in the Sea of Japan became too high for them,” said Professor Hiroshi Takahashi of the National Fisheries University in Shimonoseki, Yamaguchi prefecture.
Temperatures in the waters there were “among the fastest rising anywhere in the world”, he told This Week in Asia, adding that the changes in pufferfish had been happening just as fast.
Some spotted pufferfish had ventured down the east coast as far south as Tokyo Bay, Takahashi said, only to be driven north again as those waters also warmed.
The trouble is not that hybrids are more toxic than their ancestors, it is that nobody yet knows how interbreeding has affected the distribution of toxins.
Each species of pufferfish stores tetrodotoxin in a different combination of organs and Japan’s health ministry has not yet been able to establish which parts of the new hybrids are safe to eat and which are not.
Until it does, the government has banned the sale or consumption of hybrid fugu– but this ban is almost impossible to enforce.
“They are very hard to identify,” said Takahashi, whose team has developed a DNA test capable of distinguishing hybrid fish and hopes to make the technology commercially available to fishermen who currently have no reliable way of screening their catch.
None of this is likely to diminish fugu’s deadly mystique. The dish has been eaten in Japan for centuries, enjoyed despite – or because of – the risks involved.
Every year, new tales emerge of amateur anglers preparing the fish to eat against the advice of anxious relatives and not surviving the attempt.
Diners speak of a faint numbness in the lips as evidence of a narrow escape and the emperor of Japan is barred from eating fugu altogether, lest even a licensed chef makes a mistake.
Urban legend holds that chefs who do poison a customer are honour-bound to end their own life, with their own knife, in atonement – though this is a myth.
For their part, Japaneserestaurateurs are, perhaps unsurprisingly, keen to play down the risks.
A spokeswoman for Miyawaki Fugu Club, an upscale restaurant in Tokyo’s Ginza district, said its chef works exclusively with farmed tiger pufferfish from a long-established supplier, which she insisted were “completely safe”.
“What happens to marine ecosystems is one of the hot-button issues of the day, particularly in Japan, because the waters here are warming at twice the global average rate,” he said.
During fieldwork off the Izu peninsula, south of Tokyo, three years ago, local fishermen told him that they had lost virtually their entire kelp crop and that the abalone once abundant in those waters had vanished.
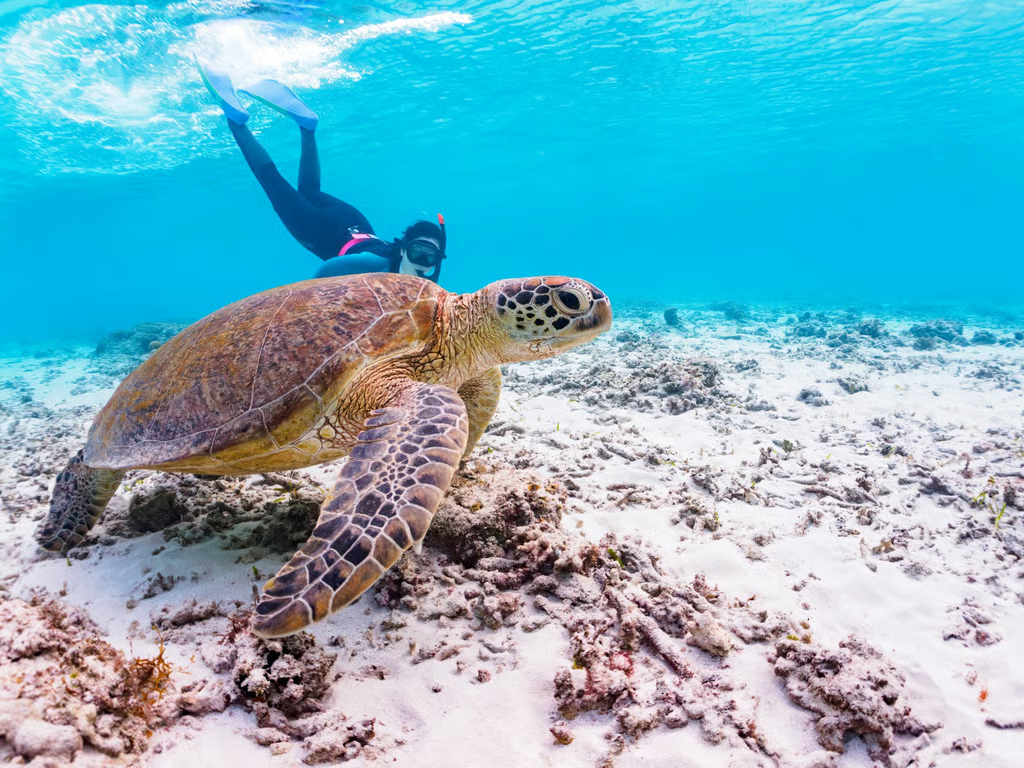
In their place, they said they were seeing far more sea turtles, as well as large schools of brightly coloured fusiliers – the prefecturalfish of Okinawa, some 1,400km (870 miles) to the south.
“Last year, our summer in Okinawa was 30 days longer than average, and we had 120 days when the water temperature was around 30 degrees Celsius (86 degrees Fahrenheit),” Reimer said.
He warns that the picture is not simply one of fish and other marine life swimming steadily north in search of more comfortable temperatures, however.
Global warming is also destabilising weather patterns, making them less predictable. Waters off Kyushu, the southernmost of Japan’s main islands, that might otherwise suit certain species are increasingly prone to temperature swings that could make them unsuitable after all.
Even so, the broader direction is unmistakable. Kyushu’s waters have seen a marked rise in shark sightings in recent years, including large tiger sharks – one more sign of the changes occurring beneath the surface of Japan’s seas.