Japan Inc. Now Sells No Yen to Invest Abroad

Earnings on Japan’s foreign direct investment (FDI) reached 103% of new FDI in 2022–25. With dividends and retained earnings counted together, Japan Inc. now needs to sell little yen to invest abroad.

[by OKUBO Takuji]

Key takeaways

  • Foreign affiliates now earn about as much as Japan invests abroad each year. Reinvested earnings, dividends and interest together reached 103% of new outward FDI in 2022–25, against 48% in 1996–2000.
  • Dividends from foreign affiliates account for a growing share of Japanese corporate profit. We estimate that foreign affiliates contributed 13.4% of Japan Inc.’s earnings in FY2025, up from 1.7% in FY1996.
  • Corporate investment abroad now involves little net yen selling. After dividends and interest paid home, the estimated outflow has been close to zero since 2022, down from about ¥5 trillion a year, or about 1% of GDP, on average in the 2010s.

Japan’s FDI stock now earns 103% of new investment

It is often said that Japan’s ageing population and slow growth give its companies too few investment opportunities at home. A Japanese government report in 2024 included the following passages.

“Japan’s ageing and shrinking population depresses expected demand at home. Expected returns remain higher abroad, so Japanese companies have accelerated outward direct investment” (my translation). — MATSUBAYASHI Yōichi [松林 洋一], MOF PRI, chapter 8, p.136.

“Companies invested abroad because they saw no promising investments in Japan; they are unlikely to bring back every return. On a cash-flow basis, the external balance is in deficit and is one factor behind the weak yen” (my translation). — KARAKAMA Daisuke [唐鎌 大輔], MOF PRI, chapter 10, pp.178 and 175.

However, my review of recent data shows that while their premise of low growth prospects in Japan is probably still right, the direct investment Japan has accumulated abroad has reached a level where it earns enough to cover Japan’s new investment abroad. This changes the exchange-rate implication even if Japan keeps investing abroad.

As chart 1 shows, earnings on the accumulated investment stock rose from 48% of new outward FDI in 1996–2000 to 103% in 2022–25.

Chart 1
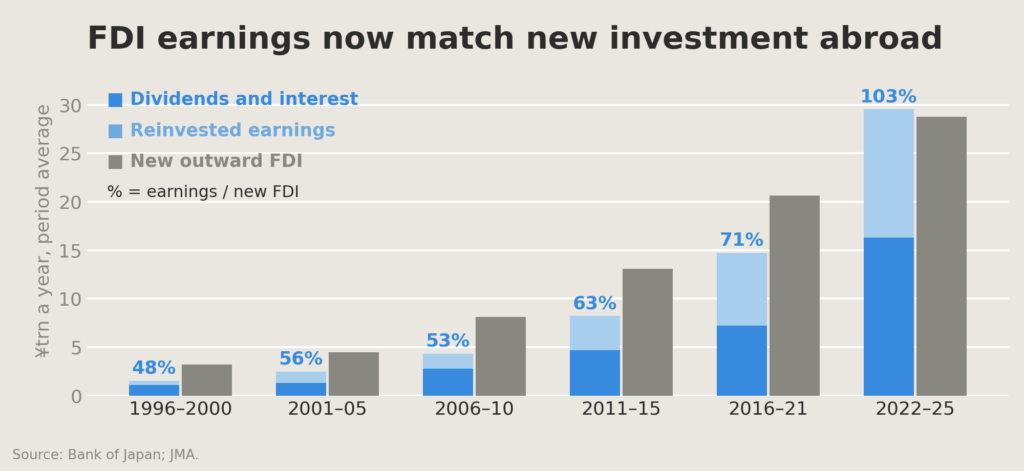
Overseas affiliates pay interest and dividends to their parent companies in Japan. Those dividends have become a sizable part of corporate Japan’s income: we estimate that they made up 13.4% of Japanese corporate profit in FY2025, up from 1.7% in FY1996.

When foreign affiliates retain their earnings on their balance sheets, Japan’s balance of payments statistics record them as FDI from Japan, even though no money crosses the border. While the companies receiving FDI dividends and the companies paying for new FDI are not necessarily the same, Japan Inc. as a whole is now financing its FDI almost entirely from the earnings of its overseas affiliates. At the current level of FDI, little new yen needs to be converted into foreign currencies as Japan goes about investing abroad.

In the rest of this report, I explain how foreign direct investment by Japanese companies evolved, and its near-term outlook. This report is the third in a series on the yen repatriation theme that I have published over the past few weeks, following “Yen Repatriation Starts with the Whale”, on capital flows through Japan’s national pension funds, and “Mrs Watanabe No More”, on Japanese households’ assets invested abroad.

A strong yen helped drive Japan’s first outward FDI boom

Japan’s outward investment was heavily restricted after WWII, requiring case-by-case permission from the government. Approvals became more and more automatic over the years until outward investment became “free in principle” in 1980. Trade friction with the US-led Japanese carmakers to restrain their exports from 1981, pushing them to build factories abroad. The rapid appreciation of the yen was also a factor. The yen strengthened from ¥242 per dollar before the Plaza Accord in September 1985 to ¥121 by the end of 1987. Japanese producers had to move lower value-added work abroad. The strong yen also gave Japanese financial institutions sizable purchasing power for a while, until the stock and property bubbles burst in 1990 and 1991.

All of these factors contributed to a rapid increase in outward FDI through the 1980s and 1990s (chart 2).

Chart 2

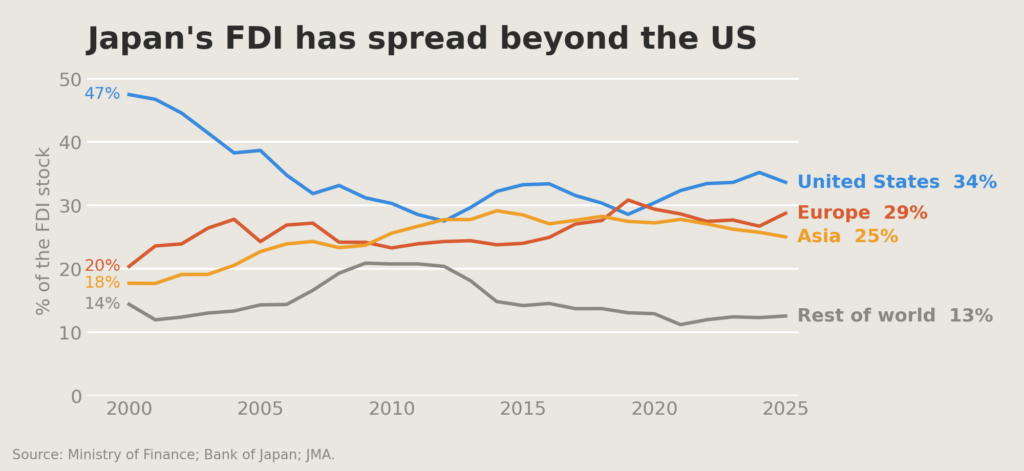
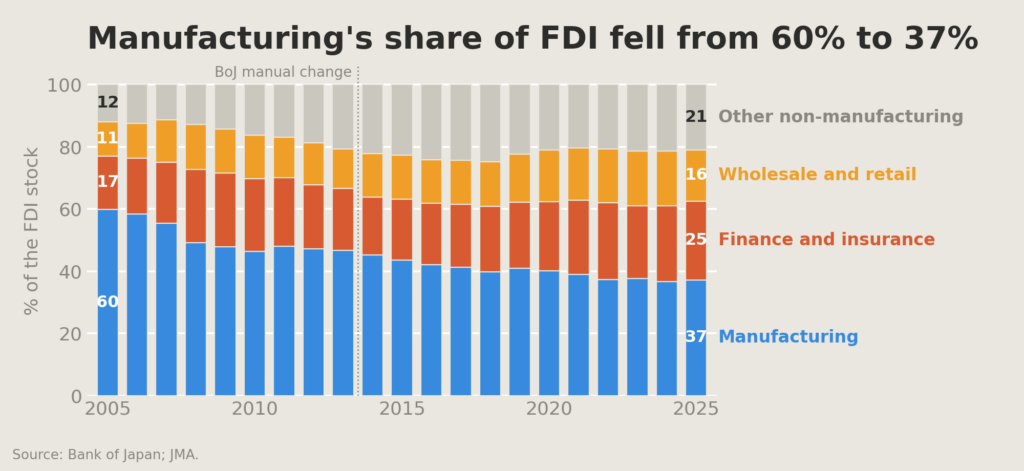
Even after the bubble burst, the strong yen kept pushing manufacturers to move abroad. In 2005, manufacturers accounted for 60% of the FDI stock. As Japanese manufacturers expanded their supply chains abroad, Asia’s share of outward FDI rose from about 12% in FY1986–90 to 19% in FY1995–99, and Asia held 23% of the FDI stock by 2005 (chart 3).

Chart 3
Japan’s outward FDI stock rose to 56% of GDP

The next phase was sustained by a different pressure. With weak growth and low interest rates at home, Japan Inc. kept investing abroad, across a broader range of industries. Between 1995 and 2025, the stock of FDI rose from 9% of Japan’s GDP to 58% (chart 4). In 2025, it is as large as about 38% of the private sector’s domestic fixed capital, on our estimate.

Chart 4

By industry composition and by destination compositions changed over time. Manufacturing’s share of the FDI stock had fallen to 37% by 2025, giving Japan’s FDI more breadth. By destination, we are seeing a revival of FDI toward the United States. It accounted for 34% of the stock in 2025, Europe 29% and Asia 25% (see earlier chart 3).
Thus, after decades of overseas investment, Japan’s FDI stock is now large enough that its earnings are sufficient to finance new investment abroad, at least for now. In the next section, I consider whether this will continue, and in particular whether Japanese companies may bring an even larger share of their overseas earnings back to Japan, given the weak yen, higher borrowing costs in yen and possibly better investment opportunities at home.

The weak yen has slowed offshoring, not reversed it

The real depreciation of the yen over the past 15 years made production in Japan more competitive. There is some evidence that manufacturers are considering bringing production back to Japan. The 2023 manufacturing white paper found more firms shifting production back from China than moving there, and they named the weak yen as one reason. We see some signs of reshoring. Japanese manufacturers’ overseas production ratio rose from 18.0% in FY2011 to 27.2% in FY2023, but it may have started to decline or at least stabilize. The ratio fell to 26.7% in FY2024. A Cabinet Office survey of listed manufacturers puts the ratio at 24.5% in FY2025, and their plan for FY2030 is broadly unchanged at 24.7%. The weak yen seems to have stabilized the wave of offshoring, but I see no firm evidence of a move back onshore yet.

Domestic investment has grown slowly despite the weak yen

There are tentative signs that domestic capital spending is starting to grow again. For three decades it grew at a very low speed. In real terms, private business investment rose only 26% between FY1997 and FY2025, less than 1% a year. In comparison, capital spending grew by about 4% a year on average in the United States. In my view, a weak currency is only one of the factors manufacturers weigh in designing their global production chains. The weak yen makes production in Japan competitive today, but they have also seen the exchange rate swing violently within short periods. Japan also has a shrinking population problem. It started to address it by opening a door to immigration, but the door is only tentatively open. Overall, my view is that the weak yen alone is unlikely to give Japan Inc. sufficient incentive to bring its capital back to Japan and to the yen.

Economic security is bringing some production home

The government is pushing harder than the currency, mostly in the name of economic security, even before the Takaichi government came along. The government currently has a ¥250 trillion domestic investment target for FY2040 and named AI and semiconductors among its 17 strategic fields. Semiconductors are where the money has gone furthest. In November 2024, under the Ishiba government, Japan committed more than ¥10 trillion of public support to AI and semiconductors by FY2030, aiming to draw more than ¥50 trillion of public and private investment over ten years. Japan managed to lure a TSMC plant to Japan, backed by a sizable subsidy. Rapidus, a government-supported Japanese semiconductor maker, has received a sizable subsidy and is building a factory in Hokkaido. Japan’s production of integrated circuits and discrete semiconductors rose from ¥2.7 trillion in 2019 to ¥4.1 trillion in 2025.

Under the name of economic security, the Japanese government is promoting other industries such as batteries, shipbuilding and pharmaceuticals. Defence spending adds to the push. Japan’s defence budget rose from about ¥5 trillion in FY2022 to ¥9.0 trillion in FY2026. Some defence contractors, such as Mitsubishi Heavy Industries, have doubled their defence revenue.

Japan’s industrial-policy record gives reason for caution

The Japanese government and the Ministry of Economy, Trade and Industry (METI), the key agency behind Japan’s industry policy, may claim some expertise in their industrial policies. Empirical studies in the past paint a poor track record, though. Rapidus, the most ambitious semiconductor project, has had no independent cost-benefit assessment (Negrine et al., 2025). While defence and economic security-driven policies have a different logic, I doubt that these industrial policies will succeed in bringing large-scale manufacturing investment back to Japan so long as macro factors such as Japan’s demography remain unfavourable.

FDI no longer appears to drive yen weakness

The weak yen and non-economic geopolitical factors do point to a halt in Japan’s four-decade offshoring trend, although it is a stabilization, rather than an economy-wide reversal of past offshoring. Japan Inc. will continue to invest more abroad, rather than within its borders. Given the sizable growth in the stock of cumulative FDI, Japan Inc. no longer needs to convert yen into overseas currency to keep investing abroad though. Net of dividends and interest paid home, Japan’s FDI sold about ¥5 trillion of yen a year, or about 1% of GDP, on average in the 2010s; since 2022 the net flow has been close to zero. There is also an interesting development in an effort to allow more share-exchange based M&A for cross-border deals that will further reduce the need for Japanese companies to spend their yen to purchase overseas assets. In my view, Japan Inc.’s FDI is no longer a factor to drive the yen weaker.

References

Why Is the World So Nightmarish?

The phrase, “La Belle Époque” (French: “The Beautiful Era”) refers to the atmosphere in Europe and especially France, the high point of which lasted from 1900 to 1914, with the outbreak of World War I. The whole era was characterized by the phrase, “la douceur de la vie” (French: “the sweetness of life”). People of the time would say that if you weren’t alive then, they could not communicate how charming life was at the time.

The sinking of the Titanic in April, 1912 is the symbolic catastrophe that heralded the end of the era. Anyone who watched Downton Abbey would perhaps remember the opening scene, which depicts the newspaper announcing it with a screaming headline.

The great masterpiece, Journey to the End of the Night (French: Voyage au bout de la nuit, 1932), describes the whole world around World War I as a nightmarish battlefield of previously unseen scope. Céline’s protagonist, Ferdinand, travels the world, from battles in Europe to Africa, then to New York and Detroit’s Ford assembly line before returning to France, finding that the nightmare is global and inescapable.

Céline died within 24 hours of Ernest Hemingway. Hemingway is famous for the quote from The Sun Also Rises (set in the 1920s), “The world breaks everyone and afterward many are strong at the broken places. But those that will not break it kills.”

The question is how could we ever explain complete evaporation of the sweetness of life and transformation into such a nightmare, culminating into the world of today.

Lastly, think of the point made in Sebastian Haffner’s The Meaning of Hitler, how Hitler fit into this nightmarization of the world. Haffner writes:

It is impossible for a serious historian to maintain that without Hitler world history in the twentieth century would have taken the course it has taken. It is by no means certain that without Hitler a second world war would even have taken place; it is quite certain that if it had taken place it would have taken a different course — possibly even with different alliances, fronts and outcomes. Today’s world, whether we like it or not, is the work of Hitler. Without Hitler there would have been no partition of Germany and Europe; without Hitler there would be no Americans and no Russians in Berlin; without Hitler there would be no Israel; without Hitler there would be no de-colonization, at least not such a rapid one; there would be no Asian, Arab or Black African emancipation, and no diminution of European preeminence. Or, more accurately, there would be none of this without Hitler’s mistakes. He certainly did not want any of it.

(The Meaning of Hitler, Harvard University Press, 1979, page 100)

No-one has yet captured how the nightmarish feeling of 2025 is itself downstream from the preceding era.

India: Deep History

In his lectures, Professor Amartya Sen, the Harvard Nobel Prize in Economics winner, mentions Sir Mortimer Wheeler, Director-General of the Archaeological Survey of India. Wheeler wrote, while reporting on the excavation of the Indus Valley Civilization (of India), that the plumbing and sewerage were advanced, in some ways surpassing modern equivalents.

Sen’s larger point is that history is characterized by phases of rise and fall and not just classes and class struggles à la Marx.

Consider the following depiction of the East India Company, from The Anarchy: The Relentless Rise of the East India Company (also subtitled The East India Company, Corporate Violence, and the Pillage of an Empire) by William Dalrymple.


On 28 August 1608, Captain William Hawkins, a bluff sea captain with the Third Voyage, anchored his ship, the Hector, off Surat, and so became the first commander of an EIC vessel to set foot on Indian soil.

India then had a population of 150 million — about a fifth of the world’s total — and was producing about a quarter of global manufacturing; indeed, in many ways it was the world’s industrial powerhouse and the world’s leader in manufactured textiles. Not for nothing are so many English words connected with weaving — chintz, calico, shawl, pyjamas, khaki, dungarees, cummerbund, taffetas — of Indian origin. It was certainly responsible for a much larger share of world trade than any comparable zone and the weight of its economic power even reached Mexico, whose textile manufacture suffered a crisis of ‘de-industrialisation’ due to Indian cloth imports. In comparison, England then had just 5 per cent of India’s population and was producing just under 3 per cent of the world’s manufactured goods. A good proportion of the profits on this found its way to the Mughal exchequer in Agra, making the Mughal Emperor, with an income of around £100 million,* by far the richest monarch in the world.

The Mughal capitals were the megacities of their day: ‘They are second to none either in Asia or in Europe,’ thought the Jesuit Fr Antonio Monserrate, ‘with regards either to size, population, or wealth. Their cities are crowded with merchants, who gather from all over Asia. There is no art or craft which is not practised there.’ Between 1586 and 1605, European silver flowed into the Mughal heartland at the astonishing rate of 18 metric tons a year, for as William Hawkins observed, all nations bring coyne and carry away commodities for the same’. For their grubby contemporaries in the West, stumbling around in their codpieces, the silk-clad Mughals, dripping in jewels, were the living embodiment of wealth and power — a meaning that has remained impregnated in the word ‘mogul’ ever since.

By the early seventeenth century, Europeans had become used to easy military victories over the other peoples of the world.

* Over £10,000 million today.

Think of the larger point: what you just read is the story of Indian de-industrialization and its negative results. Ask yourself whether American de-industrialization is something of an echo of this, as manufacturing is offshored.

World-Watching: Container Shipping Financial Insight, Nov. 2023

[from Drewry Shipping Consultants]

Driven by weak 3Q23 financial results, the Drewry Container Equity Index decreased 3.7% last month (as of 22 Nov 2023). Additionally, asset prices continue to fall due to the supply-demand imbalance.

  • Container shipping companies’ 3Q23 financial results showcased a sharp dip in profits or even losses. On a group level, eleven liners (which report quarterly results) among our portfolio of 13 companies reported an average slump of 54.6% YoY in their 3Q23 topline. Operating costs declined 18.1% YoY amid falling chartering costs and lowering bunker prices. However, the cost reduction was insufficient to offset the plunge in topline; thus, EBIT contracted 94.1% YoY on average.
  • The Drewry Container Equity Index tumbled 28.1% YTD 2023 (ending 22 November), driven by lowering freight rates (WCI: -30.7% in YTD 2023), which squeezed earnings over the quarters. On the contrary, the S&P 500 posted an 18.4% growth. The Drewry Container Equity Index declined 3.4% in the month ending 22 November 2023. Talking about equity prices individually, APMM’s stock price fell 9.0% amid EBIT loss for its Ocean segment in 3Q23, staff cuts and reduced capex guidance, highlighting APMM’s efforts toward reducing costs faced with the bleak industry outlook. Hapag-Lloyd’s stock price slumped 22.2% as its EBIT margin (3Q23: 5.1%) slid below its pre-pandemic level (3Q19: 7.8%). ZIM became the first carrier to report impairment of assets worth USD 2.0bn in 3Q23, and its stock price fell 18.1%. Meanwhile, China-exposed container companies benefitted from the positive sentiment arising from the proposed fiscal stimulus by the Chinese government, possibly boosting the out-of-China and intra-Asia trades. Asian stocks in the broader index rose 2.0% to 19.4% in the month ending 22 November 2023.
  • Mainly driven by weak earnings prospects, the Drewry Container Equity Index trades at a P/B of 0.5x, a 47.5% discount to its pre-pandemic average (2013-19). We expect freight rates to fall sharply in 2024 and increasingly incur losses. Thus, we expect the multiple to remain suppressed.
  • As the fleet of container shipping companies expands, the charter market softens. For instance, 1-year TC rates declined 14.2% and 52.5% YoY in October for vessels sized 1,110 teu and 8,500 teu. Rates declined more for larger vessels as these constitute the majority of the order book and new deliveries. The YoY decline has continued since October 2022, but rates improved slightly during April-May 2023. However, this was not due to the fundamentally strong market but MSC and CMA CGM’s aggressive chartering of vessels to expand their fleets. Now that the two companies have stopped chartering in vessels, the charter market continues to decline.
  • Driven by the softening charter market, second-hand asset prices are also weakening. In October, on a YoY basis, prices for five-year-old vessels (2,700 teu and 7,200 teu) contracted 30.6% and 31.5%, and for 10-year-old ships, prices tumbled between 36.7% and 53.2%. Contrary to the sale and purchase market, newbuild prices (1,500 teu and 14,000 teu) continue to increase and rose by an average of 2.2% YoY, led by a shortage of capacity in shipyards.
  • The charter market and the S&P market have a direct impact on container shipping companies’ earnings. Costs related to chartering-in slots or vessels from other non-operating vessel owners form a significant portion of container shipping companies’ cost structure. In the 3Q23 results, this cost was reduced,
    marginally relieving downside pressure on the operating margin of container shipping companies. In line with the declining charter market, we expect this trend to continue in 4Q23. We also expect other companies to follow ZIM in reporting impairment losses as prices for older vessels continue to fall.

Read the report [archived PDF] for additional graphs.

Zheng Yongnian (郑永年) on How to Address Western Public Opinion on China: Facts, Science and Reason

[from Pekingology at the Center for China and Globalization (CCG)]

“Be open, open, and more open,” especially to businesses, investors, media, universities, and research institutions. And tit-for-tat doesn’t work, the professor says.

by Zichen Wang, Shuyuan Han, and Li Huiyan

Professor Zheng Yongnian (郑永年), the Founding Director of the Institute for International Affairs at the Chinese University of Hong Kong, Shenzhen, on January 28 published an article on how China should address Western public opinion on China. His advice is in the last part of the article, and below is a translation.

(Emphasis by Pekingnology.)

First, we need to understand how such narratives are formed. Historically, China held a bias due to its self-isolation and limited knowledge of the West. Despite losing the two Opium Wars, Chinese intellectuals at that time still saw Westerners as uncivilized. It was not until China was defeated by Japan, a neighboring country once considered as China’s student, that they realized their ignorance and a need for reform. Before China’s Reform and Opening up, Chinese people barely knew anything about the West. They always assumed Westerners were in deep distress, repeating the same lack of understanding of the West.

Similarly, the West’s uncertainty and fear towards China’s rise stem from a lack of understanding and even fear of the country, and their ingrained ideology would lead to misconceptions.

China is the world’s second-largest economy. The externalities and influence of its economy on the West are obvious. Upon joining the WTO, some Chinese people also felt unsettled by the externalities of the West. Some said, “the wolf is coming.” Now it is the West that is experiencing such worries.

It is crucial to recognize the significant impact of the Western hypocritical narratives against China, even if they are based on ideology rather than facts. We must also acknowledge that ideology-based public opinion from the West can exert a powerful influence on their policies toward China.

Historically, the West tended to demonize others while presenting themselves as morally superior, which enabled them to apply Social Darwinism to international politics easily and thus legitimizing conflicts and even wars with other nations. Given the Soviet Union’s failure in the ideological arena during the Cold War, we should by no means ignore any ideology-based public opinion toward China from the West.

Second, to make rational responses to the Western ideology-based criticisms, we should draw lessons from the history of the world economy, such as the lessons of the Soviet Union, as well as our practices, such as the rhetorical battle with the West in the past few years. Coming up with an externally-facing public opinion based on a different ideology is not the most effective in addressing public opinion attacks based on an ideology. Empirically, tit-for-tat is ineffective and can worsen the situation. Again, the failure of the Soviet Union is a prime example, as its battle with a Western ideology failed. When faced with China-demonizing based on ideology from the West, we need to do the simplest thing, namely resorting to facts, science, and reason.

Third, and most importantly, China needs to prioritize its sustainable development, which ultimately benefits the country itself. It is important to recognize that the foundation of the government’s governance lies in its citizens, not Western praise. The support from its people is crucial for both the nation’s longevity and stability., China’s sustainable development also benefits the world economy by boosting its growth. As mentioned above, China has been the largest contributor to the growth of the world economy since it joined the WTO.

It is crucial to prioritize the building of a knowledge system based on China’s practical experiences. Regarding global soft power, we need a knowledge system based on our experiences rather than a certain ideology. While there has been a proposal for an autonomous knowledge system, continuous effort is still required.

Fourth, given the substantial externalities of our economy, we must further communicate and coordinate with other countries on economic policies, regardless of their respective sizes. Our duty is to fulfill the responsibility as a major player in the international community, which also benefits China.

After the 1997-1998 Asian financial crisis, China promised not to devalue its currency, and that commitment became an international public good in Asia. Similarly, after the global financial crisis from 2007 to 2008, China made similar contributions. As China re-opens its economy after the pandemic, it is important not only to take note of the hypocritical comments from certain quarters in the Western world but also to recognize the positive evaluations and high expectations from many international organizations.

Fifth, we must be open, open, and more open. Despite China’s efforts, there remains a persistent ideological camp in the West that views China through an ideological lens, a situation made worse by the past three years of the pandemic. The pandemic was so severe that it hindered travel across borders; as a result, some Western media and scholars tend to assess China through ideology since they couldn’t come here to see the facts with their own eyes.

The assessment of China through a uniform ideological lens appears to have strengthened the original Western ideological camp. However, the United States and the West have more than one ideology, and not all people believe in the prevailing ideology in the public opinion sphere. China’s openness provides a “seeing is believing” opportunity for different groups in the West. China should increase its openness to Western groups, including businesses, investors, media, universities, and research institutions. The changes in their understanding could render those ideological-based public opinions less effective.

From ASEAN and G20 to APEC, as World Leaders Meet in Person Again, 3 Reasons to Root for Multilateralism

By Wang Huiyao | Founder of the Center for China and Globalization (CCG)

Over the past two weeks, Asia has played host to the most intense sequence of multilateral summits since the pandemic began, as national leaders gathered for meetings organized by ASEAN, the G20 and APEC. Although overshadowed by geopolitical tensions, the meetings marked a welcome return to in-person summit diplomacy, and the better-than-expected outcomes show hope yet for multilateralism.

The conclaves began in Phnom Penh with the annual summit of the Association of Southeast Asian Nations. At the first of such in-person events in almost three years, ASEAN leaders took the positive step of agreeing in principle to admit East Timor as the 11th member of the organization.

As leaders moved on to Bali for the Group of 20 summit, expectations were low after ministerial meetings in the run-up had failed to produce consensus. Earlier in the year, given fractures in the wake of Russia’s invasion of Ukraine, there was a question mark over whether the G20 could even go ahead or survive in its existing form.

In the end, the summit surpassed expectations by producing a joint declaration after intense negotiations, with leaders finding the compromises necessary to unite in declaring that “today’s era must not be of war” and pledging to uphold the multilateral system.

The summit also saw a positive face-to-face meeting between China’s President Xi Jinping and U.S. President Joe Biden, their first as leaders, signaling a willingness to halt the downward trajectory of China-U.S. relations.

In Bangkok, the 21 leaders of the Asia-Pacific Economic Cooperation forum also pledged to uphold and strengthen the rules-based multilateral trading system. Importantly, the group agreed on a multi-year work plan for an Asia-Pacific free trade area.

Reflecting on these three summits, three takeaways give reason for cautious optimism that multilateralism can yet be revived and play a major role in solving our challenges.

First, and perhaps most obviously, the return of in-person summit diplomacy is a welcome uplift for global cooperation. Virtual formats played a useful interim role at the height of the pandemic but were never a substitute for getting leaders in the same room. That is especially when it comes to interactions on the sidelines, often as important as the main event.

China’s return to diplomacy at the highest level was a further boost, both for the nation and the rest of the world.

In addition to Xi’s highly anticipated meeting with Biden, the Chinese leader met over a dozen other leaders at the G20 and APEC summits, including a warmer-than-expected first meeting with Japanese Prime Minister Fumio Kishida and his first meeting with an Australian prime minister since 2016.

Leaders got to meet their new counterparts for the first time or build on existing relationships, which can only help global cooperation.

The second takeaway is that as grave as our challenges are, the threat of escalating conflict and severe economic pressures on all nations seem to be focusing minds and increasing the willingness to engage and cooperate—out of necessity if nothing else.

The G20 summit was the second major one this year to surpass expectations after the 12th World Trade Organization Ministerial Conference in June surprised observers by agreeing on a plan to reform the organization and its dispute settlement mechanism. The G20 statement reiterated support for this WTO reform plan, which will be critical to get the free trade agenda back on track and provide a much-needed boost for the global economy.

Third, and perhaps most significantly for the long term, the recent summits marked an acceleration of the trend towards multi-polarization in international diplomacy, and in particular, the rising influence of non-aligned “middle powers” to shape multilateral outcomes.

The middle powers represented at ASEAN, the G20 and APEC have huge stakes in avoiding a bifurcation of the global economy that might result from a new cold war. They don’t want to be forced to pick sides and many show a growing willingness and ability to build bridges and restore positive momentum for multilateralism.

Indonesia is a prime example. The country’s strategic heft and non-aligned credibility make it well-placed to bridge different camps. President Joko Widodo made a big political bet on the success of the G20 and has won praise for the deft diplomacy that kept the organization alive and got it to a joint statement.

The Indian delegation reportedly also played a big role in achieving consensus on language in the statement, with the BRICS group (Brazil, Russia, India, China and South Africa)—as well as Indonesia—turning out to be crucial swing voters in securing the joint statement. One Indian official said it was “the first [G20] summit where developing nations shaped the outcome.”

There is scope for this trend to continue next year as middle powers continue to rise in stature, and India and Indonesia take over the presidency of the G20 and ASEAN, respectively. Brazil will host the G20 the year after.

Over in Sharm el-Sheikh at the COP27 UN climate summit, another middle power—the host Egypt—also won praise for helping to shepherd a historic financing deal for poor countries affected by climate change. But the ultimate failure to reach a commitment to phase down fossil fuels was a sobering reminder of the huge difficulties that remain in forging the global consensus needed to overcome our shared challenges.

World-Watching: How the G20’s Succession of Developing Country Presidencies Could Help Re-shape the Global Economy

[from Asian Development Bank Institute]

Indonesia’s Group of 20 (G20) presidency in 2022 marks the start of three successive years in which the annual forum of the world’s largest economies will be hosted by developing countries, to be followed by India in 2023 and Brazil in 2024.

In this podcast, Pramod Bhasin, Chair of the Indian Council for Research on International Economic Relations (ICRIER), discusses India’s G20 presidency countdown and policy imperatives. He also describes the outlook for Indonesia, India, and Brazil’s G20 presidencies and their potential significance for the global economy.

[Archived podcast MP3]

Read the transcript. [Archived PDF]

View the full playlist of audio insights into ADBI’s ideas for developing Asia and the Pacific.

Education and Hegemonial Struggles

Dominance by Design, by Professor Michael Adas, is a very “intellectually useful” overview of the American thrust towards world domination by force, whether through the backdoor (covert means) or through the front door (invasion of Iraq in 2003, etc).

Michael Adas is the Abraham E. Voorhees Professor of History at Rutgers University, New Brunswick.

“Long before the United States became a major force in global affairs, Americans believed in their superiority over others due to their inventiveness, productivity, and economic and social well-being. U.S. expansionists assumed a mandate to “civilize” non-Western peoples by demanding submission to American technological prowess and design. As an integral part of America’s national identity and sense of itself in the world, this civilizing mission provided the rationale to displace the Indians from much of our continent, to build an island empire in the Pacific and Caribbean, and to promote unilateral—at times military—interventionism throughout Asia. In our age of “smart bombs” and mobile warfare, technological aptitude remains preeminent in validating America’s global mission.

Michael Adas brilliantly pursues the history of this mission through America’s foreign relations over nearly four centuries from North America to the Philippines, Vietnam, and the Persian Gulf. The belief that it is our right and destiny to remake foreign societies in our image has endured from the early decades of colonization to our current crusade to implant American-style democracy in the Muslim Middle East.

Dominance by Design explores the critical ways in which technological superiority has undergirded the U.S.’s policies of unilateralism, preemption, and interventionism in foreign affairs and raised us from an impoverished frontier nation to a global power. Challenging the long-held assumptions and imperatives that sustain the civilizing mission, Adas gives us an essential guide to America’s past and present role in the world as well as cautionary lessons for the future.”

(Harvard University Press, 2009)

The whole issue of hegemonial struggles (as opposed to left-wing emphasis on “class struggles”) is very eye-opening in terms of achieving a more comprehensive understanding of the newspapers and history books themselves.

For example, Paul Kennedy’s book, “The Rise of the Anglo-German Antagonism: 1860-1914” (1980) is a very important book in giving us this layer of reality which complicates the parallel layer of globalization forces from 1870-1914.

Globalization narrowly speaking is about econo-technical changes unifying prices and other economic variables, while hegemonial struggles involve the struggle for mastery by rival countries or blocs.

This book gives an account of the rivalry between Great Britain and Germany in the period leading to the First World War. It gives readers a thorough comparison of the two societies, their political cultures, economies, party politics, courts, the role of the press and pressure groups, and so on.

Hegemonial rivalries between nations, blocs, empires are a key “motor” in world history and globalization and this rivalry are entwined at all times. Holistic education is partly the understanding of how entwining governs the world around us, in all areas.

World-Watching: India

(from ICRIER Newsletter | November 2019 | Vol. III, Issue 11)

The November 2019 issue of the Newsletter provides a quick recap of ICRIER’s research and policy engagements during the month of October 2019.

Three research reports were released by ICRIER last month in the areas of competition, trade and investment and climate change (See below).

ICRIER also organized consultation workshops, dissemination and outreach events during the month. ICRIER researchers published several articles in leading newspapers and other media platforms on a variety of current issues such as growth, agriculture, trade, FTAs, RCEP, single use plastics and the Economics Nobel. We sincerely hope that you will take a few moments to glance through these updates and engage further with anything that interests you. We hope you enjoy the newsletter’s new format. As always, we welcome your valuable feedback.

Competition Issues in India’s Mobile Handset Industry

(Rajat Kathuria, Mansi Kedia and Kaushambi Bagchi)

Mobile phones have been the key to India’s technology revolution. India is the second largest mobile phone market globally, next only to China. At the end of 2018, the estimated number of smart phone users in India was 337 million, compared to 2.53 billion users worldwide. One would imagine that the exponential increase in cheaper smart phone models would displace the market for feature phones; to the contrary, feature phones continue to dominate the Indian market. While smart phone and feature phone shipments in 2018 Q3 were about the same, a comparison of growth rates shows that both phablets (large screen smartphones) and regular smartphones eclipse feature phones.

Read more (archived PDF).

Exploring Trade and Investment Opportunities between India and Select African and Asian Economies

(Anirudh Shingal, Neha Gupta, Minakshee Das, Akshaya Aggarwal and Varsha Jain)

Using descriptive statistical analysis, this study examines trade and investment opportunities between India and 41 African and Asian economies (mostly LDCs) by focusing on the latter’s export opportunities in the Indian market and on India’s investment opportunities in the selected countries. It also discusses barriers to realizing the identified trade and investment opportunities between India and the selected economies, based on a review of the existing literature.

Read more (archived PDF).

Financing Resilience against Natural Disasters

(Saon Ray, Samridhi Jain and Vasundhara Thakur)

Disaster Risk Resilience can be interpreted as global policies working for improving disaster risk reduction. The Sendai Framework for Disaster Risk Reduction is the guiding principle for efforts to improve resilience worldwide. This report links the global efforts for disaster risk reduction with resilient infrastructure. The report analyses the applicability of popular instruments for emerging economies, the role of the private sector, and challenges to implementation of resilience framework. It maps the evolution and status of disaster risk financing in India.

Read more (archived PDF).

ICANN 66 Pre-Meeting Briefing

ICRIER hosted the ICANN 66 Pre-Meeting Briefing on 18th October 2019 for its Indian stakeholders. This edition of the Pre-Meeting Briefing looked closely at the developments between ICANN 65 and ICANN 66 and highlighted some of the key policy discussions currently underway at ICANN. The event witnessed participation from various stakeholders from India, including representatives from the Ministry of Electronics & Information Technology (MeitY), National Internet Exchange of India (‘.in’ registry) along with Indian representatives active in various policy development processes at ICANN. ICANN 65 was held in Montreal, Canada, between 2-7 November 2019. ICRIER will also be hosting the ICANN 66 Readout during the first week of December 2019 to highlight some of the key takeaways from ICANN 66.

Read more [archived PDF].

Dissemination of the India-LDCs Trade and Investment Study

ICRIER organised Dissemination of the Report Exploring Trade and Investment Opportunities between India and Select African and Asian Economies on October 14, 2019 at Magnolia Hall, India Habitat Centre, Lodhi Road, New Delhi.

Welcome remarks were delivered by Dr. Rajat Kathuria, Director & CE, ICRIER and the Introductory Session was Chaired by Dr. Jayant Dasgupta, IAS (Retd.) Former Ambassador of India to the WTO. Dr. Anirudh Shingal, Sr. Fellow, ICRIER presented the key findings of the report, which was followed by a Panel discussion Chaired by Dr. Arpita Mukherjee, Professor, ICRIER.

Read more [archived PDF] [Presentation PDF] [Report PDF]

Market Incentives, Direct Income Support for Farmers are far more Effective in Increasing Agricultural Productivity

(Ashok Gulati, Sakshi Gupta)

Read article [archived PDF]

Cities at Crossroads: Single-use Plastic only Part of the Challenge

(Isher Judge Ahluwalia, Almitra Patel)

Read article [archived PDF]

From Plate to Plough: Agri-Policy Lessons from China

(Ashok Gulati & Sakshi Gupta)

Read article [archived PDF]

Growth, Income, Poverty and the Nobel

(Alok Sheel)

Read article [archived PDF]

Understanding the RCEP with Rajat Kathuria

(Rajat Kathuria)

Listen to podcast [archived MP3 audio] [PDF transcript]

The Five-trillion Math

(Alok Sheel)

Read article [archived PDF]

Has PM-Kisan Belied Expectations?

(Siraj Hussain)

Read article [archived PDF]

How Government Can Control Sudden Spike in Prices of Onion and Tomato

(Ashok Gulati & Harsh Wardhan)

Read article [archived PDF]

Best of Business Standard Opinion: Corporate Tax Cuts, Pollution Challenge…

(Durgesh K. Rai)

Read article [archived PDF]

India’s Trade with its FTA Partners: Experiences, Challenges…

(Durgesh K. Rai)

Read article [archived PDF]

India’s Trade Policy Should Lend an Ear to a Wider Range of Voices

(Ujjwal Krishna & Amrita Saha)

Read article [archived PDF]

Monsoon’s Late Surge Helps, But Floods Hurt Crop Prospects

(Siraj Hussain)

Read article [archived PDF]

Press Release: World Energy Outlook 2019 Highlights Deep Disparities in the Global Energy System

Rapid and widespread changes across all parts of the energy system are needed to put the world on a path to a secure and sustainable energy future

Deep disparities define today’s energy world. The dissonance between well-supplied oil markets and growing geopolitical tensions and uncertainties. The gap between the ever-higher amounts of greenhouse gas emissions being produced and the insufficiency of stated policies to curb those emissions in line with international climate targets. The gap between the promise of energy for all and the lack of electricity access for 850 million people around the world.

The World Energy Outlook 2019, the International Energy Agency’s flagship publication, explores these widening fractures in detail. It explains the impact of today’s decisions on tomorrow’s energy systems, and describes a pathway that enables the world to meet climate, energy access and air quality goals while maintaining a strong focus on the reliability and affordability of energy for a growing global population.

As ever, decisions made by governments remain critical for the future of the energy system. This is evident in the divergences between WEO scenarios that map out different routes the world could follow over the coming decades, depending on the policies, investments, technologies and other choices that decision makers pursue today. Together, these scenarios seek to address a fundamental issue – how to get from where we are now to where we want to go.

The path the world is on right now is shown by the Current Policies Scenario, which provides a baseline picture of how global energy systems would evolve if governments make no changes to their existing policies. In this scenario, energy demand rises by 1.3% a year to 2040, resulting in strains across all aspects of energy markets and a continued strong upward march in energy-related emissions.

The Stated Policies Scenario, formerly known as the New Policies Scenario, incorporates today’s policy intentions and targets in addition to existing measures. The aim is to hold up a mirror to today’s plans and illustrate their consequences. The future outlined in this scenario is still well off track from the aim of a secure and sustainable energy future. It describes a world in 2040 where hundreds of millions of people still go without access to electricity, where pollution-related premature deaths remain around today’s elevated levels, and where CO2 emissions would lock in severe impacts from climate change.

The Sustainable Development Scenario indicates what needs to be done differently to fully achieve climate and other energy goals that policy makers around the world have set themselves. Achieving this scenario – a path fully aligned with the Paris Agreement aim of holding the rise in global temperatures to well below 2°C and pursuing efforts to limit it to 1.5°C – requires rapid and widespread changes across all parts of the energy system. Sharp emission cuts are achieved thanks to multiple fuels and technologies providing efficient and cost-effective energy services for all.

“What comes through with crystal clarity in this year’s World Energy Outlook is there is no single or simple solution to transforming global energy systems,” said Dr. Fatih Birol, the IEA’s Executive Director. “Many technologies and fuels have a part to play across all sectors of the economy. For this to happen, we need strong leadership from policy makers, as governments hold the clearest responsibility to act and have the greatest scope to shape the future.”

In the Stated Policies Scenario, energy demand increases by 1% per year to 2040. Low-carbon sources, led by solar PV, supply more than half of this growth, and natural gas accounts for another third. Oil demand flattens out in the 2030s, and coal use edges lower. Some parts of the energy sector, led by electricity, undergo rapid transformations. Some countries, notably those with “net zero” aspirations, go far in reshaping all aspects of their supply and consumption.

However, the momentum behind clean energy is insufficient to offset the effects of an expanding global economy and growing population. The rise in emissions slows but does not peak before 2040.

Shale output from the United States is set to stay higher for longer than previously projected, reshaping global markets, trade flows and security. In the Stated Policies Scenario, annual U.S. production growth slows from the breakneck pace seen in recent years, but the United States still accounts for 85% of the increase in global oil production to 2030, and for 30% of the increase in gas. By 2025, total U.S. shale output (oil and gas) overtakes total oil and gas production from Russia.

“The shale revolution highlights that rapid change in the energy system is possible when an initial push to develop new technologies is complemented by strong market incentives and large-scale investment,” said Dr. Birol. “The effects have been striking, with U.S. shale now acting as a strong counterweight to efforts to manage oil markets.”

The higher U.S. output pushes down the share of OPEC members and Russia in total oil production, which drops to 47% in 2030, from 55% in the mid-2000s. But whichever pathway the energy system follows, the world is set to rely heavily on oil supply from the Middle East for years to come.

Alongside the immense task of putting emissions on a sustainable trajectory, energy security remains paramount for governments around the globe. Traditional risks have not gone away, and new hazards such as cybersecurity and extreme weather require constant vigilance. Meanwhile, the continued transformation of the electricity sector requires policy makers to move fast to keep pace with technological change and the rising need for the flexible operation of power systems.

“The world urgently needs to put a laser-like focus on bringing down global emissions. This calls for a grand coalition encompassing governments, investors, companies and everyone else who is committed to tackling climate change,” said Dr. Birol. “Our Sustainable Development Scenario is tailor-made to help guide the members of such a coalition in their efforts to address the massive climate challenge that faces us all.”

A sharp pick-up in energy efficiency improvements is the element that does the most to bring the world towards the Sustainable Development Scenario. Right now, efficiency improvements are slowing: the 1.2% rate in 2018 is around half the average seen since 2010 and remains far below the 3% rate that would be needed.

Electricity is one of the few energy sources that sees rising consumption over the next two decades in the Sustainable Development Scenario. Electricity’s share of final consumption overtakes that of oil, today’s leader, by 2040. Wind and solar PV provide almost all the increase in electricity generation.

Putting electricity systems on a sustainable path will require more than just adding more renewables. The world also needs to focus on the emissions that are “locked in” to existing systems. Over the past 20 years, Asia has accounted for 90% of all coal-fired capacity built worldwide, and these plants potentially have long operational lifetimes ahead of them. This year’s WEO considers three options to bring down emissions from the existing global coal fleet: to retrofit plants with carbon capture, utilisation and storage or biomass co-firing equipment; to repurpose them to focus on providing system adequacy and flexibility; or to retire them earlier.

Access the 2019 World Energy Outlook report.

About the IEA: The International Energy Agency, the global energy authority, was founded in 1974 to help its member countries co-ordinate a collective response to major oil supply disruptions. Its mission has evolved and rests today on three main pillars: working to ensure global energy security; expanding energy cooperation and dialogue around the world; and promoting an environmentally sustainable energy future.

International Energy Agency Press Office
31-35 Rue de la Fédération, Paris, 75015