Japan Inc. Now Sells No Yen to Invest Abroad

Earnings on Japan’s foreign direct investment (FDI) reached 103% of new FDI in 2022–25. With dividends and retained earnings counted together, Japan Inc. now needs to sell little yen to invest abroad.

[by OKUBO Takuji]

Key takeaways

  • Foreign affiliates now earn about as much as Japan invests abroad each year. Reinvested earnings, dividends and interest together reached 103% of new outward FDI in 2022–25, against 48% in 1996–2000.
  • Dividends from foreign affiliates account for a growing share of Japanese corporate profit. We estimate that foreign affiliates contributed 13.4% of Japan Inc.’s earnings in FY2025, up from 1.7% in FY1996.
  • Corporate investment abroad now involves little net yen selling. After dividends and interest paid home, the estimated outflow has been close to zero since 2022, down from about ¥5 trillion a year, or about 1% of GDP, on average in the 2010s.

Japan’s FDI stock now earns 103% of new investment

It is often said that Japan’s ageing population and slow growth give its companies too few investment opportunities at home. A Japanese government report in 2024 included the following passages.

“Japan’s ageing and shrinking population depresses expected demand at home. Expected returns remain higher abroad, so Japanese companies have accelerated outward direct investment” (my translation). — MATSUBAYASHI Yōichi [松林 洋一], MOF PRI, chapter 8, p.136.

“Companies invested abroad because they saw no promising investments in Japan; they are unlikely to bring back every return. On a cash-flow basis, the external balance is in deficit and is one factor behind the weak yen” (my translation). — KARAKAMA Daisuke [唐鎌 大輔], MOF PRI, chapter 10, pp.178 and 175.

However, my review of recent data shows that while their premise of low growth prospects in Japan is probably still right, the direct investment Japan has accumulated abroad has reached a level where it earns enough to cover Japan’s new investment abroad. This changes the exchange-rate implication even if Japan keeps investing abroad.

As chart 1 shows, earnings on the accumulated investment stock rose from 48% of new outward FDI in 1996–2000 to 103% in 2022–25.

Chart 1
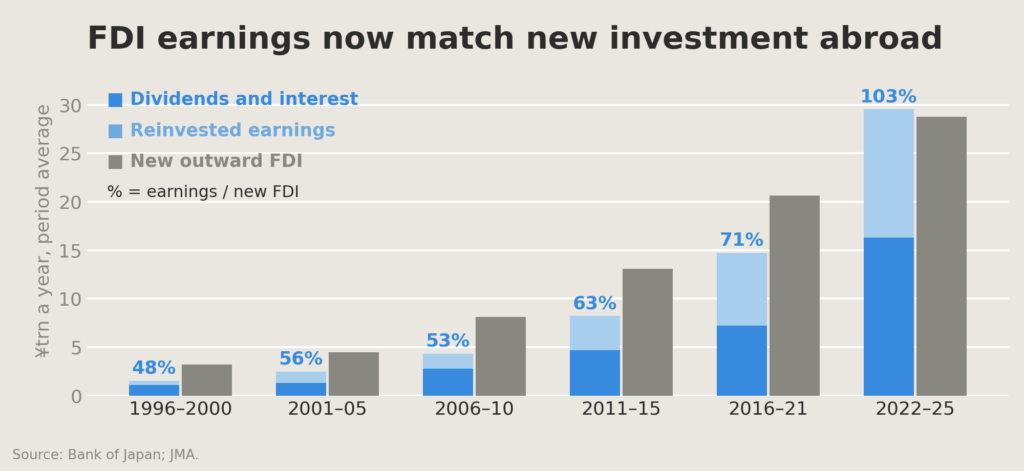
Overseas affiliates pay interest and dividends to their parent companies in Japan. Those dividends have become a sizable part of corporate Japan’s income: we estimate that they made up 13.4% of Japanese corporate profit in FY2025, up from 1.7% in FY1996.

When foreign affiliates retain their earnings on their balance sheets, Japan’s balance of payments statistics record them as FDI from Japan, even though no money crosses the border. While the companies receiving FDI dividends and the companies paying for new FDI are not necessarily the same, Japan Inc. as a whole is now financing its FDI almost entirely from the earnings of its overseas affiliates. At the current level of FDI, little new yen needs to be converted into foreign currencies as Japan goes about investing abroad.

In the rest of this report, I explain how foreign direct investment by Japanese companies evolved, and its near-term outlook. This report is the third in a series on the yen repatriation theme that I have published over the past few weeks, following “Yen Repatriation Starts with the Whale”, on capital flows through Japan’s national pension funds, and “Mrs Watanabe No More”, on Japanese households’ assets invested abroad.

A strong yen helped drive Japan’s first outward FDI boom

Japan’s outward investment was heavily restricted after WWII, requiring case-by-case permission from the government. Approvals became more and more automatic over the years until outward investment became “free in principle” in 1980. Trade friction with the US-led Japanese carmakers to restrain their exports from 1981, pushing them to build factories abroad. The rapid appreciation of the yen was also a factor. The yen strengthened from ¥242 per dollar before the Plaza Accord in September 1985 to ¥121 by the end of 1987. Japanese producers had to move lower value-added work abroad. The strong yen also gave Japanese financial institutions sizable purchasing power for a while, until the stock and property bubbles burst in 1990 and 1991.

All of these factors contributed to a rapid increase in outward FDI through the 1980s and 1990s (chart 2).

Chart 2

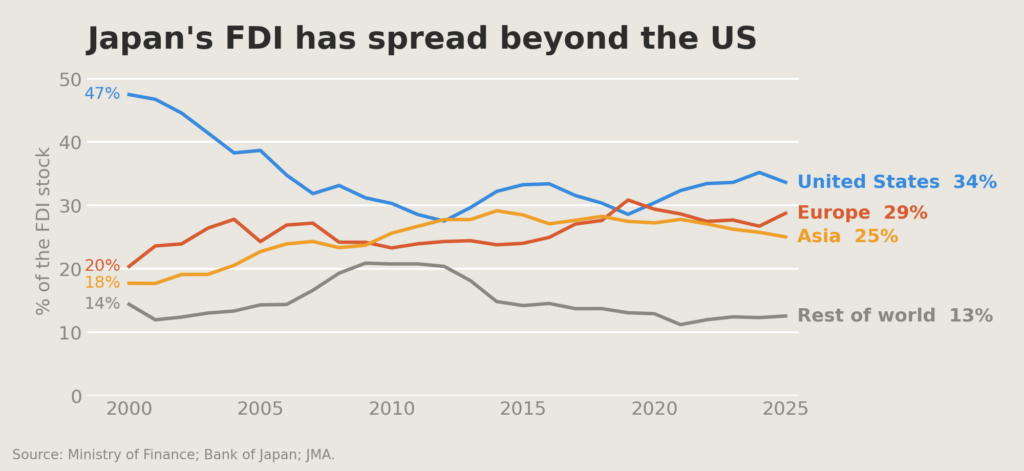
Even after the bubble burst, the strong yen kept pushing manufacturers to move abroad. In 2005, manufacturers accounted for 60% of the FDI stock. As Japanese manufacturers expanded their supply chains abroad, Asia’s share of outward FDI rose from about 12% in FY1986–90 to 19% in FY1995–99, and Asia held 23% of the FDI stock by 2005 (chart 3).

Chart 3
Japan’s outward FDI stock rose to 56% of GDP

The next phase was sustained by a different pressure. With weak growth and low interest rates at home, Japan Inc. kept investing abroad, across a broader range of industries. Between 1995 and 2025, the stock of FDI rose from 9% of Japan’s GDP to 58% (chart 4). In 2025, it is as large as about 38% of the private sector’s domestic fixed capital, on our estimate.

Chart 4

By industry composition and by destination compositions changed over time. Manufacturing’s share of the FDI stock had fallen to 37% by 2025, giving Japan’s FDI more breadth. By destination, we are seeing a revival of FDI toward the United States. It accounted for 34% of the stock in 2025, Europe 29% and Asia 25% (see earlier chart 3).
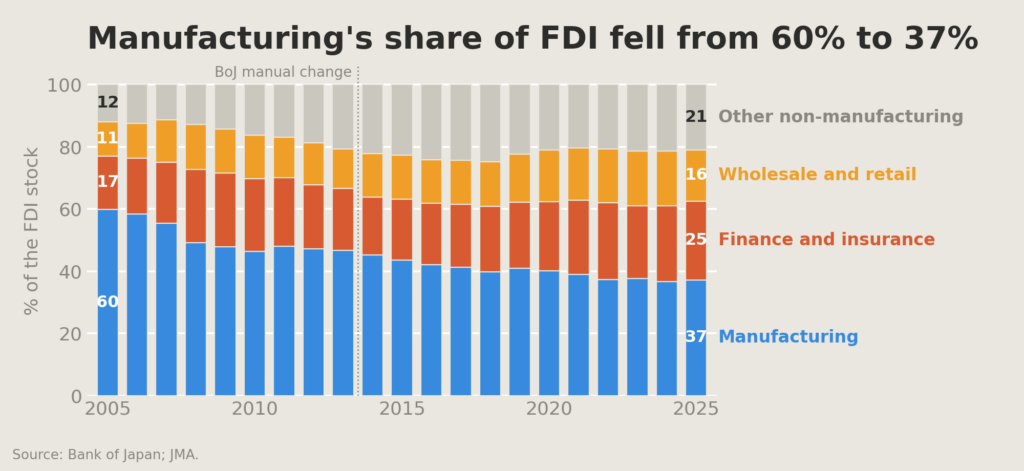
Thus, after decades of overseas investment, Japan’s FDI stock is now large enough that its earnings are sufficient to finance new investment abroad, at least for now. In the next section, I consider whether this will continue, and in particular whether Japanese companies may bring an even larger share of their overseas earnings back to Japan, given the weak yen, higher borrowing costs in yen and possibly better investment opportunities at home.

The weak yen has slowed offshoring, not reversed it

The real depreciation of the yen over the past 15 years made production in Japan more competitive. There is some evidence that manufacturers are considering bringing production back to Japan. The 2023 manufacturing white paper found more firms shifting production back from China than moving there, and they named the weak yen as one reason. We see some signs of reshoring. Japanese manufacturers’ overseas production ratio rose from 18.0% in FY2011 to 27.2% in FY2023, but it may have started to decline or at least stabilize. The ratio fell to 26.7% in FY2024. A Cabinet Office survey of listed manufacturers puts the ratio at 24.5% in FY2025, and their plan for FY2030 is broadly unchanged at 24.7%. The weak yen seems to have stabilized the wave of offshoring, but I see no firm evidence of a move back onshore yet.

Domestic investment has grown slowly despite the weak yen

There are tentative signs that domestic capital spending is starting to grow again. For three decades it grew at a very low speed. In real terms, private business investment rose only 26% between FY1997 and FY2025, less than 1% a year. In comparison, capital spending grew by about 4% a year on average in the United States. In my view, a weak currency is only one of the factors manufacturers weigh in designing their global production chains. The weak yen makes production in Japan competitive today, but they have also seen the exchange rate swing violently within short periods. Japan also has a shrinking population problem. It started to address it by opening a door to immigration, but the door is only tentatively open. Overall, my view is that the weak yen alone is unlikely to give Japan Inc. sufficient incentive to bring its capital back to Japan and to the yen.

Economic security is bringing some production home

The government is pushing harder than the currency, mostly in the name of economic security, even before the Takaichi government came along. The government currently has a ¥250 trillion domestic investment target for FY2040 and named AI and semiconductors among its 17 strategic fields. Semiconductors are where the money has gone furthest. In November 2024, under the Ishiba government, Japan committed more than ¥10 trillion of public support to AI and semiconductors by FY2030, aiming to draw more than ¥50 trillion of public and private investment over ten years. Japan managed to lure a TSMC plant to Japan, backed by a sizable subsidy. Rapidus, a government-supported Japanese semiconductor maker, has received a sizable subsidy and is building a factory in Hokkaido. Japan’s production of integrated circuits and discrete semiconductors rose from ¥2.7 trillion in 2019 to ¥4.1 trillion in 2025.

Under the name of economic security, the Japanese government is promoting other industries such as batteries, shipbuilding and pharmaceuticals. Defence spending adds to the push. Japan’s defence budget rose from about ¥5 trillion in FY2022 to ¥9.0 trillion in FY2026. Some defence contractors, such as Mitsubishi Heavy Industries, have doubled their defence revenue.

Japan’s industrial-policy record gives reason for caution

The Japanese government and the Ministry of Economy, Trade and Industry (METI), the key agency behind Japan’s industry policy, may claim some expertise in their industrial policies. Empirical studies in the past paint a poor track record, though. Rapidus, the most ambitious semiconductor project, has had no independent cost-benefit assessment (Negrine et al., 2025). While defence and economic security-driven policies have a different logic, I doubt that these industrial policies will succeed in bringing large-scale manufacturing investment back to Japan so long as macro factors such as Japan’s demography remain unfavourable.

FDI no longer appears to drive yen weakness

The weak yen and non-economic geopolitical factors do point to a halt in Japan’s four-decade offshoring trend, although it is a stabilization, rather than an economy-wide reversal of past offshoring. Japan Inc. will continue to invest more abroad, rather than within its borders. Given the sizable growth in the stock of cumulative FDI, Japan Inc. no longer needs to convert yen into overseas currency to keep investing abroad though. Net of dividends and interest paid home, Japan’s FDI sold about ¥5 trillion of yen a year, or about 1% of GDP, on average in the 2010s; since 2022 the net flow has been close to zero. There is also an interesting development in an effort to allow more share-exchange based M&A for cross-border deals that will further reduce the need for Japanese companies to spend their yen to purchase overseas assets. In my view, Japan Inc.’s FDI is no longer a factor to drive the yen weaker.

References

Economics-Watching: Where Could Reshoring Manufacturers Find Workers?

[from the Federal Reserve Bank of Cleveland, 9 October, 2025]

by Stephan D. Whitaker, Senior Policy Economist

The United States has lost millions of manufacturing jobs in recent decades, but a variety of policies have been enacted to incentivize the creation of manufacturing jobs in America. This District Data Brief analyzes where manufacturers might find US workers to fill these roles.

Introduction

The announcement of new tariffs this year has reignited the discussion of whether the United States can expand its manufacturing employment by millions of workers. Reversing decades of manufacturing job losses is one explicit goal of the new higher tariffs. This District Data Brief presents measures of employment and demographics as context around the current and potential employment in US manufacturing. Raising manufacturing employment by 4 to 6 million workers would constitute a large increase relative to current levels. However, an increase of this scale would not be large relative to the global growth of manufacturing employment in recent decades, the current US labor force size, or the number of US adults not engaged in high-paying work.

With different priorities and approaches, policymakers have spent much of the past decade addressing issues related to the loss or absence of manufacturing in the United States. For example, America’s dependence on imported manufactured goods was highlighted at the beginning of the COVID-19 pandemic as supply chain disruptions led to shortages of medical equipment, pharmaceuticals, microchips, and other products. The CHIPS and Science Act and the Inflation Reduction Act featured tax breaks and subsidies to expand US manufacturing capacity for semiconductors, electric vehicles, and renewable energy equipment.

At the same time, economists have been documenting the loss of work opportunities and earning power by workers without college degrees as manufacturing employment has declined. In 2013, David Autor, David Dorn, and Gordon Hanson published a study that estimated the labor market impacts resulting from increased trade competition following China’s entrance into the World Trade Organization, an effect often referred to as the “China shock.” Dozens of studies have since used the regional variation in job and income losses caused by the China shock to measure the adverse impacts of job displacement on family structures, crime, health, and other social indicators. Some supporters of industrial subsidies and higher tariffs have expressed the hope that these dynamics can be put into reverse.

Read the full article [archived PDF].

Technology-Watching: Quantum Microchips Connected in Record-Breaking World First

[from UK Research and Innovation]

Researchers in the UK have successfully transferred data between quantum microchips for the first time.

This helps overcome a key obstacle to building a commercial quantum computer.

The milestone achieved by a team from the University of Sussex and Brighton-based quantum computer developer Universal Quantum, allows chips to be linked like a jigsaw.

On track to useful quantum computers

It means that many more qubits, the basic calculating unit, can be joined together than is possible on a single microchip. This will make a more powerful quantum computer possible.

The project, which has been backed by the Engineering and Physical Sciences Research Council (EPSRC), has also broken the world record for quantum connection speed and accuracy.

The scaling of qubit numbers from the current level of around 100 qubits to nearer 1 million is central to creating a quantum processor that can make useful calculations.

The significant achievement is based on a technical blueprint for creating a large-scale quantum computer, which was first published in 2017 with funding from EPSRC.

Within the blueprint was the ground-breaking concept successfully demonstrated with this research of linking quantum computing modules with electrical fields.

Unlocking UK potential

The UK is a leader in the global race to develop useful quantum computers, which represent a step-change in computing power.

Their development may help solve pressing challenges from drug discovery to energy-efficient fertilizer production. But their impact is expected to sweep across the economy, transforming most sectors and all our lives.

Potential to scale up

Winfried Hensinger, Professor of Quantum Technologies at the University of Sussex and Chief Scientist and co-founder at Universal Quantum said:

As quantum computers grow, we will eventually be constrained by the size of the microchip, which limits the number of quantum bits such a chip can accommodate.

In demonstrating that we can connect 2 quantum computing chips, a bit like a jigsaw puzzle, and, crucially, that it works so well, we unlock the potential to scale up by connecting hundreds or even thousands of quantum computing microchips.

Speed and precision

The researchers were successful in transporting the qubits using electrical fields with a 99.999993% success rate and a connection rate of 2424 transfers per second. Both numbers are world records.

Dr. Kedar Pandya, Director of Cross-Council Programmes at EPSRC, said:

This significant milestone is evidence of how EPSRC funded science is seeding the commercial future for quantum computing in the UK.

The potential for complex technologies, like quantum, to transform our lives and create economic value widely relies on visionary early-stage investment in academic research.

We deliver that crucial building block and are delighted that the University of Sussex and its spin-out company, Universal Quantum, are demonstrating the strength it supports.

Institute of Physics award winner

Universal Quantum has been awarded €67 million from the German Aerospace Center to build 2 quantum computers.

The University of Sussex spin-out was also recently named as one of the 2022 Institute of Physics award winners in the business start-up category.

India and the Russia-Ukraine War: The Paradox of Military Dependence, Traditional Loyalty and Strategic Autonomy

[from India in Transition, published by the Center for the Advanced Study of India (CASI) of the University of Pennsylvania, by Arndt Michael]

India, long-established as the world’s most populous democracy, has been quite instrumental over the years in assisting various countries dealing with democratic struggles. This support has included a blend of bilateral and multilateral initiatives, and especially economic development projects. Yet, India’s recent attitude toward the Russian attack on Ukraine and its concomitant behavior in the United Nations Security Council (as a non-permanent member) seems to contradict its support of democracy. By abstaining, rather than explicitly voting in favor of UN resolutions condemning Russian aggression at the beginning of the war, India angered several UN member-countries.

In order to substantiate its abstention from voting, India felt compelled to issue a so-called “Explanation of Vote” (EoV). In it, India asked for a “return to the path of diplomacy” and an immediate cessation of “violence and hostilities.” Crucially, India stated in the EoV that “the contemporary global order has been built on the UN Charter, international law, and respect for the sovereignty and territorial integrity of states…all member states need to honor these principles in finding a constructive way forward. Dialogue is the only answer to settling differences and disputes, however daunting that may appear at this moment.” 

While these statements and the call for dialogue are in accordance with India’s professed stance toward the relevance and objectives enshrined in the UN Charter, the discrepancy between rhetoric and practice is still conspicuous. At first glance, a “good” relationship with Russia seems to be more significant than the expectations of the world-community as represented in the United Nations. And, more importantly, by abstaining, India seemingly violated one of its central foreign and strategic policies: to always strive for strategic autonomy.

However, from a strategic perspective, India is precisely replicating what it did when the Soviet Union invaded Afghanistan. For India, its own national security is at stake, as well as its current and future geostrategic influence in Asia and the world. The military dependence that currently exists between India and Russia is nothing short of gigantic and has created a dangerous conundrum. Since the “Indo–Soviet Treaty of Peace, Friendship and Cooperation” was signed in 1971, defense agreements and long-term supply contracts have been in place. And while India and Russia have shared a strategic relationship since October 2000, this was upgraded in December 2020 to a “Special and Privileged Strategic Partnership.” 

Although there was a marked reduction of Russian imports in past years, official data from the Stockholm International Peace Research Institute (SIPRI) reveal that between 1996-2015, the Russian proportion of Indian military imports was almost 70 percent, and between 2016-20 it still hovered around 49 percent. In fact, 70 percent of all Indian military equipment currently in use has been directly produced in Russia, was manufactured with the majority of parts coming from Russia, or licensed by Russia. In 2020, this included the majority of Indian tanks, the only aircraft carrier (the INS Vikramaditya, a heavily modified Kiev-class aircraft carrier) with all of its combat aircraft MiG-29s, six frigates, four destroyers and the only nuclear-powered submarine. Additionally, eight out of fourteen Indian Navy submarines belong to the Russian Kilo-class. The Indian Air Force flies Sukhoi Su-30MKIs and Mil Mi-17s, which, respectively, constitute the largest share of the combat aircraft and utility helicopters, in addition to Russian tanker planes. India also just recently purchased the S-400 missile system.

Even though India has begun to reorient itself militarily toward other countries—the U.S., Israel, France and Italy—and has substituted foreign imports by slowly developing its own capabilities, a large number of new Indo-Russian projects are in the conceptual or implementation stages. In December 2021, in the frame of the so-called “2+2 Dialogue” (foreign and defense ministers), India and Russia began a new phase in their military–technological cooperation. Incidentally, India has used this very format for furthering cooperation in strategic, security and intelligence issues with four of its key strategic partners: Australia, the U.S., Japan and the newly added Russia. Russia and India agreed upon a further deepening of mutual military relations for ten years (until 2031). What is new is that next to the traditional purchase of Russian weapons systems, many common research projects and the development of new weapons systems—with their production taking place equally in both countries—have been agreed upon. This production includes new frigates, helicopters, submarines, cruise missiles and even Kalashnikovs. 

The depth of this mutual engagement, and especially India’s dependence, highlights a huge dilemma that might not only have drastic strategic consequences, but also long-lasting regional repercussions. The worldwide sanctions issued against Russia aim at the Russian economy and military. When it comes to the procurement of such crucial components as microchips or airline parts, Russia is soon expected to face shortages, essentially crippling its capacity to repair, construct, or have spare parts available (let alone construct new equipment). Unless other countries, such as China, circumvent international sanctions and step-in, the expected Russian inability to take care of its own military will have a spill-over effect. Russia is unlikely to be able to fulfill its contractual obligations toward India, and the lack of spare parts also has the potential to cripple India’s own military with regards to the Russian weapons equipment. The procurement agreements and common projects are, hence, all in jeopardy and India, now more than ever, depends on Russian goodwill. 

Next to military dependence, there are other concomitant effects in the economic and political sphere that influence Indian voting behavior. The worldwide sanctions have already led to dramatic increases in oil and gas prices, with India relying on imports of up to 80 percent. India will, therefore, have to pay much more for such crucial imports. Military imports from other countries aimed at substituting Russian equipment will also be much more expensive. All of this deals the Indian economy another blow—an economy that has been especially hit hard by the COVID-19 pandemic. And politically, Indian hegemony in South Asia has been markedly under pressure, in no small part because of the China–Pakistan axis. In the eyes of India, this axis poses a serious threat to an already highly volatile Indo–Pakistan relationship. In addition, the Indo–China relationship reached a new low in May 2020 when Chinese infrastructure projects along the Himalayan borderlands led to fighting and the killing of soldiers. In addition, the Chinese claims to the South China Sea are categorically disputed by India. Chinese overtures toward Sri Lanka, the Maldives, and especially Pakistan in the frame of the Road Initiative are also regarded with growing discontent, as India claims that China is following a policy of encircling India.

In its 75th year of independence, India is following a classic realpolitik in trying not to alienate Russia while pledging rhetorical support for Ukraine. The contradictory consequence is that Russia has now offered more discounted oil, gas, and investments, while at the same time, the UK has suggested its military relationship with India could be upgraded—and has offered weapons made in the UK. For the Indian political establishment, India cannot forgo Russian support, militarily or as a producer of cheap oil and gas. Going forward, India’s military will need to protect its national security and project Indian influence and power well beyond its borders.

Arndt Michael is a Lecturer in the Department of Political Science, University of Freiburg (Germany), author of the multi-award-winning book India’s Foreign Policy and Regional Multilateralism (Palgrave Macmillan, 2013), and co-editor of Indien Verstehen (Understanding India, Springer, 2016). His articles have been published in Asian Security, Cambridge Review of International Affairs, Harvard Asia Quarterly, India Quarterly and India Review.

New Ultrathin Capacitor Could Enable Energy-Efficient Microchips

Scientists turn century-old material into a thin film for next-gen memory and logic devices

[from Berkeley Lab, by Rachel Berkowitz]

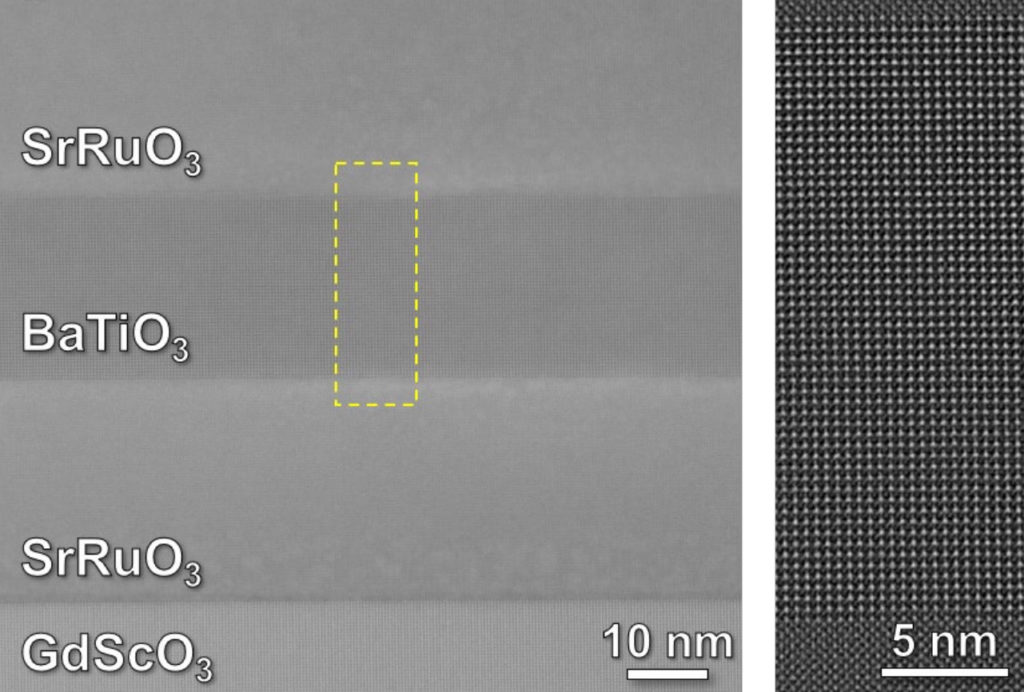
Electron microscope images show the precise atom-by-atom structure of a barium titanate (BaTiO3) thin film sandwiched between layers of strontium ruthenate (SrRuO3) metal to make a tiny capacitor. (Credit: Lane Martin/Berkeley Lab)

The silicon-based computer chips that power our modern devices require vast amounts of energy to operate. Despite ever-improving computing efficiency, information technology is projected to consume around 25% of all primary energy produced by 2030. Researchers in the microelectronics and materials sciences communities are seeking ways to sustainably manage the global need for computing power.

The holy grail for reducing this digital demand is to develop microelectronics that operate at much lower voltages, which would require less energy and is a primary goal of efforts to move beyond today’s state-of-the-art CMOS (complementary metal–oxide semiconductor) devices.

Non-silicon materials with enticing properties for memory and logic devices exist; but their common bulk form still requires large voltages to manipulate, making them incompatible with modern electronics. Designing thin-film alternatives that not only perform well at low operating voltages but can also be packed into microelectronic devices remains a challenge.

Now, a team of researchers at Lawrence Berkeley National Laboratory (Berkeley Lab) and UC Berkeley have identified one energy-efficient route—by synthesizing a thin-layer version of a well-known material whose properties are exactly what’s needed for next-generation devices.

First discovered more than 80 years ago, barium titanate (BaTiO3) found use in various capacitors for electronic circuits, ultrasonic generators, transducers, and even sonar.

Crystals of the material respond quickly to a small electric field, flip-flopping the orientation of the charged atoms that make up the material in a reversible but permanent manner even if the applied field is removed. This provides a way to switch between the proverbial “0” and “1” states in logic and memory storage devices—but still requires voltages larger than 1,000 millivolts (mV) for doing so.

Seeking to harness these properties for use in microchips, the Berkeley Lab-led team developed a pathway for creating films of BaTiO3 just 25 nanometers thin—less than a thousandth of a human hair’s width—whose orientation of charged atoms, or polarization, switches as quickly and efficiently as in the bulk version.

“We’ve known about BaTiO3 for the better part of a century and we’ve known how to make thin films of this material for over 40 years. But until now, nobody could make a film that could get close to the structure or performance that could be achieved in bulk,” said Lane Martin, a faculty scientist in the Materials Sciences Division (MSD) at Berkeley Lab and professor of materials science and engineering at UC Berkeley who led the work.

Historically, synthesis attempts have resulted in films that contain higher concentrations of “defects”—points where the structure differs from an idealized version of the material—as compared to bulk versions. Such a high concentration of defects negatively impacts the performance of thin films. Martin and colleagues developed an approach to growing the films that limits those defects. The findings were published in the journal Nature Materials.

To understand what it takes to produce the best, low-defect BaTiO3 thin films, the researchers turned to a process called pulsed-laser deposition. Firing a powerful beam of an ultraviolet laser light onto a ceramic target of BaTiO3 causes the material to transform into a plasma, which then transmits atoms from the target onto a surface to grow the film. “It’s a versatile tool where we can tweak a lot of knobs in the film’s growth and see which are most important for controlling the properties,” said Martin.

Martin and his colleagues showed that their method could achieve precise control over the deposited film’s structure, chemistry, thickness, and interfaces with metal electrodes. By chopping each deposited sample in half and looking at its structure atom by atom using tools at the National Center for Electron Microscopy at Berkeley Lab’s Molecular Foundry, the researchers revealed a version that precisely mimicked an extremely thin slice of the bulk.

“It’s fun to think that we can take these classic materials that we thought we knew everything about, and flip them on their head with new approaches to making and characterizing them,” said Martin.

Finally, by placing a film of BaTiO3 in between two metal layers, Martin and his team created tiny capacitors—the electronic components that rapidly store and release energy in a circuit. Applying voltages of 100 mV or less and measuring the current that emerges showed that the film’s polarization switched within two billionths of a second and could potentially be faster—competitive with what it takes for today’s computers to access memory or perform calculations.

The work follows the bigger goal of creating materials with small switching voltages, and examining how interfaces with the metal components necessary for devices impact such materials. “This is a good early victory in our pursuit of low-power electronics that go beyond what is possible with silicon-based electronics today,” said Martin.

“Unlike our new devices, the capacitors used in chips today don’t hold their data unless you keep applying a voltage,” said Martin. And current technologies generally work at 500 to 600 mV, while a thin film version could work at 50 to 100 mV or less. Together, these measurements demonstrate a successful optimization of voltage and polarization robustness—which tend to be a trade-off, especially in thin materials.

Next, the team plans to shrink the material down even thinner to make it compatible with real devices in computers and study how it behaves at those tiny dimensions. At the same time, they will work with collaborators at companies such as Intel Corp. to test the feasibility in first-generation electronic devices. “If you could make each logic operation in a computer a million times more efficient, think how much energy you save. That’s why we’re doing this,” said Martin.

This research was supported by the U.S. Department of Energy (DOE) Office of Science. The Molecular Foundry is a DOE Office of Science user facility at Berkeley Lab.