Henry Huiyao Wang: A New Compact for China and Europe

CCG President outlines opportunities for China and Europe to deepen cooperation in trade, investment, climate action, and global governance.

[from the Center for China & Globalization, 7 November 2026]

Henry Huiyao Wang [王辉耀], Founder and President of the Center for China & Globalization (CCG), has published an article titled “A New Compact for China and Europe” in the Autumn 2026 issue (No. 36) of Horizons, a journal published by the Center for International Relations and Sustainable Development (CIRSD).
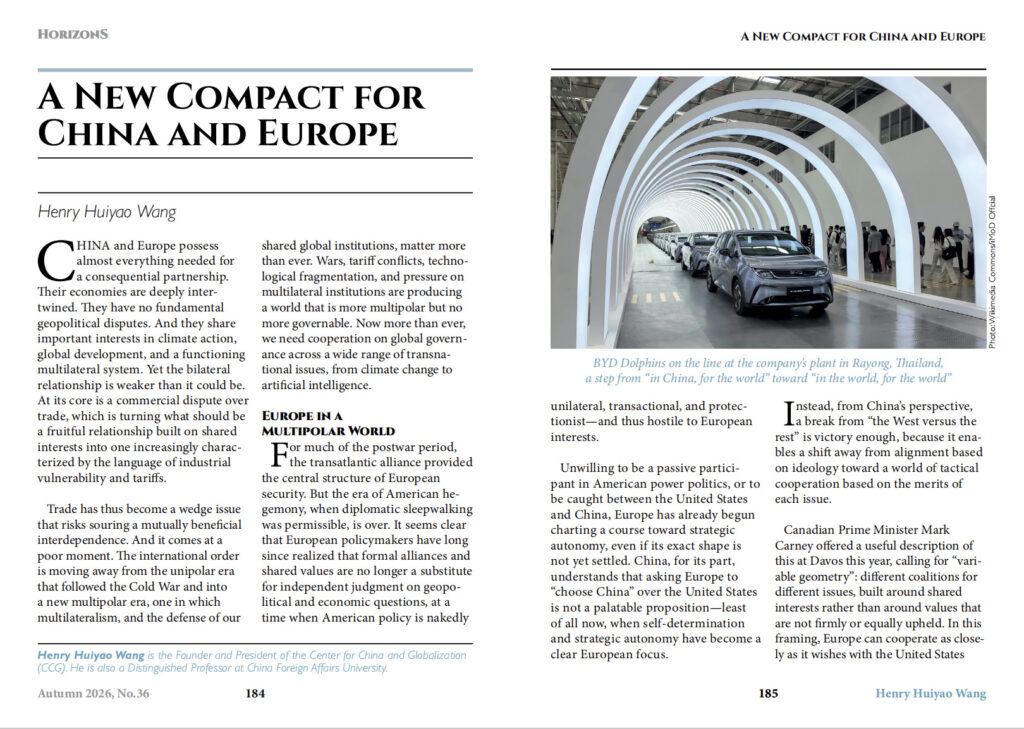
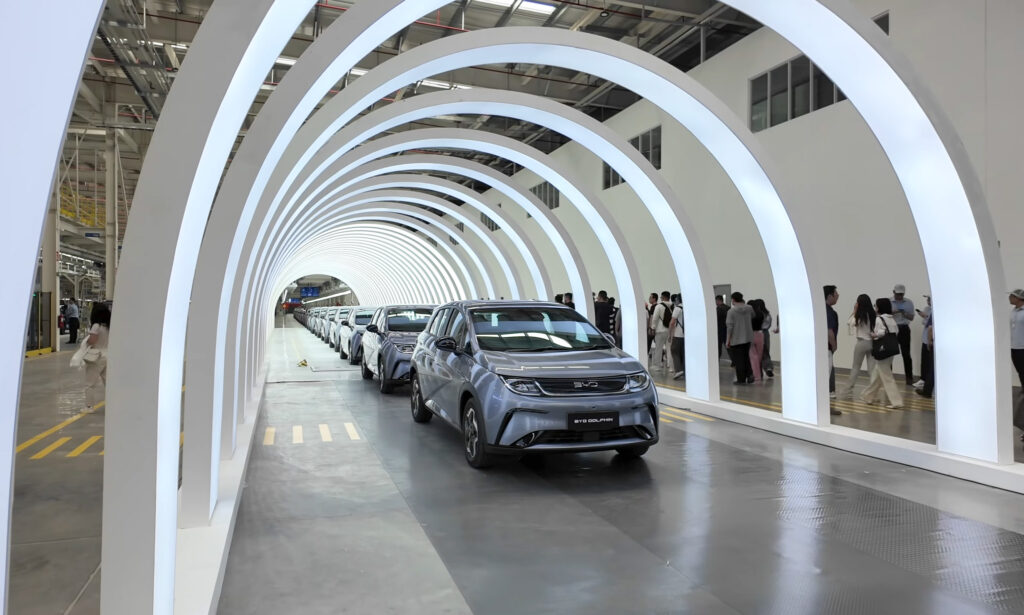
BYD Dolphins on the line at the company’s plant in Rayong, Thailand, a step from “in China, for the world” toward “in the world, for the world”
Wikimedia Commons/iMoD Official

China and Europe possess almost everything needed for a consequential partnership. Their economies are deeply intertwined. They have no fundamental geopolitical disputes. And they share important interests in climate action, global development, and a functioning multilateral system. Yet the bilateral relationship is weaker than it could be. At its core is a commercial dispute over trade, which is turning what should be a fruitful relationship built on shared interests into one increasingly characterized by the language of industrial vulnerability and tariffs.

Trade has thus become a wedge issue that risks souring a mutually beneficial interdependence. And it comes at a poor moment. The international order is moving away from the unipolar era that followed the Cold War and into a new multipolar era, one in which multilateralism, and the defense of our shared global institutions, matter more than ever. Wars, tariff conflicts, technological fragmentation, and pressure on multilateral institutions are producing a world that is more multipolar but no more governable. Now more than ever, we need cooperation on global governance across a wide range of transnational issues, from climate change to artificial intelligence.

Europe in a Multipolar World

For much of the postwar period, the transatlantic alliance provided the central structure of European security. But the era of American hegemony, when diplomatic sleepwalking was permissible, is over. It seems clear that European policymakers have long since realized that formal alliances and shared values are no longer a substitute for independent judgment on geopolitical and economic questions, at a time when American policy is nakedly unilateral, transactional, and protectionist—and thus hostile to European interests.

Unwilling to be a passive participant in American power politics, or to be caught between the United States and China, Europe has already begun charting a course toward strategic autonomy, even if its exact shape is not yet settled. China, for its part, understands that asking Europe to “choose China” over the United States is not a palatable proposition—least of all now, when self-determination and strategic autonomy have become a clear European focus.

Instead, from China’s perspective, a break from “the West versus the rest” is victory enough, because it enables a shift away from alignment based on ideology toward a world of tactical cooperation based on the merits of each issue.

Canadian Prime Minister Mark Carney offered a useful description of this at Davos this year, calling for “variable geometry”: different coalitions for different issues, built around shared interests rather than around values that are not firmly or equally upheld. In this framing, Europe can cooperate as closely as it wishes with the United States on defense, while still finding common cause with China on climate and trade reform, or with India on development. Such flexibility is increasingly the default in our plural world.

A cohesive Europe able to act independently is preferable to a divided continent whose China policy is increasingly shaped elsewhere. But that also means that policymakers in China must address European fears if they are to benefit from engagement and cooperation on shared interests.

The Changing Bargain

The core anxiety facing Europe, and the one undermining a merits-based relationship, is that the old, unspoken economic bargain—European technology and premium manufacturing in exchange for Chinese consumer goods and lower-cost production—is giving way to a more competitive relationship.

China now possesses broad industrial ecosystems, world-class infrastructure, skilled engineering talent, and the capacity for fast commercialization at scale. It no longer competes on wages alone. In electric vehicles, batteries, solar energy, machinery, telecommunications equipment, and, increasingly, advanced digital applications, Chinese firms can combine cost, speed, and technological capability.

But let us not get carried away with catastrophizing. The shared economic foundation between China and the EU remains immense. In 2025, two-way trade in goods and services exceeded €880 billion. Europe imported more than €570 billion in goods from China and exported about €200 billion, producing a large bilateral goods deficit. Yet this figure should be interpreted carefully. The European Union still recorded an overall goods surplus of approximately €128 billion in 2025, as well as a substantial current-account surplus. Nor are all imports finished products: Eurostat data shows that 57 percent of all extra-EU goods imports in 2025 were intermediate products, meaning that much of what Europe imports feeds into value-added production chains from which Europe itself benefits. Europe’s difficulty is that, while its industry remains broadly profitable, certain critical sectors are already under pressure, and the trend seems unlikely to reverse suddenly in favor of European manufacturing.

Europe is not facing this crisis in a vacuum, either. It is compounded by high energy costs, aging populations, fragmented capital markets, and chronic underinvestment. The result is a genuine fear of deindustrialization, with the attendant loss of skilled employment, supplier networks, technological capacity, and social cohesion. This worry is especially potent in the major European economies with large export-oriented manufacturing sectors, such as Germany, France, Italy, and Spain, and it makes the debate over “overcapacity” deeply politically charged.

While the imbalance is a product of industrial excellence, it can also be attributed to weak domestic demand in China. Household consumption there remains around 40 percent of GDP, while families save heavily out of concern over housing, education, health care, and retirement. The 2025 consumption action plan addressed wages, pensions, health care, childcare, paid leave, and benefits for migrant and flexible workers, and China’s first five-year plan devoted specifically to consumption subsequently set a goal of approximately 60 trillion yuan in retail sales by 2030. But it is far too early to call the effort complete. Although per capita disposable income rose by 5 percent and consumption expenditure by 4.4 percent in 2025, the first half of 2026 was weaker, and overall consumption still lags behind where it should be. Stronger pensions, health care, unemployment insurance, childcare, and portable benefits for migrant workers will help reduce precautionary saving, and greater access for foreign goods and services would ensure that stronger Chinese demand creates opportunities for European producers. That transformation, however, is not yet complete.

Europe, for its part, should recognize that competitive success is not in itself an unfair subsidy. The International Energy Agency estimates that producing a battery-electric vehicle costs more than 30 percent less in China than in advanced economies, with only about one-third of the gap attributable to the battery; a similar cost gap exists for conventional vehicles. China’s earlier industrial policies undoubtedly helped establish this ecosystem, but important forms of direct support, including national EV purchase subsidies, have already been phased out.

Rhodium Group estimates that BYD enjoys a cost advantage of approximately $4,700 per vehicle over Tesla’s operations in China, of which grants account for only about $292, while vertical integration and lower research, administrative, and supplier costs explain at least three-quarters of the difference. BYD produces roughly 70 percent of its components in-house, including its batteries. Europe should investigate market-distorting support and is right to insist on transparency, but it should not define the ecosystem, technology, and efficiencies China has built as unfair.

Nor is China’s automobile sector insulated from competition. The number of Chinese electric-vehicle makers was reported at 487 in 2018; by 2025, consolidation had reduced the market to approximately 129 brands produced by about 50 manufacturers, and only 10 to 15 are expected to be profitable by 2030. China exported approximately 5.86 million of the more than 31 million vehicles it sold in 2024, meaning that the large majority were still absorbed at home. By comparison, Volkswagen delivered 9.03 million vehicles worldwide but only 1.12 million in Germany, while Toyota and Lexus sold 10.16 million worldwide and 1.44 million in Japan. Airbus, likewise, sells approximately 68 percent of its aircraft outside Europe. Producing for global markets is accepted as normal when established European or Japanese companies do it; it should not automatically become illegitimate when Chinese firms do the same.

China’s textile industry offers a further precedent. Even as wages rose and some production moved to Vietnam, Bangladesh, and elsewhere, China retained 37 percent of global textile exports and 34 percent of clothing exports in 2017, because supplier clusters, infrastructure, skills, and continual upgrading proved more durable than low labor costs alone.

Beyond economic competition, clearer rules are urgently needed on the securitization of critical industries. The dispute over Nexperia—the Chinese-owned semiconductor company placed under Dutch government control in 2025—rattled supply chains and deepened concern in China about investing abroad. Either the company should not have been sold in the first place, or a clearer regulatory environment might have avoided a quasi-nationalization that rapidly internationalized a corporate dispute, and that still hangs over the mutual investment relationship today.

Likewise, proposals for a European instrument modeled on the United States’ Section 301 powers may offer political reassurance, but Section 301 is a blunt unilateral instrument designed to authorize retaliation. Europe would be better served by an explicitly transitional mechanism. Where an import surge threatens to destabilize domestic markets, temporary safeguards can provide time for adjustment, but they should be evidence-based, reviewable, and subject to firm sunset clauses. Their purpose should be to facilitate adaptation and negotiation, not to turn emergency protection into a permanent wall.

An Industrial Compact for Shared Competitiveness

When I visited Jean Monnet’s house outside Paris this summer, I was reminded of the method that helped build modern Europe: begin with concrete achievements that create the basis for solidarity. That method matters especially now, when trade has become a wedge issue and trust and trade cannot be separated.

We must therefore build a new industrial compact: one that aligns Chinese industrial capacity with Europe’s need for investment, innovation, and employment, and that enables China and Europe to stand together in support of a world of free, fair, and open trade.

First, China should follow through on its ongoing shift from an export– and investment-heavy model toward consumption-led growth. Alongside the social measures described above, this requires reducing the barriers faced by private and foreign businesses, improving market access in services and public procurement, and applying regulation more transparently. European companies should be able to compete in China with confidence that they will receive equal treatment and can protect their intellectual property.

Second, Europe needs to draw a sharper distinction between trade in products that present a genuine security risk and investment that strengthens European productive capacity. Concerns about supply-chain resilience and security in defined strategic sectors are unavoidable, given increasing regionalization. But a presumption against Chinese investment would deprive Europe of capital, technology, competition, and jobs precisely when it needs them most. Instead, Europe could openly welcome investment that meets its requirements on governance, data protection, labor standards, and environmental performance, while increasing the local economic contribution such production provides.

This openness should be anchored by a renewed Comprehensive Agreement on Investment. The agreement reached in principle in 2020 was never implemented and the relationship has changed too much for it simply to be revived unchanged. China and Europe should instead negotiate a new CAI covering market access, national treatment, subsidy transparency, technology transfer, public procurement, and enforceable dispute resolution. It should give European companies more predictable access to China, while establishing clear and consistent conditions for Chinese market access and investment in Europe, with an eye to creating employment and supplier networks there.

China has already demonstrated the value it places on market access by extending tariff-free treatment to goods from 53 African countries, and it could move explicitly to align its standards more closely with Europe’s. Europe, for its part, should reconsider its technology and investment restrictions—especially those implemented specifically to protect U.S. interests, such as the restrictions preventing China from purchasing advanced semiconductor equipment from ASML. Working examples of Chinese investment in Europe already exist. Chinese companies are investing in battery and vehicle production in Hungary, Slovakia, Spain, and Serbia, while European manufacturers—including Volkswagen, BMW, and Mercedes-Benz—continue to deepen their research, production, and partnership networks in China. These investments should not be viewed as isolated commercial transactions. They can become the architecture of a more balanced relationship.

Third, localization must mean more than final assembly. Joint ventures and investment agreements can encourage local supplier development, worker training, research partnerships, and the sharing of production know-how, while respecting intellectual-property rights. Chinese industry was once buoyed by European know-how through joint ventures; in return, European industry can now benefit from Chinese advances. The goal should be a competitive ecosystem in which both Chinese and European firms have a stake.

Fourth, any trade measures should be targeted and temporary. If an import surge threatens serious injury, safeguards can buy time for adaptation. But they should have clear evidentiary thresholds, sunset clauses, and review procedures. Protection without a productivity strategy merely postpones decline and risks marginalization, rather than allowing a dynamic industrial sector to emerge. At the same time, Europe can and should complete its own agenda: lowering energy costs, deepening the single market, mobilizing investment, scaling up innovative companies, and improving infrastructure.

Here, China can become Europe’s “fitness partner.” The phrase may sound counterintuitive at a moment of industrial anxiety, but the underlying idea is important. Healthy competition from China can push European companies and governments to confront long-delayed reforms, reduce costs, and innovate faster. Shelter from competitive pressure does not create health; competition, by contrast, can serve as a yardstick for rebuilding strength. China, meanwhile, gains more from a prosperous and capable Europe than from a weakened market increasingly hostile to Chinese commerce.

Finally, the compact should look beyond the bilateral market. Chinese and European joint ventures could look abroad, toward the product and development needs of the Global South. Joint production for Global South markets could be a starting point, moving in time toward joint financing of development and infrastructure to accelerate green industrialization in Africa, Asia, Latin America, and the Middle East.

This would represent the next stage of globalization: not simply Chinese companies “in China, for the world,” but “in the world, for the world.” It would spread productive capacity more widely, answer concerns about concentrated supply chains, and make development a shared undertaking rather than an arena for geopolitical competition.

From Commercial Trust to Strategic Cooperation

An industrial compact cannot by itself remove all political differences. But it would serve as a springboard, and a trust-building exercise, for deeper commitments and further work on shared interests.

Climate cooperation is the most obvious bridge. China’s manufacturing scale has lowered the global cost of solar panels, batteries, and electric vehicles, in a very real way underwriting the transition away from fossil fuels. At the same time, Europe is suffering under the weight of an energy crisis born of Russia’s invasion of Ukraine and, more recently, of upheavals in the Middle East around the Strait of Hormuz and the Bab al-Mandeb. A natural alignment would be for China and Europe to build a green partnership that helps wean the world off volatile fossil fuels and address the climate crisis. The exact shape of such measures is not yet defined, but using joint ventures, cooperation, and technology exchange to tap Chinese expertise and cost advantages could benefit both sides while buoying the global green transition. A tariff spiral in clean technology, by contrast, would make the energy transition slower and more expensive for everyone.

More broadly, China and Europe share an interest in conflict resolution. China has always been clear that sovereignty and territorial integrity apply universally, that nuclear escalation is unacceptable, and that a negotiated settlement must provide credible security for all parties. But it can do more to ease the concerns of a Europe that feels threatened by a Russia now in its fifth year of fighting in Ukraine. Working together, Europe and China could help provide an off-ramp, each using its leverage to bring the negotiating positions closer together. A truly durable settlement, acceptable to both sides, may eventually require security guarantees involving both European and non-European countries, and China could contribute through reconstruction, nuclear safety, and peacekeeping. The Middle East is another region where common interests are greater than current policy coordination suggests. Continued conflict and volatility around the straits have not only given fresh impetus to the transition away from fossil fuels but also created a new area of shared interest. Together, Europe and China could support a peace architecture with wider international participation.

Artificial intelligence governance is another opportunity. China and Europe approach data, platforms, and regulation differently, but both reject a future in which a handful of private companies set global rules without public accountability. They can work together on safety testing, scientific exchange, interoperable standards, and the application of AI to health, climate, and development. Agreement will be difficult, but building a shared environment for rule-making would help hedge against fragmentation in this rapidly developing field.

Finally, China and the EU have both long advocated restoring the World Trade Organization. A revitalized WTO already contains tools to address subsidies and demonstrable injury. Boeing and Airbus were both found, in WTO disputes, to have benefited from improper support, and those cases were handled through multilateral proceedings rather than through an open-ended campaign against either side’s wider industrial success. The WTO’s dispute-settlement system must now be restored, its rules on subsidies and state enterprises updated, and its development functions strengthened. The United States weakened that system by blocking appointments to the Appellate Body after adverse rulings; but China and Europe are both major beneficiaries of an open trading system, and both can press for reform.

None of this will be sustainable without renewed contact between societies. Direct flights, student exchanges, tourism, university partnerships, city-to-city links, and think-tank dialogue all have their roles to play, for they are the infrastructure of mutual understanding.

China–Europe relations will not always be perfectly aligned, and they will likely continue to contain elements of cooperation, competition, and disagreement. But together, we can put to rest the prospect of weaponized interdependence and move instead toward win-win interdependence.

Europe does not need to become less European in order to cooperate with China, nor does China need to adopt European political mores for cooperation to succeed. Both are now free to cooperate selectively and on the merits of each issue. And a world in which China and Europe cannot find areas of deep mutual interest—despite their deep economic ties and their shared stake in multilateralism—is a world that is measurably poorer for it.

Does History Operate on a Long Fuse? Evidence from Isaac Bashevis Singer

Isaac Bashevis Singer’s The Manor orbits two Polish rebellions (1830 and 1863).

Author’s Note to the Original Edition

The Manor was written between 1953 and 1955. As with many of my stories and all my novels (with the exception of Satan in Goray, which I wrote while still in Warsaw), it was first serialized in The Jewish Daily Forward. Although The Manor was published many years after The Family Moskat, it portrays an earlier period—the epoch between the Polish insurrection of 1863 and the end of the nineteenth century. It was the era of gas lamps, the time when the Poles had finally become resigned to their loss of independence and turned to a kind of national positivism. Poland now began to emerge as an industrial country; railroads were built, factories were opened, and the cities grew rapidly. The Jews, who until 1863 for the most part still lived in a ghetto atmosphere, now began to play an important role in Polish industry, commerce, the arts and sciences. All the spiritual and intellectual ideas that triumphed in the modern era had their roots in the world of that time—socialism and nationalism, Zionism and assimilationism, nihilism and anarchism, suffragettism, atheism, the weakening of the family bond, free love, and even the beginnings of Fascism.

The Estate, a sequel to and the conclusion of The Manor, ends in the last years of the nineteenth century—an epoch when humanism undertook to practice what it had preached for generations. What happened in the village of Jampol, and what was discussed by a small group of self-educated youths in furnished rooms in Warsaw, became the basis of the social upheavals and the terrible disillusions of our present time.

Isaac Bashevis Singer. The Manor. Avon Books, 1979.

If you look at his sentence above describing “All the spiritual and intellectual ideas”, you may start to see what we describe as the long fuse of history. When we are in the present, a lot of the issues from the past emerge again in the future. Reality is such that there is no permanent yesterday.

The novel is also haunted by another kind of deep change, the rise of the world market or globalization.

The novel’s protagonist, Jacoby, acquires a hill, which allows him to begin his fortune with a quarry:

The peasants complained that the Jew was contaminating the Polish countryside, putrefying the air, but the authorities ignored them. Poland, after the insurrection, was full of activity, as if awakened from a long slumber. Workshops sprang up, mines were dug, forests cut down, and railroads built. Polish products, textiles, leather goods, brushes, sieves, sheepskin coats, glassware appeared on the world market. As soon as the Jews were granted permission to reside freely in the cities, the country began to grow.

It was said that Calman had been blessed by a holy man. A building boom was in progress, and his lime quarry yielded immense profits. Scores of Jews and Gentiles earned their livelihood from it. Calman purchased horses and wagons and built a smithy. As if all this were not enough, the Russian government decided to build a railway line through Jampol. …

Isaac Bashevis Singer. The Manor. Avon Books, 1979. p. 9.

Accompanying the rebellions and the commerce are a set of perpetual questions that have yet to be definitively answered.

Does a live carp suffer agonies when it is scaled and cut to pieces for the Sabbath meal? Why are some people poor and others rich? What was there before the universe? Does a goat have a soul? Was Adam a Jew? Did Eve wear a bonnet? And he was constantly finding contradictions in the Holy Writ, pointing out that in one place it is stated that a man is punished only for his own sins, but in another, that the third and fourth generations must suffer for them; and first the Lord is said to be invisible, then it is written that the elders while they ate and drank saw the Lord. For another thing, Ezriel criticized the prophet Elisha for causing the children to be attacked by bears; the boy felt bitterly reproachful toward King David for slaying Uriah the Hittite, and he wept and blasphemed when he read how Abraham sent his concubine Hagar into the desert with nothing but a jug of water, and how she almost perished of thirst.

Isaac Bashevis Singer. The Manor. Avon Books, 1979. pp. 23-24.

Consider specifically the question of what was before the universe. Today our greatest cosmologists and physicists continue to ask this very question. This confirms a famous quote from William Faulkner, “The past is never dead. It’s not even past.”

Economics-Watching: Why Businesses Say Tariffs Have a Delayed Effect on Inflation

[from the Federal Reserve Bank of Richmond, 8 August, 2025]

by R. Andrew Bauer, Renee Haltom and Matthew Martin

Regional Matters

Ever since new tariffs were enacted in early 2025, a key policy question has been what is the extent to which businesses will pass tariff costs through to prices, and when? The effects of a tariff are rarely straightforward, given, among other things, competitive dynamics and the challenges of implementation, but the historically large and changing nature of these tariffs have created additional levels of uncertainty over the effects.

In uncertain times, anecdotal evidence from businesses can be especially insightful. We are learning how businesses are reacting to tariffs through the Richmond Fed’s business surveys as well as through hundreds of one-on-one conversations with Fifth District businesses since the start of 2025.

These conversations showcase that navigating tariffs is a complex and sometimes protracted process for firms, particularly when there is uncertainty. Firms describe several reasons they may not have experienced the full impact of proposed tariffs yet (even when goods and countries they deal with are subject to them), as well as reasons that even when they have incurred tariff-related cost increases, there can be a delayed impact on pricing decisions.

Reasons Firms May Not Have Incurred Tariffs Yet

Business contacts describe several strategies or circumstances that can delay or reduce the tariffs on inputs or other imported items. These include the following:

As our monthly business surveys have found, many firms report deploying more than one strategy to delay tariffs. Notably, many of these delays are only temporary.

Reasons Tariffs May Have a Delayed Impact on Prices

Even when firms have incurred tariffs, they give several reasons why tariffs may not be immediately reflected in the prices they charge for their products. These include the following:

  • Waiting for tariff policy to clarify. Higher prices could reduce demand for goods and services and/or lead firms to lose market share, so many firms said they are hesitant to increase prices until they’re sure tariffs will remain in place. For example, a large national retailer said if tariffs are finalized at a sufficiently low level, they’ll absorb what they’ve incurred to date, but if high tariffs stick, they’ll have to raise prices. A steel fabricator for industrial equipment described being reluctant to raise prices on the 10 percent cost increases they’d seen thus far but would have to raise prices should the increases reach 12 to 13 percent. A grocery store chain was reluctant to raise prices and instead might reduce margins, which had recovered in recent years, to maintain their customer base. Some firms explicitly noted a strategy to both raise prices over time and pursue efficiency gains to cut costs and completely restore margins within a year or two.
  • Elasticity testing. Firms reported testing across goods whether consumers will accept price increases. A furniture manufacturer said he’s seen competitors pass along just 5 percentage points of the tariffs at a time so it isn’t such a huge shock to customers, though in that sector, “We all end in the same place which is the customer bearing most of it.” A national retailer said most firms are doing a version of stair-stepping tariffs through, e.g., raising prices a small amount once or twice to see if consumer demand holds, and if so, trying again two months later. This retailer said prices were going up very marginally in early summer, would increase more in July and August, and would be up by 3 to 5 percent by the end of Q4 and into 2026. Another national retailer said they would start testing the extent to which demand falls with price increases, e.g., when the first items that were subject to tariffs—in this case back to school items—hit shelves in late July.
  • Blind margin. Some firms reported attempting to pass through cost in less noticeable ways. While any price increase to consumers will be captured in measures of aggregate inflation, the fact that price increases may occur on non-tariffed goods might make it difficult to directly relate price increases to tariffs. An outdoor goods retailer said, “Unless it’s a branded item where everyone knows the price, if something goes for $18, it can also go for $19.” A national retailer plans to print new shelf labels with updated pricing, which will be less noticeable for consumers compared to multiple new price stickers layered on top. This takes time (akin to a textbook “menu cost” in economics), so it will not be reflected in prices until July and August. A grocery store said their goal was to increase average prices across the store but focus on less visible prices.
  • Selling out of preexisting inventory: Many firms noted they still have production inventory from before tariffs were announced, so they do not need to raise prices as long as they still sell these lower cost goods. A national retailer noted they have at least 25 weeks of inventory on hand for most imported products. A firm that produces grocery items said they will decide how much to raise prices as they get closer to selling tariff-affected products. Similarly, retailers order seasonal items quarters in advance. Many were receiving items for fall and winter when the new tariffs were going into effect in the spring. They paid the tariff then, but we won’t see the price increase until those items hit the shelves in the fall or winter. One retailer speculated that seasonal décor items will look the most like a one-time increase.
  • Pre-established prices. Many firms face infrequent pricing due to factors like annual contracts or pre-sales. For example, a dealer of farm equipment gets half its sales through incentivized pre-sales to lock in demand and smooth around crop cycles. They noted that while it would be difficult to retroactively ask those customers to pay for part of the tariff, they will pass tariffs directly through on spare parts. A steel fabricator for industrial equipment has a contract for steel through Q3, so they haven’t been impacted yet by price increases. However, they will face new costs once that contract expires.

In general, compared to small firms, large firms have more ability to negotiate with vendors, temporarily absorb costs, burn cash, wait for strategic opportunity, and test things out. This matters because large firms often lead pricing behavior among firms, so these strategic choices may influence the response of inflation to tariffs more generally. Even within firm size, one often hears that negotiations on price vary considerably by relationship and item.

Conclusion

A key question surrounding tariffs is whether any effects on inflation will resemble a short-lived price increase—as in the simplest textbook model of tariffs—or a more sustained increase to inflation that may warrant tighter Fed monetary policy. When asked in May what will determine the answer, Fed Chair Jerome Powell cited three factors [archived PDF]: 1) the size of the tariff effects; 2) how long it takes to work their way through to prices; and 3) whether inflation expectations remain anchored. The insights shared above suggest the process from proposed tariffs to the prices set by firms is far from instantaneous or clear-cut, particularly when tariff policy is changing.

Sensing from businesses suggests that the impact of tariffs on their price-setting [archived PDF] has been lagged, but it is starting to play out. Nonetheless, it remains highly uncertain how tariffs will impact consumer inflation. The discussion above makes clear that firms are nimble and innovative in the face of challenge, and they are concerned about losing customers in the current environment, particularly consumer-facing firms. We will continue to learn from our business contacts and share their insights.


Views expressed are those of the author(s) and do not necessarily reflect those of the Federal Reserve Bank of Richmond or the Federal Reserve System.

World-Watching: India: Building an Export-Oriented Apparel Sector

[from ICRIER, 28 July, 2025]

The Kotak-ICRIER Centre of Excellence for Agriculture Policy, Sustainability, and Innovations (KICEAPSI) is delighted to present its Agri-Food Trends and Analytics Bulletin (AF-TAB), Volume 5, Issue 1, on “Building an Export-oriented Apparel Sector.” [archived PDF] Amidst an evolving geopolitical landscape and shifting global trade patterns, India’s textiles and apparel (T&A) sector stands at a crucial juncture. The country has a rich cultural heritage in textiles and is one of the few nations with the entire T&A value chain, yet its export share in apparel market remains low and stagnant over the last two decades, at least. With China gradually vacating the export market space and global buyers looking to diversify sourcing, India must act swiftly.

This AF-TAB issue explores this window of opportunity through three interesting articles. The first article, ‘India’s Apparel Sector and the Window of Opportunity’, examines India’s stagnant export performance and the structural constraints that have prevented it from capturing a larger global share. It highlights how fragmentation, poor logistics, and high input costs weigh the sector down, despite strong domestic potential. The second article, ‘Missing the Closet: Is India Exporting What the World Wears?’ analyses India’s export basket against global demand trends. It reveals a mismatch between what India produces–largely cotton-based basics and what the global markets demand—man-made fibres (MMF)-based, fashion-forward garments. This misalignment is most visible in key markets like the U.S. and EU. The third article, ‘PM MITRA Parks—Can They Lift Apparel Exports?’, evaluates the government’s flagship scheme designed to address these inefficiencies. While PM MITRA is a much-needed step to create scale, plug-and-play infrastructure, and attract investment, its success depends on timely execution, policy alignment, and strategic targeting.

Read the bulletin [archived PDF].

China: Deep History

Winston Churchill says somewhere (if we paraphrase) that the further back you are able to look, the more secure your ability to analyze the present and the future. Without these ‘historical smarts’, your sense of direction is very feeble. Let us use the novel, Lost Illusions, by Honoré de Balzac as a back door into historical smarts.

This novel was originally published in three parts between 1837 and 1843 and is set mostly in the 1820s, primarily in provincial France. It is unique because it starts with technology and commerce.

At the time when this story begins, the Stanhope press and inking-rollers were not yet in use in small provincial printing-offices. Angoulême, although its paper-making industry kept it in contact with Parisian printing, was still using those wooden presses from which the now obsolete metaphor ‘making the presses groan’ originated. Printing there was so much behind the times that the pressmen still used leather balls spread with ink to dab on the characters. The bed of the press holding the letter-filled ‘forme’ to which the paper is applied was still made of stone and so justified its name ‘marble’. The ravenous machines of our times have so completely superseded this mechanism — to which, despite its imperfections, we owe the fine books produced by the Elzevirs, the Plantins, the Aldi and the Didots — that it is necessary to mention this antiquated equipment which Jérôme-Nicolas Séchard held in superstitious affection; it has its part to play in this great and trivial story.

Not only do we get this conceptual framework about printing technology, but later on in the novel, Balzac gives us a further insight into paper-making and textiles, including a long discussion of China.

In England, where four-fifths of the population use cotton to the exclusion of linen, they make nothing but cotton paper. The cotton paper is very soft and easily creased to begin with, and it has a further defect: it is so soluble that if you seep a book made of cotton paper in water for fifteen minutes, it turns to a pulp, while an old book left in water for a couple of hours is not spoilt. You could dry the old book, and the pages, though yellow and faded, would still be legible, the work would not be destroyed.

“There is a time coming when legislation will equalize our fortunes, and we shall all be poor together; we shall want our linen and our books to be cheap, just as people are beginning to prefer small pictures because they have not wall space enough for large ones. Well, the shirts and the books will not last, that is all; it is the same on all sides, solidity is drying out. So this problem is one of the first importance for literature, science, and politics.

“One day, in my office, there was a hot discussion going on about the material that the Chinese use for making paper. Their paper is far better than ours, because the raw material is better; and a good deal was said about this thin, light Chinese paper, for if it is light and thin, the texture is close, there are no transparent spots in it. In Paris there are learned men among the printers’ readers; Fourier and Pierre Leroux are Lachevardiere’s readers at this moment; and the Comte de Saint-Simon, who happened to be correcting proofs for us, came in in the middle of the discussion. He told us at once that, according to Kempfer and du Halde, the Broussonetia furnishes the substance of the Chinese paper; it is a vegetable substance (like linen or cotton for that matter). Another reader maintained that Chinese paper was principally made of an animal substance, to wit, the silk that is abundant there. They made a bet about it in my presence. The Messieurs Didot are printers to the Institute, so naturally they referred the question to that learned body. M. Marcel, who used to be superintendent of the Royal Printing Establishment, was umpire, and he sent the two readers to M. l’Abbe Grozier, Librarian at the Arsenal. By the Abbe’s decision they both lost their wages. The paper was not made of silk nor yet from the Broussonetia; the pulp proved to be the triturated fibre of some kind of bamboo. The Abbe Grozier had a Chinese book, an iconographical and technological work, with a great many pictures in it, illustrating all the different processes of paper-making, and he showed us a picture of the workshop with the bamboo stalks lying in a heap in the corner; it was extremely well drawn.

“Lucien told me that your father, with the intuition of a man of talent, had a glimmering of a notion of some way of replacing linen rags with an exceedingly common vegetable product, not previously manufactured, but taken direct from the soil, as the Chinese use vegetable fibre at first hand. I have classified the guesses made by those who came before me, and have begun to study the question. The bamboo is a kind of reed; naturally I began to think of the reeds that grow here in France.

“Labor is very cheap in China, where a workman earns three halfpence a day, and this cheapness of labor enables the Chinese to manipulate each sheet of paper separately. They take it out of the mould, and press it between heated tablets of white porcelain, that is the secret of the surface and consistence, the lightness and satin smoothness of the best paper in the world. Well, here in Europe the work must be done by machinery; machinery must take the place of cheap Chinese labor. If we could but succeed in making a cheap paper of as good a quality, the weight and thickness of printed books would be reduced by more than one-half. A set of Voltaire, printed on our woven paper and bound, weighs about two hundred and fifty pounds; it would only weigh fifty if we used Chinese paper. That surely would be a triumph…

In 2025, we are to some extent, back to China, going from the proto-industrial world to our industrial and even digital world.

To educate oneself on all of this, you should look at the supreme scholarly achievement of the 20th century, namely Professor Joseph Needham’s masterpiece, Science and Civilisation in China.

Movies and Chemistry: Keeping the Enchantment of Education

Several movies give you an “enchanting” back door or window into chemistry so that you can “beat” the tediousness of regular education and come into the field and its topics via these movies:

I.

The Man in the White Suit is a 1951 British comedy classic with Alec Guinness as a genius research chemist. He fiddles with his flasks and polymer and textile chemistry experiments until he invents a fabric that shows no wear and tear “forever.” This would seem like a great boon to humanity in its clothing needs but the chemist (“Sidney Stratton”) finds that both labor and management reject his discovery violently as it threatens jobs and profits. Textile or fabric polymer chemistry is at the heart of the plot.

Cry Terror! is a taut 1958 crime thriller movie with James Mason and Rod Steiger. The plot involves the terrorist threat of exploding a domestic airliner with a hidden RDX cache (a TNT successor) unless the demanded payment is made.

RDX was used by both sides in World War II. The U.S. produced about 15,000 long tons per month during WWII and Germany about 7,000 long tons per month. RDX had the major advantages of possessing greater explosive force than TNT, used in World War I and requiring no additional raw materials for its manufacture.

Semtex is a general-purpose plastic explosive containing RDX and PETN. It is used in commercial blasting, demolition, and in certain military applications.

A Semtex bomb was used in the Pan Am Flight 103 (known also as the Lockerbie) bombing in 1988. A belt laden with 700 g (1.5 lb) of RDX explosives tucked under the dress of the assassin was used in the assassination of former Indian prime minister Rajiv Gandhi in 1991.

The 1993 Bombay bombings used RDX placed into several vehicles as bombs. RDX was the main component used for the 2006 Mumbai train bombings and the Jaipur bombings in 2008. It also is believed to be the explosive used in the 2010 Moscow Metro bombings.

Traces of RDX were found on pieces of wreckage from 1999 Russian apartment bombings and 2004 Russian aircraft bombings. Further reports on the bombs used in the 1999 apartment bombings indicated that while RDX was not a part of the main charge, each bomb contained plastic explosive used as a booster charge.

Ahmed Ressam, the al-Qaeda Millennium Bomber, used a small quantity of RDX as one of the components in the bomb that he prepared to detonate in Los Angeles International Airport on New Year’s Eve 1999-2000; the bomb could have produced a blast forty times greater than that of a devastating car bomb.

In July 2012, the Kenyan government arrested two Iranian nationals and charged them with illegal possession of 15 kilograms (33 pounds) of RDX. According to the Kenyan Police, the Iranians planned to use the RDX for “attacks on Israeli, U.S., UK and Saudi Arabian targets.”

RDX was used in the assassination of Lebanese Prime Minister Rafic Hariri on February 14, 2005.

In the 2019 Pulwama attack in India, 250 kg of high-grade RDX was used by Jaish-e-Mohammed. The attack resulted in the deaths of 44 Central Reserve Police Force personnel as well as the attacker.

Semtex was developed and manufactured in Czechoslovakia, originally under the name B 1 and then under the “Semtex” designation since 1964, labeled as SEMTEX 1A, since 1967 as SEMTEX H, and since 1987 as SEMTEX 10. Originally developed for Czechoslovak military use and export, Semtex eventually became popular with paramilitary groups and rebels or terrorists because prior to 2000 it was extremely difficult to detect, as in the case of Pan Am Flight 103.

The Russian apartment bombings were a series of explosions that hit four apartment blocks in the Russian cities of Buynaksk, Moscow and Volgodonsk in September 1999, killing more than 300, injuring more than 1,000, and spreading fear across the country. The bombings, together with the Invasion of Dagestan, triggered the Second Chechen War. The handling of the crisis by Vladimir Putin, who was prime minister at the time, boosted his popularity greatly and helped him attain the presidency within a few months.

The blasts hit Buynaksk on 4 September and in Moscow on 9 and 13 September. On 13 September, Russian Duma speaker Gennadiy Seleznyov made an announcement in the Duma about receiving a report that another bombing had just happened in the city of Volgodonsk. A bombing did indeed happen in Volgodonsk, but only three days later, on 16 September. Chechen militants were blamed for the bombings, but denied responsibility, along with Chechen president Aslan Maskhadov.

A suspicious device resembling those used in the bombings was found and defused in an apartment block in the Russian city of Ryazan on 22 September. On 23 September, Vladimir Putin praised the vigilance of the inhabitants of Ryazan and ordered the air bombing of Grozny, which marked the beginning of the Second Chechen War. Three FSB agents who had planted the devices at Ryazan were arrested by the local police, with the devices containing a sugar-like substance resembling RDX.

II.

The movie Khartoum (1966) has General Charles Gordon traveling to Sudan in 1884 to quell the “mad mullah” the Mahdi. (Osama bin Laden of his day).
At the train station where General Gordon starts his trip, there’s a railway ad sign that promotes the use of “Wright’s Coal Tar Soap.”

This gives us a sign of the rise of the modern chemical industry.

III.

Think of “Sherlock Holmes” in terms of all the movies and TV series or the original stories and books:

Holmes has to explain to Watson how he survived the assassination attempt on him by Moriarty, “the Napoleon of Crime” who threw him off the Reichenbach Falls. Holmes explains that he faked Moriarty out and clung to a bush or something and was (obviously) not killed.

Holmes tells Watson what he does when he returns to civilization and travels and studies for some three years:

“I then passed through Persia, looking in at Mecca, and paid a short but interesting visit to the Khalifa at Khartoum, the results of which I communicated to the Foreign Office. Returning to France, I spent some months in a research into the coal-tar derivatives, which I conducted in a laboratory at Montpellier, in the south of France.”

The context implies the year 1894.

There is clear evidence that Mr. Holmes was deeply involved in the research of coal-tar derivatives as early as 1889 when the events of the Copper Beeches matter were transpiring.

We are told that on an evening in 1889, Mr. Holmes was seated in 221B Baker Street at the deal table loaded with retorts and test tubes. He was settling down to one of those all-night chemical researches in which he frequently indulged.

The research work was interrupted by a message of distress from Violet Hunter. Watson found that there was a train the next morning, and Holmes tells Watson:

“That will do very nicely. Then perhaps I had better postpone my analysis of the acetones as we may need to be at our best in the morning.”

It is clear that Holmes was engaged in coal-tar research long before his visit to Montpellier in the south of France.

The quotation from the Copper Beeches story refers to acetones, not to coal-tar derivatives.

“In the fractional distillation of coal-tar, the distillate separates into five distinct groups or layers, depending upon the stage of the process and the amount of heat applied. Category-one of the five includes benzene, toluene, xylenes and cumenes.

Acetones [dimethelketone-CH3COCH3] may be derived from the oxidation of cumene. And cumene [isopropylbenzene-C6H5C(CH3)2] is derived by distillation from the coal-tar naphtha fractions.”

Cumenes are derived from coal-tar, and acetones are derived from cumenes. Thus, a study of the acetones is, necessarily, research into coal-tar derivatives.

The rise of chemical engineering and organic chemistry are at the heart of the Sherlock Holmes stories.

Thus we can “climb” into chemistry via these books and movies and keep a feeling of enchantment as a kind of educational “shoehorn.”

Movies As Parallel Universities: The Promised Land

The Promised Land is a Polish film masterpiece based on Nobel laureate Reymont’s 1899 novel. The novel describes the industrialization of the Polish city of Łódź in the nineteenth century and reminds one a little of Upton Sinclair’s The Jungle of 1906 but with the emphasis not on dangers and miseries for labor but on the “mad dance” of the capitalist industrial free-for-all:

“The Promised Land (Polish: Ziemia obiecana) is a 1975 Polish drama film directed by Andrzej Wajda, based on the novel by Władysław Reymont. Set in the industrial city of Łódź, The Promised Land tells the story of a Pole, a German, and a Jew struggling to build a factory in the raw world of 19th century capitalism.”

(Wikipedia)

Wajda presents a shocking image of the city, with its dirty and dangerous factories and ostentatiously opulent residences devoid of taste and culture. The film follows in the tradition of Charles Dickens, Émile Zola and Maxim Gorky, as well as German expressionists such as Dix, Meidner and Grosz, who gave testimony of social protest. Think also of the English poet, William Blake’s metaphor describing industrial England as a world of “dark Satanic mills.”

Reymont, the author of the original novel, was in his heart a ruralist and intensely disliked the modern industrial world, which he saw as maniacal and destructive.

In the 2015 poll conducted by the Polish Museum of Cinematography in Łódź, The Promised Land was ranked first on the list of the greatest Polish films of all time.

Plot

“Karol Borowiecki (Daniel Olbrychski), a young Polish nobleman, is the managing engineer at the Bucholz textile factory. He is ruthless in his career pursuits, and unconcerned with the long tradition of his financially declined family. He plans to set up his own factory with the help of his friends Max Baum (Andrzej Seweryn), a German and heir to an old handloom factory, and Moritz Welt (Wojciech Pszoniak), an independent Jewish businessman. Borowiecki’s affair with Lucy Zucker (Kalina Jędrusik), the wife of another textile magnate, gives him advance notice of a change in cotton tariffs and helps Welt to make a killing on the Hamburg futures market. However, more money has to be found so all three characters cast aside their pride to raise the necessary capital.

On the day of the factory opening, Borowiecki has to deny his affair with Zucker’s wife to a jealous husband who, himself a Jew, makes him swear on a sacred Catholic object. Borowiecki then accompanies Lucy on her exile to Berlin. However, Zucker sends an associate to spy on his wife; he confirms the affair and informs Zucker, who takes his revenge on Borowiecki by burning down his brand new, uninsured factory. Borowiecki and his friends lose all that they had worked for.

The film fast forwards a few years. Borowiecki recovered financially by marrying Mada Müller, a rich heiress, and he owns his own factory. His factory is threatened by a workers’ strike. Borowiecki is forced to decide whether or not to open fire on the striking and demonstrating workers, who throw a rock into the room where Borowiecki and others are gathered. He is reminded by an associate that it is never too late to change his ways. Borowiecki, who has never shown human compassion toward his subordinates, authorizes the police to open fire nevertheless.”

(Wikipedia)

Notice the sentence above:

Borowiecki’s affair with Lucy Zucker (Kalina Jędrusik), the wife of another textile magnate, gives him advance notice of a change in cotton tariffs and helps Welt to make a killing on the Hamburg futures market.

Textiles and hence cotton prices and tariffs are, as elsewhere, “the name of the game” in Łódź industry.

There is a concrete basis in reality for this 19th century version of our derivatives trading contributing to 2008 and the Great Recession:

In a discussion of futures markets, we read:

“Already in 1880 merchants were buying an idea rather than a palpable commodity, as we saw happen in the grains futures market. In that year, sixty-one million bags (coffee, in this example) were bought and sold on the Hamburg futures market, when the entire world harvest was less than seven million bags!

It was this sort of speculation that caused the German government to shut down the futures market for a while.”

(Global Markets Transformed: 1870-1945, Steven Topik & Allen Wells, Harvard University Press, 2012, page 234)

The danger with such speculative excesses is that the economy, national or global, becomes a “betting parlor” (bets on bets on bets in an infinite regress, as in the lead-up to 2008) and governments have been paralyzed and passive in the face of such “casino capitalism” (to use Susan Strange’s vocabulary) because laissez-faire neoliberal ideology has a profound hold in the West, especially in Anglo-America.

Professor Milton Friedman (died in 2006) argued in interviews going back to the 1960s and before, that speculators fulfill a valuable economic function since they “keep the system efficient.”

The current semi-dismantling and neutralizing of the Dodd-Frank financial reforms and guidelines has to do not only with lobbying but also with the hold of various strands of such “laissez-faire” ideology and market fundamentalism.

Keynes’s classic essay, “The End of Laissez-Faire” tends to yield to the countervailing force of this market fundamentalism/“laissez-faire religion.”

Looking Backwards and Forwards at the Same Time

Janus and Bi-Directional Smarts

The Roman god Janus looks backwards and forwards at the same time and learning to be somewhat Janus-like is very conducive in the metaintelligence (i.e., larger overview) quest.

There’s a useful French phrase, “reculer pour mieux sauter” which means like a high jumper, you have to take steps backwards to jump higher. In other words, learn to look bi-directionally at the world.

First look back, then forward.

Here’s a concrete example:

W. Arthur Lewis, the “father” of development economics, originally from the Caribbean, taught at Princeton. He won the Nobel in 1979 and wrote various classics such as Growth and Fluctuations, 1870-1913 (1978).

Lewis writes:

In this book we shall not be attempting to give formal or complete explanations of why fluctuations occurred. Like the captain of a ship navigating in stormy seas, we shall need to identify the waves, without needing an exhaustive theory of what causes waves.

When analyzing these fluctuations economists have identified four different cycles, distinguished by length of periodicity, each of which is named after the economist who first wrote about it:

the Kitchin (about three years)
the Juglar (about nine years)
the Kuznets (about twenty years)
the Kondratiev (about fifty years)

(W. Arthur Lewis, Growth and Fluctuations, 1870-1913, 1978, page 19)

Lewis gives us a quick overview of how we got to the era covered by his book:

“The essence of the industrial and agricultural revolutions in the first three quarters of the nineteenth century was in new ways of doing old things—of making iron, textiles and clothes, of growing cereals, and of transporting goods and services. In the last quarter of the nineteenth century the revolution added a new twist—that of making new commodities: telephones, gramophones, typewriters, cameras, automobiles and so on, a seemingly endless process whose twentieth century additions include aeroplanes, radios, refrigerators, washing machines and pleasure boats.”

(Growth and Fluctuations, 1870-1913, page 29)

Professor Norman Stone in his masterpiece on WWI calls this late nineteenth century explosion of material change and inventions the greatest fast quantum leap in world history in transforming the world.

If one reads these lines with a “Janus mind” we wonder, looking forward from the Lewis book and its era:

  1. How does his catchy metaphor of waves in the ocean relate to fluctuations and cycles? When Ben Bernanke (Fed Chair) describes recent decades as “The Great Moderation” does he mean to imply that Lewis-type waves disappeared or got much smaller?
  2. Can computers and mobile phones really match cars and planes in profundity of impact? Or is it only the tremendous spread of mobile or smartphones in the Global South that can?

In fact, the recent economic history classic, Robert Gordon’s The Rise and Fall of American Growth argues against the assumption of endless technical change as a growth accelerator or endless frontier:

In the century after the Civil War, an economic revolution improved the American standard of living in ways previously unimaginable. Electric lighting, indoor plumbing, home appliances, motor vehicles, air travel, air conditioning, and television transformed households and workplaces. With medical advances, life expectancy between 1870 and 1970 grew from 45 to 72 years. Weaving together a vivid narrative, historical anecdotes, and economic analysis, The Rise and Fall of American Growth provides an in-depth account of this momentous era. But has that era of unprecedented growth come to an end?

Gordon challenges the view that economic growth can or will continue unabated, and he demonstrates that the life-altering scale of innovations between 1870 and 1970 can’t be repeated. He contends that the nation’s productivity growth, which has already slowed to a crawl, will be further held back by the vexing headwinds of rising inequality, stagnating education, an aging population, and the rising debt of college students and the federal government. Gordon warns that the younger generation may be the first in American history that fails to exceed their parents’ standard of living, and that rather than depend on the great advances of the past, we must find new solutions to overcome the challenges facing us.

A critical voice in the debates over economic stagnation, The Rise and Fall of American Growth is at once a tribute to a century of radical change and a harbinger of tougher times to come.

  1. Why does one not read of the four cycles mentioned by Lewis (i.e., Kitchin) and the rest listed above in today’s business and financial press? Has there been some great discontinuity?

If you apply a “Janus mind” to the past (described by Lewis) and our sense of the future (described by techno-pessimists like Gordon) you get a more thoughtful sense of “the human prospect.”