CCG’s President says there will be no diplomatic masterstroke in Ukraine’s absence, but serious consideration of a ceasefire can lay the groundwork for peace
Putin was receptive, warmly welcoming the idea of a China-hosted meeting. Trump, too, has expressed a willingness to meet Xi and Putin. These expressions of openness offer an opportunity we must seize in pursuit of peace.
Some in the United States and Europe question the value of such a summit. They may fear restoring Putin’s standing or normalising the conflict without yielding any real progress towards an end to the war. That risk is still real but these largely Western fears must be tempered by the very real, very human cost of letting the war continue unabated.
In August last year, I extended that train of logic in Foreign Policy, where I proposed a seven-party format for peace negotiations and suggested that a peacekeeping force include troops from European and BRICS countries. A meeting of the three leaders in Shenzhen could help lay the groundwork for these broader diplomatic and peacekeeping efforts.
Without Ukraine’s participation, such a meeting is unlikely to produce a diplomatic masterstroke that ends the war. But the three leaders need not put the war to rest at a table in Shenzhen to make progress. Serious consideration of a ceasefire along the current line of contact—an approach Ukrainian PresidentVolodymyr Zelenskyy has supported—could give peace efforts fresh momentum, leaving the final status of disputed territories for subsequent negotiations.
Further agreement could be sought on the protection of nuclear facilities, or a mutual end to strikes on energy infrastructure, new prisoner exchanges or improved humanitarian access. Of course, issues of sovereignty, security guarantees, Russia’s security concerns and Europe’s security commitments would remain. But these need not all be resolved at once before a ceasefire can begin.
Already, years of war have inflicted immense suffering on both Russia and Ukraine. Neither side achieved its objectives, and both need a dignified way out that protects their core interests. Thus, we must open a path towards peace without requiring either side to concede defeat. China could help bridge this gap by bringing Xi, Trump and Putin together in Shenzhen to explore how a ceasefire and wider negotiations involving Ukraine might work.
The United Nations could stand at the core of such an arrangement by monitoring any ceasefire and preventing a return to fighting by physical peacekeeping if the parties are so inclined.
For a broader negotiation on settlement, I find myself returning to a seven-party format that would bring together the five permanent members of the UN Security Council—China, France, Russia, Britain and the U.S.—alongside Ukraine and the European Union. An understanding reached in Shenzhen could give momentum to this broader negotiating process and free up the Security Council for action.
A peacekeeping force composed entirely of NATO or European troops might be unacceptable to Russia. Yet a mission without European participation would struggle to reassure Ukraine and its neighbours. Any workable arrangement would need to address both concerns.
In my Foreign Policy article, I proposed a peacekeeping force drawing troops from five European countries—Germany, France, Britain, Poland and Italy—and five members of the BRICS grouping, such as China, India and Brazil. And while the exact formulation, from the composition and mandate to the terms of deployment, would need to be negotiated with the consent of Russia and Ukraine, and the agreement of the contributing countries, the core idea remains sound.
As a permanent member of the UN Security Council and the largest contributor of peacekeeping personnel among the five permanent members, China is well positioned to help. Its distinctive role in the global economy and dialogue with Russia, Ukraine, the U.S. and Europe, give it channels through which to coax the parties towards peace. But this process must begin somewhere, and that somewhere could be Shenzhen.
Nor should APEC be the end of the diplomatic effort. With an understanding reached by the leaders in Shenzhen, the Security Council may pick up the momentum by advancing ceasefire and peacekeeping proposals. The Group of 20 could then join the effort to rally support from major economies with an interest in maintaining the deal. Each would play a different role and would not be tasked with settling the entire conflict.
China’s role in the Saudi Arabia-Iran rapprochement in 2023 showed Beijing’s ability to open a door after years of enmity. The Ukraine war is different, and there can be no guarantee of a similar outcome. But diplomacy must begin somewhere, particularly when fighting has brought such destruction.
The central question is whether such a meeting could help bring the war to an end. In that light, any gain in prestige for an individual leader is almost irrelevant. And if the three leaders could agree on practical steps towards peace, they would give the United Nations and the wider international community a material basis upon which peace could be built.
In the plains of Assam, different kinds of rain are often distinguished through vivid local expressions that reflect their intensity and impact on everyday life. One such term is “sagoli-kheda-borokhun” (the rain that chases goats). It refers to a light shower, enough to send goats hurrying into their sheds while people continue with their daily activities. As the rainfall intensifies, it may be described as “goru-kheda-borokhun” (cow-chasing rain), followed by “manuh-kheda-borokhun” (people-chasing rain), when even humans seek shelter from the downpour. At the extreme end of this scale of vernacular expressions of rainfall intensity lies “gor-kheda-borokhun” (the rain that chases away rhinos), evoking a deluge so intense that even Assam’s iconic one-horned rhinoceroses would retreat and look for shelter. With rapid urbanization and changing rainfall patterns, such beautiful expressions of rain have lost continuous usage, especially among the younger generation, who no longer name types of rains.
These expressions reveal the richly textured ways in which communities inhabiting the water-abundant landscapes of Northeast India have understood and interpreted rainfall. Their environmental imagination is shaped not only by the rains themselves but also by the sounds, movements, and rhythms of the ecosystems around them. Among the most evocative signs of the approaching monsoon was the chorus of frogs inhabiting the “pukhuris” (ponds), “khaals” (natural drainage channels), and “beels” (wetlands). Their persistent croaking, described locally as the rhythmic “tur-tu-rai” of an assembled army of frogs, would fill the night air. Hearing this familiar symphony, people would often remark that the rains were on their way.
In today’s times, such soundscapes have diminished considerably and the traditional knowledge of being able to predict rains by observing sounds and signs in nature have not been passed on. The familiar chorus of frogs on humid nights has grown noticeably quieter as ponds have deteriorated, wetlands have been drained, and traditional water bodies have gradually disappeared from the landscape. Here, I look at the languages and imaginations of communities, and how these interact with the annual rains and storms along the Eastern Himalayas, how they keep record of the changes in the climate patterns in their community lives through their vernacular depictions of storms and rains, and how the current climate crisis has clouded their traditional communication methods.
Water-Abundant Worlds
The Himalayan river-systems and the plains they nourish have always been regarded as a water-abundant environment, with monsoons, storms and rains forming an essential part of the lives and imaginations of communities living there. Nation-state borders, which straddle river-systems and regions across the Himalayas, bring in an additional layer of complexity to the various discourses of climate change disasters and patterns in the region, which are already exacerbated by infrastructural interventions on the river systems.
The languages and imaginations of Himalayan communities through which they describe the monsoons, climate change, storms, and rainfall patterns in their daily lives and natural environment, and how they are shaped by the interventions and narratives deployed by the nation-state in the Eastern Himalayas serve as critical crisis communication, often proving more useful and timely than governmentcommunication. The monsoon rains that stream in from the Indian Oceancurrents and extend up to the heights of the easternmost fringes of the Himalayas bring most of the Himalayan river-systems to life. The monsoon clouds, after they enter Northeast India, play a veritable ping-pong between the low-lying rolling hills of the Patkai ranges and the towering eastern Himalayan mountain ranges, and the rains and storms that ensue from this match nourish the various communities, sustain the forests, and shape the landscape. This interaction forms an archive of climate disasters in the region.
Modern meteorological forecasting methods have greatly improved with scientific progress and modelling and availability of long-term data. However, from my research, it has been evident that the medium-range and long-range predictions of storms and rainfall patterns have low reliability at the local level, meaning state-led communication methods are not effective or timely. There are externalities of data collection challenges and reliability of what actually constitutes long-term data and the rapid infrastructure push and anthropogenic changes in the context of the fragile and ever-crumbling-and-forming Eastern Himalayas.
Bordoisila is the personified name given to an annual spring storm that ravages the foothills of the Eastern Himalayas, often spanning across Assam, Meghalaya, Arunachal Pradesh, Nagaland, and Bhutan. The community memory of Bordoisila is archived over time through stories of the storm returning to “her maternal home,” Assam, to celebrate Bohag Bihu, the mid-April spring festival, and accounting for the ferocity and devastation it regularly brings along, as well as the variation in timing of the storm’s arrival and when “she returns” after celebrating. Communities provide token offerings of festive food and clothing to Bordoisila, imploring the storm to pass by gently in “her path.” The variation in timing and ferocity of the storm is recorded in recent community memory as the personified storm managing to come home early this year as “she got to leave early from her workplace.” Originating in the Chotanagpur plateau and gathering force from the Bay of Bengal, she again returns in an angry mood as if “she was not treated well by her mother” with festive goodies and good food.
Personified Storms
Over years of research in the region, I have noted that communities rarely rely on modern meteorological forecasting information for the stormy season. They know it only by community memory and their sense of the ferocity of the storm when it passes by—among a series of spring storms—and declare that “she has finally arrived” and “she will soon return after celebrating Bihu.” It is along the trail of Bordoisila that the first wave of floods also arrives in Assam, and the traditional knowledge repository known as “Dakor Boson,” a collection of vernacularprose and poetrysayings, depicting how the coming monsoon and the ensuing agricultural cropping cycle will span out. The first floods were always celebrated with the Bihu dance, and the storm Bordoisila is revered despite its ferocity, as it brings the rain and nutrient-rich silt to nourish the overall landscape. However, with climate change and anthropogenic interventions, the language of climate crises has changed from a sense of celebration and reverence to utter despair.
Over the past several decades, Northeast India has witnessed profound shifts in its monsoon patterns. Periods of unusually intense rainfall have triggered devastating floods, while prolonged dry spells have brought drought-like conditions to many areas. In response to persistent droughts, communities across Assam have continued to observe customs such as frog-marriage ceremonies, invoking these creatures regarded as messengers of the rain-gods, to restore the rains through their renewed croaking. In Meghalaya, rainfall that used to last nine nights and days in a continuous rhythmic pattern, known as “slap-khyndai-miet-khyndai-sngi,” has, over recent years, lost its original community language emphasis, as such long-enduring rainfall patterns have diminished greatly.
Among the Idu-Mishmi of eastern Arunachal Pradesh, traditional ritual specialists are called upon to communicate with rain spirits, seeking their intervention both when the rains fail to arrive and when incessant downpours raise fears of catastrophic flooding. The Idu-Mishmi term for rain, “ayyo or ayyoyo,” carries deep cultural significance within these practices. Jibi Pulu, an Idu-Mishmi community leader and environmental activist, points to how different kinds of rainfall were once understood to perform distinct ecological functions in the forests of the Dibang Valley. Certain rains signaled the shedding of leaves, others supported flowering cycles, while some heralded the arrival of migratory birds that seasonally visited the region’s rich forest ecosystems. However, he observed that such patterns have become increasingly difficult to anticipate, as deforestation, climate change, and human intervention have disrupted environmental rhythms that earlier generations could interpret with a high confidence.
Many Idu-Mishmi elders similarly attribute the growing unpredictability of rainfall and the increasing occurrence of extreme floods on the Dibang River and its tributaries to a deterioration in the relationship between people and the natural world. They regard practices such as the indiscriminate slaughter of animals and the growing trend of winter picnics on dry riverbeds (where meals are prepared directly on the exposed riverbed) as acts that offend river spirits. In their understanding, these transgressions disturb the balance between humans and the spiritual forces inhabiting the landscape, contributing to erratic weather patterns and destructive flooding events. Some historic flooding events are referred to by communities with names of where such flooding originated, such as the “China-paani” of the year 2000 and the recent episodes of “Bhutan-baanpaani” along the Bhutan–Assam border. This vocabulary has expanded to include specific dam-induced floods such as Ranganadi-floods in Assam.
Culturally Grounded Approaches
The diverse linguistic expressions, traditional knowledge systems, and lived experiences through which indigenous communities across Northeast India understand rainfall, storms, climate variability, and recurring flood events deserve to be documented, connected, and amplified within broader conversations on environmental democracy and transboundary cooperation. Bringing these perspectives together can help foster more inclusive dialogues across the Eastern Himalayas and the Patkai mountain ranges, enabling local communities to participate meaningfully in decision-making processes concerning ecology, environmental governance, infrastructure development, disaster preparedness, crisis communication, and other issues that directly shape their everyday lives and livelihoods. For generations, communities have relied on close observation of their surroundings to interpret changes in weather and rainfall patterns, rhythms of rivers, and flood cycles.
As environmental transformations become more pronounced and traditional indicators grow increasingly uncertain, their ability to understand and articulate these changes offers valuable insights into the realities of climate change on the ground. Recognizing and engaging with such lived experiences, local knowledge, and environmental imaginations is, therefore, essential to strengthening civil society participation and building more democratic, responsive, and culturally grounded approaches to environmental governance in the region. Modern meteorological forecasting methods need to learn from traditional wisdom and social innovation and the vast archive of knowledge which have recorded past disasters and also can predict future ones. The rapid pace and scale of transformation along the Eastern Himalayas are rendering traditional knowledge systems incapable of providing climate solutions.
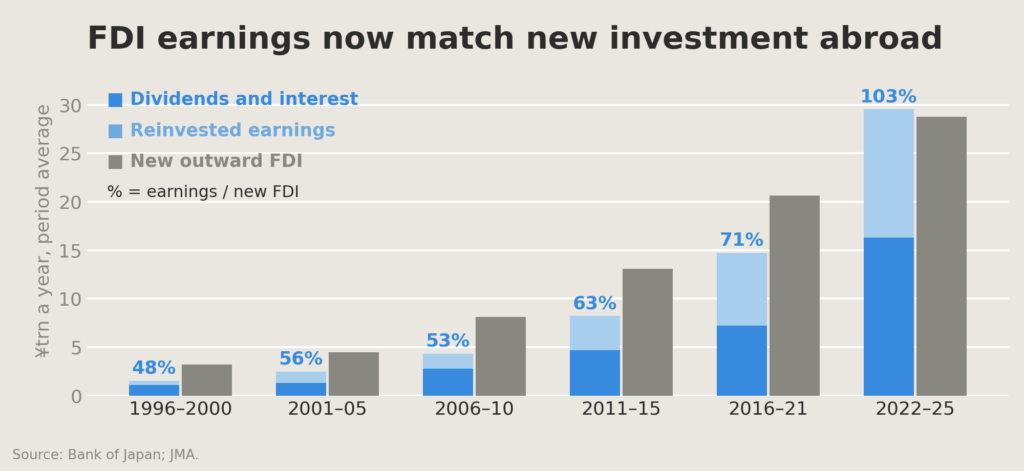
Earnings on Japan’s foreign direct investment (FDI) reached 103% of new FDI in 2022–25. With dividends and retained earnings counted together, Japan Inc. now needs to sell little yen to invest abroad.
[by OKUBO Takuji]
Key takeaways
Foreign affiliates now earn about as much as Japan invests abroad each year. Reinvested earnings, dividends and interest together reached 103% of new outward FDI in 2022–25, against 48% in 1996–2000.
Dividends from foreign affiliates account for a growing share of Japanese corporate profit. We estimate that foreign affiliates contributed 13.4% of Japan Inc.’s earnings in FY2025, up from 1.7% in FY1996.
Corporate investment abroad now involves little net yen selling. After dividends and interest paid home, the estimated outflow has been close to zero since 2022, down from about ¥5 trillion a year, or about 1% of GDP, on average in the 2010s.
Japan’s FDI stock now earns 103% of new investment
“Japan’s ageing and shrinking population depresses expected demand at home. Expected returns remain higher abroad, so Japanese companies have accelerated outward direct investment” (my translation). — MATSUBAYASHI Yōichi [松林 洋一], MOF PRI, chapter 8, p.136.
“Companies invested abroad because they saw no promising investments in Japan; they are unlikely to bring back every return. On a cash-flow basis, the external balance is in deficit and is one factor behind the weak yen” (my translation). — KARAKAMA Daisuke [唐鎌 大輔], MOF PRI, chapter 10, pp.178 and 175.
However, my review of recent data shows that while their premise of low growth prospects in Japan is probably still right, the direct investmentJapan has accumulated abroad has reached a level where it earns enough to cover Japan’s new investment abroad. This changes the exchange-rate implication even if Japan keeps investing abroad.
Overseas affiliates pay interest and dividends to their parent companies in Japan. Those dividends have become a sizable part of corporate Japan’s income: we estimate that they made up 13.4% of Japanese corporate profit in FY2025, up from 1.7% in FY1996.
When foreign affiliates retain their earnings on their balance sheets, Japan’s balance of payments statistics record them as FDI from Japan, even though no money crosses the border. While the companies receiving FDIdividends and the companies paying for new FDI are not necessarily the same, Japan Inc. as a whole is now financing its FDI almost entirely from the earnings of its overseas affiliates. At the current level of FDI, little new yen needs to be converted into foreign currencies as Japan goes about investing abroad.
A strong yen helped drive Japan’s first outward FDI boom
Japan’s outward investment was heavily restricted after WWII, requiring case-by-case permission from the government. Approvals became more and more automatic over the years until outward investment became “free in principle” in 1980. Trade friction with the US-led Japanese carmakers to restrain their exports from 1981, pushing them to build factories abroad. The rapid appreciation of the yen was also a factor. The yen strengthened from ¥242 per dollar before the Plaza Accord in September 1985 to ¥121 by the end of 1987. Japanese producers had to move lower value-added work abroad. The strong yen also gave Japanese financial institutions sizable purchasing power for a while, until the stock and property bubbles burst in 1990 and 1991.
All of these factors contributed to a rapid increase in outward FDI through the 1980s and 1990s (chart 2).
The next phase was sustained by a different pressure. With weak growth and low interest rates at home, Japan Inc. kept investing abroad, across a broader range of industries. Between 1995 and 2025, the stock of FDI rose from 9% of Japan’s GDP to 58% (chart 4). In 2025, it is as large as about 38% of the private sector’s domestic fixed capital, on our estimate.
Chart 4
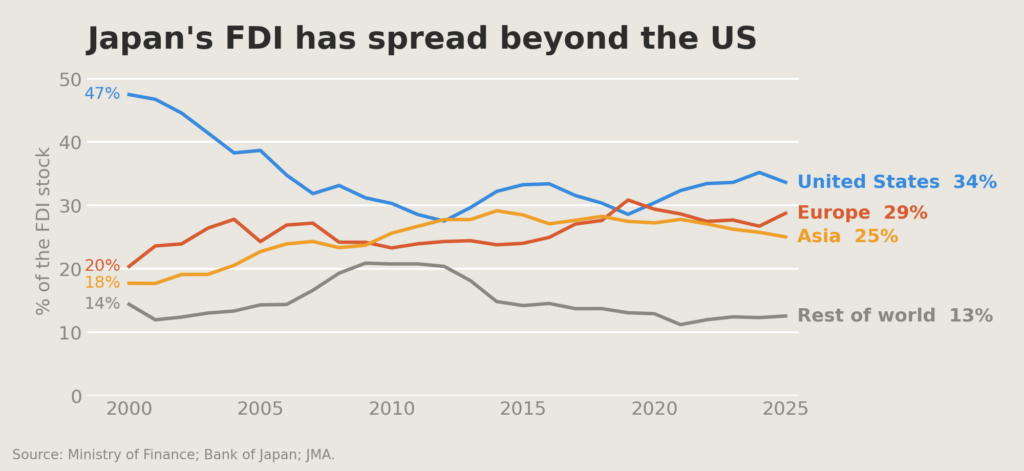
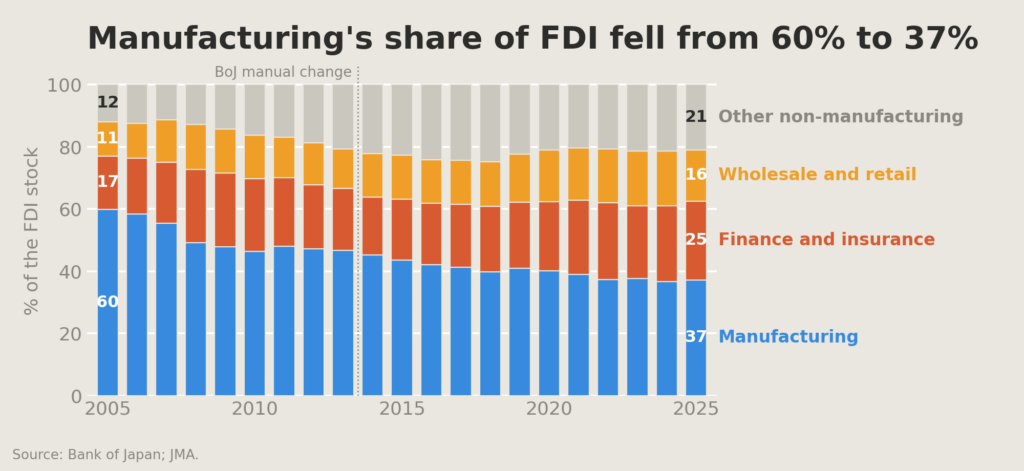
By industry composition and by destination compositions changed over time. Manufacturing’s share of the FDIstock had fallen to 37% by 2025, giving Japan’s FDI more breadth. By destination, we are seeing a revival of FDI toward the United States. It accounted for 34% of the stock in 2025, Europe 29% and Asia 25% (see earlier chart 3).
Thus, after decades of overseas investment, Japan’s FDI stock is now large enough that its earnings are sufficient to finance new investment abroad, at least for now. In the next section, I consider whether this will continue, and in particular whether Japanese companies may bring an even larger share of their overseas earnings back to Japan, given the weak yen, higher borrowing costs in yen and possibly better investment opportunities at home.
The weak yen has slowed offshoring, not reversed it
The real depreciation of the yen over the past 15 years made production in Japan more competitive. There is some evidence that manufacturers are considering bringing production back to Japan. The 2023 manufacturingwhite paper found more firms shifting production back from China than moving there, and they named the weak yen as one reason. We see some signs of reshoring. Japanese manufacturers’ overseas production ratio rose from 18.0% in FY2011 to 27.2% in FY2023, but it may have started to decline or at least stabilize. The ratio fell to 26.7% in FY2024. A Cabinet Office survey of listed manufacturers puts the ratio at 24.5% in FY2025, and their plan for FY2030 is broadly unchanged at 24.7%. The weak yen seems to have stabilized the wave of offshoring, but I see no firm evidence of a move back onshore yet.
Domestic investment has grown slowly despite the weak yen
There are tentative signs that domestic capital spending is starting to grow again. For three decades it grew at a very low speed. In real terms, private business investment rose only 26% between FY1997 and FY2025, less than 1% a year. In comparison, capital spending grew by about 4% a year on average in the United States. In my view, a weak currency is only one of the factors manufacturers weigh in designing their global production chains. The weak yen makes production in Japan competitive today, but they have also seen the exchange rate swing violently within short periods. Japan also has a shrinking population problem. It started to address it by opening a door to immigration, but the door is only tentatively open. Overall, my view is that the weak yen alone is unlikely to give Japan Inc. sufficient incentive to bring its capital back to Japan and to the yen.
Economic security is bringing some production home
The weak yen and non-economic geopolitical factors do point to a halt in Japan’s four-decade offshoring trend, although it is a stabilization, rather than an economy-wide reversal of past offshoring. Japan Inc. will continue to invest more abroad, rather than within its borders. Given the sizable growth in the stock of cumulative FDI, Japan Inc. no longer needs to convert yen into overseas currency to keep investing abroad though. Net of dividends and interest paid home, Japan’s FDI sold about ¥5 trillion of yen a year, or about 1% of GDP, on average in the 2010s; since 2022 the net flow has been close to zero. There is also an interesting development in an effort to allow more share-exchange based M&A for cross-border deals that will further reduce the need for Japanese companies to spend their yen to purchase overseas assets. In my view, Japan Inc.’s FDI is no longer a factor to drive the yen weaker.
Preliminary determination of Anti-Dumping Duty Investigation of Nickel-added cold-rolled stainless steel coil, sheet, and strip originating in the People’s Republic of China and the Separate Customs Territory of Taiwan, Penghu, Kinmen, and Matsu
Note: An alloy steel containing 10.5% or more of chromium and containing by weight more than 0.6% nickel. The characteristics of this product are that it combines corrosion resistance, the functionality of steel, and a beautiful and clean design by manufacturing methods. Also, it is used in various fields of demand.
MOF and METI will continue the investigation in accordance with the provisions of the international rules under the WTO Agreements and related domestic laws and regulations, providing the interested parties with an appropriate opportunity to present evidence and express their views relating to the preliminary determination.
Following the further investigation, the Government of Japan will determine whether or not the product has been imported into Japan at dumpedprices and if such dumpedimports have caused material injury to the domestic industry, and make a decision whether or not to impose a definitive anti-dumpingduty on the product.
The interim report on preliminary determination offers details of the investigation.
Extension of the Period of Investigation of Nickel-added cold-rolled stainless steel coil, sheet and strip originating in the People’s Republic of China and the Separate Customs Territory of Taiwan, Penghu, Kinmen, and Matsu
Note: An alloy steel containing 10.5% or more of chromium and containing by weight more than 0.6% nickel. The characteristics of this product are that it combines corrosion resistance, the functionality of steel, and a beautiful and clean design by manufacturing methods. Also, it is used in various fields of demand.
MOF and METI have been conducting the investigation since July 22, 2025. The investigation was to be concluded within one year, but the period can be extended by six months at most if it is found necessary for special reasons.
The year 1900 was a wonderful one, when men were proud to be middle-class, and to be Europeans. The fate of the whole world was decided around green baize-covered tables in London, Paris or Berlin. Rubber trees from the Amazons were shipped to Malaya, the vast coal seams of the Upper Hwang-Ho were being exploited at the expense of the wretched labourers, and in the north of the Upper Vaal a mining city sprang up in a few short weeks. Mobilized by steam, the planet’s riches were being shifted ‘from one side of the world to the other’, to quote Le Bateau Ivre, on orders flashed by telegraph in two or three minutes. Decisions reached by boards of directors in London, Paris or Berlin affected the lives of millions of human beings who did not suspect that their right to happiness depended on quotations scribbled on blackboards in three noisy exchanges built like temples, in which raged the battles of unbridled financial ambition. Not a single detail escaped the notice of Europe’s financial capitals: they fixed the price of a tram ticket in Rio de Janeiro, and the working hours of a coolie in Hong Kong. So much power had never before been concentrated in so few hands within so small an area of the globe. It was the age of triumph of the Europeanmiddle classes.
This gives us the theme of anxiety over national destiny and trajectory, which currently preoccupies the American mind.
In the second book, this antagonism question involves real and imaginary threats, and all of these anxieties and antagonisms are related. The masterpiece series, Downton Abbey, depicts a scene that takes place in the garden, where the Lord announces that they are at war with Germany, and his audience is perplexed, thinking, “How can we be at war? Germany is our biggest trading partner.” This teaches us that wars and the antagonisms that precede them are not solely based on rational factors like trade volumes.
Let us turn our attention to China. We are all aware, however vaguely, of the Chinese Exclusion Act of 1882. In the recent PBS television series, American Masters, the episode “Tyrus” (season 31, episode 7, aired September 8, 2017) has the artist Tyrus Wong recounting the story of his father, with whom he immigrated to California in 1920 at the age of 9. It is hard for us to believe that, as people of Chinese descent, they were forbidden from owning property outside of Chinatown. He describes his struggle with the hassles of overt racism. He did not gain his American citizenship until 1946, after the act was repealed. He came to fame with Disney’s Bambi, where he was the film’s lead artist.
“…But all the people who live in the little shipping and trading towns along the coast are immigrants from far away, who care little about the Kashubian hinterland because there’s nothing there for them, their concerns are elsewhere. What concerns them is where their trade is, and since they trade with the whole world and are in communication with the whole world, you find people among them from all corners of the globe. Which goes for Kessin too, backwater though it is.”
“But this is delightful, Geert. You keep calling it a backwater, but now, if you haven’t been exaggerating, I find that it’s a completely new world. All sorts of exotic things. Isn’t that right? That’s what you meant, isn’t it?”
He nodded.
“A whole world, I say, with perhaps a Negro or a Turk, or perhaps even a Chinaman.”
“A Chinaman too. What a good guess. We may still have one, we certainly did have; he’s dead now, buried in a little plot with a railing round it next to the churchyard. If you’re not afraid I’ll show you his grave sometime. It’s in the dunes with just some marram grass round it and a little immortelle here and there, and the sound of the sea all the time. It’s very beautiful and very eerie.”
“Yes, eerie — I would like to know more about it. Or maybe rather not, I invariably start imagining things and then I have dreams, and I don’t want to see a Chinaman approaching my bed tonight when I hope I’ll be sleeping soundly.”
“Well, he won’t.”
“Well, he won’t. Listen to that. How odd it sounds, as if it were somehow possible. You’re trying to make Kessin interesting for me, but you’re rather overdoing it. Are there many foreigners like that in Kessin?”
“A great many. The whole town consists of foreigners like that, people whose parents or grandparents lived somewhere else altogether.”
“How very peculiar. Tell me more, please. But nothing sinister. A Chinaman, I think, is always a bit sinister.”
Notice the quote, “…I don’t want to see a Chinaman approaching my bed tonight when I hope I’ll be sleeping soundly.” This character echoes similar sentiments several more times above.
This “othering” of the Chinese in the novel continues:
Innstetten laughed. “We’re seventy miles further north than Hohen-Cremmen here and you have to wait a while for the first polar bear. I think you’re feeling the strain of the long journey, what with the St. Privat panorama and the story of the Chinaman and everything?”
“You didn’t tell me any story.”
“No, I just referred to him. But the mere mention of a Chinaman is a story in itself…”
“Oh, some nonsense: an old ship’s captain with a granddaughter or a niece who disappeared one fine day, and then a Chinaman, who may have been her lover, and in the hallway there was a little shark and a crocodile, both suspended on strings and always in motion. Makes a marvellous story, but not now. There are all kinds of other things flitting through my mind.”
All of this global antagonism-watching and paranoia is disconcertingly related to our current situation. Donald Trump and the Republicans are essentially entrepreneurs of hatred. As is widely misattributed to Mark Twain, “history doesn’t repeat itself, but it often rhymes.”
At the same time, economists have been documenting the loss of work opportunities and earning power by workers without college degrees as manufacturingemployment has declined. In 2013, David Autor, David Dorn, and Gordon Hanson published a study that estimated the labor market impacts resulting from increased trade competition following China’s entrance into the World Trade Organization, an effect often referred to as the “China shock.” Dozens of studies have since used the regional variation in job and income losses caused by the China shock to measure the adverse impacts of job displacement on family structures, crime, health, and other social indicators. Some supporters of industrial subsidies and higher tariffs have expressed the hope that these dynamics can be put into reverse.
Robert Orttung, Debra Javeline, Graeme Robertson, Richard Arnold, Andrew Barnes, Edward Holland, Mikhail Troitskiy, Judyth Twigg, and Susanne Wengle argue that the renewed U.S.–Russia alignment under Trump and Putin prioritizes fossil fuel development over climate action, and undermines international climate negotiations.
In a statement to The Kyiv Independent, Peter Rutland echoes the contrast between the West’s diplomatic quarantine of Russia and the possibility of implementing policies without its permission, articulating how differing attitudes between Europe and Putin discourage any kind of escalation. In her recent article, Margarita Zavadskaya explores the “White Coat” narrative, explaining the origin and manipulation of Russian attitudes towards those who have left.
In a recent interview, Volodymyr Dubovyk explains why he believes Putin “wins” the Alaska summit, sharing his perspective on the meeting’s implications and concluding that the dynamics of peace negotiations shift somewhat. Richard Arnold marks the Donbas’ significance, stating that Russian control of the “Fortress Belt” enables havoc on all areas to the west.
Ryhor Nizknikau speaks with TVP World, interpreting the significance of Ukrainian Parliamentary Speaker Parubiy’s assassination. Tymofii Brik’s recent study, together with Oleksii Sereda, Anna Kokoba, and Alina Shmaliuk, appears in Vox Ukraine, covering the participants and reasoning behind the protest against the bill to limit SAPO and NABU’s independence.
In the context of Russia’s recent nuclear developments near the Pan’kovo testing range, Pavel Podvig comments that “Skyfall”, the new weapon’s NATO nickname, has likely undergonetesting already. During an interview withDW News, Mikhail Alekseev addresses the goals pursued by the Sino-Russian partnership, which range from the tangible benefits of constructing gas infrastructure to the more ideological advantage of presenting an alternative to the U.S.-led world order.
Although previous studies suggest anthropogenic forcing may influence extreme precipitationprobability, few have specifically investigated the human influence on moisture transport. Here, we leverage the 2023 record-breaking summer precipitation in Northern China (NC) to address this gap. Combining station observation with Coupled Model Intercomparison Project Phase 6 (CMIP6) model outputs, we demonstrate that the 2023-like heavy precipitation event was exacerbated by anthropogenic enhanced moisture transport. External forcing increased the probability of extreme southeasterly moisture transport by approximately 1.3 (90% confidence interval: 1.0–1.8) times. Moreover, the total anthropogenic forcing likely increased the probability of similar precipitation events at least 1.7 times (1.0–3.1), with both greenhouse gases and anthropogenic aerosols contributing positively. As greenhouse gases concentrations rise and anthropogenic warming intensifies, the frequency of similar extreme precipitation events in NC is projected to increase further.
The extent of human influence on moisture transport and consequent heavy precipitation remains a critical research question. While anthropogenic contributions to precipitation extremes are increasingly recognized, studies specifically addressing human-induced changes in moisture transport remain limited. The record-breaking summer precipitation in Northern China (NC) during 2023 provides a salient case study. This extreme event was fueled by substantial moisture transport from the southeast into NC, driven by TyphoonsDoksuri and Khanun. Attribution analyses indicate that both greenhouse gas and anthropogenic aerosol emissions likely increased the probability of similar heavy precipitation events and associated moisture transport patterns. Such events are projected to become more frequent with continued anthropogenic warming. These findings demonstrate that human activities significantly influence moisture transport pathways and consequently modulate extreme precipitation occurrence in NC, deepening our understanding of the physical mechanisms underlying these events.
Stone fruit production in Australia is forecast to decline in marketing year (MY) 2025/26, primarily due to the Bureau of Meteorology’s (BOM) projection of a wetter-than-average spring. If realized, these conditions are expected to negatively affect both yields and fruit quality. Cherry production is forecast to fall by ten percent, while peach and nectarine production is expected to drop by seven percent. Growing conditions to date have been favorable, with excellent winter chill hours supporting strong bud burst and production potential. However, the anticipated shift to wet spring weather is likely to undermine these early-season advantages. As a result, cherryexports are forecast to decrease by nine percent and peach and nectarineexports by seven percent. Imports, though starting from a low base, are projected to rise modestly in MY 2025/26.
Post projects exports of Chileancherries to grow significantly in the coming years, driven by strong international demand, particularly from China. Post estimates cherry production in marketing year (MY) 2024/25 to reach 730,000 metric tons (MT), a 6.7 increase over MY 2024/25. Chileancherryexports will increase by 7.2 percent reaching 670,000 MT. In MY 2024/25, Post estimates nectarine and peach production to total 205,000 MT, a 3.4 percent increase over MY 2024/25. Peach and nectarine exports will increase by 3.4 percent totaling 146,000 metric tons. This growth reflects the continued expansion of nectarine planting, which offsets the decline in fresh peach area planted.
China: Call for Domestic Comments on 30 National Food Safety Standards
On August 1, 2025, the Chinese government announced a public comment period for 30 national food safety standards, open until September 26, 2025, via the national standards management system. The standards have not yet been notified to the WTO. This report includes an unofficial translation of the announcement and the list of standards, and stakeholders are advised to review the regulations for potential market or regulatory impacts.
China: New CCP Regulation Expands Anti-Corruption and Frugality Measures
On May 18, 2025, the Chinese Communist Party and State Council issued a revised regulation on “Strict Economy and Opposing Waste by Party and Government Organs.” The regulation bans drinking alcohol at public receptions and events and discourages other forms of consumption that could be seen as extravagant. The FAS China offices are monitoring the potential impact on high-value U.S.agriculturalproducts.
China: Revised National Food Safety Standard for Paddy Rice Notified
On July 25, 2025, China notified a National Food Safety Standard for Paddy Rice to the WTO under G/TBT/N/CHN/2091. This national food safety standard includes mandatory requirements for quality, testing, inspection, packaging, and labeling of domestic and imported commercial paddy rice. This report provides an unofficial translation of the notified standard. Comments may be submitted to the China’s TBT National Notification and Enquiry Center at tbt@customs.gov.cn until August 24, 2025.
Japan’s fresh cherry production for the 2025/26 marketing year (MY) is projected to be 12,500 tons. This forecast is a result of production losses caused by high temperatures during the pollination period in the country’s largest cherry-producing region. While this represents an 8.7 percent increase compared to the previous year’s historically poor harvest, it is expected to be a low yield year with a 25 percent decrease from the average production year. Due to the poor domestic production, demand for U.S.cherries is expected to remain strong for the 2025/26 MY, continuing the trend from the previous year. For peach production in Japan, the absolute number of fruits is anticipated to be equivalent to the previous year; however, the total production volume by weight is forecasted to decrease by approximately 10 percent because of high temperatures and low rainfall during the critical fruit growing period.
Nicaragua’s peanutfarmers are expected to reduce harvested areas by at least five percent in marketing year (MY) 2025/26 in anticipation of lower prices due to increased Brazilianpeanut production. FASManagua expects farmers to be more rigorous in selecting production areas based on historical yields in MY 2025/26, excluding marginal lands with less fertile soil. Even with fluctuating marketprices and adjustments to planted areas, Nicaragua is expected to remain a stable peanut producer in the region, with exports of shelled peanuts exceeding 70,000 metric tons annually.