Japan-Watching: Machinery Orders in August, 2026

[from Japan’s Cabinet Office (内閣府) Economic and Social Research]

Results

  1. The total value of machinery orders received by 280 manufacturers operating in Japan decreased by 3.7% in August from the previous month on a seasonally adjusted basis.
  2. Private-sector machinery orders, excluding volatile ones for ships and those from electric power companies, increased a seasonally adjusted by 5.2% in August.

Percentage change from previous quarter (month)

(%)

2025
Jul-Sep
Oct-Dec2026
Jan-Mar
Apr-JunJul-Sep
(forecast)
2026
May
JunJulAug
Total3.510.210.311.3-0.19.50.4-5.5-3.7
private sector-1.36.22.614.6-3.837.4-26.01.5-4.2
(exc. volatile orders)-1.06.66.40.24.9-12.49.7-3.75.2
manufacturing5.3-0.810.0-1.34.0-14.919.9-1.01.6
non-manufacturing (exc. volatile orders)-4.411.36.2-2.35.9-9.34.5-2.62.9
governments-14.757.7-21.3-17.828.5-5.010.5-9.2-6.1
from overseas14.53.631.010.41.3-4.419.9-8.2-7.7
through agencies0.32.64.86.711.1-5.87.21.3-6.3

Note

  1. Seasonally adjusted series. As all series are seasonally adjusted individually, a sum of seasonally adjusted individual/component series does not equal to seasonally adjusted totals.
  2. Volatile orders: Orders for ships and those from electric power companies.

References

Chart 1: Total Value of Machinery Orders
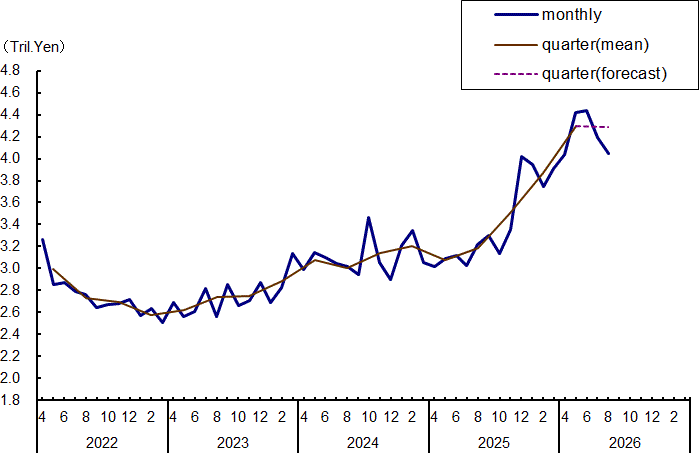
Chart 2: Private Sector (excluding volatile orders)
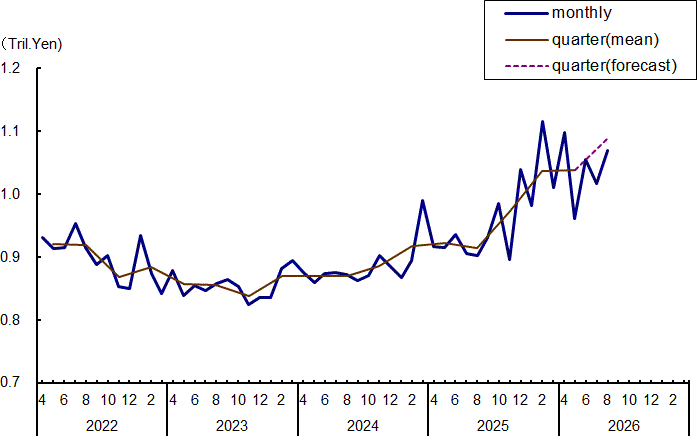
Table 1: Machinery Orders by Sectors

(billion Yen %)

2025
Jul-Sep
Oct-Dec2026
Jan-Mar
Apr-JunJul-Sep
(forecast)
2026
May
JunJulAug
Total9,543.6
(3.5)
[6.1]
10,514.8
(10.2)
[13.5]
11,593.0
(10.3)
[23.5]
12,900.0
(11.3)
[39.4]
12,881.0
(-0.1)
[36.7]
4,422.2
(9.5)
[40.4]
4,439.0
(0.4)
[43.7]
4,195.7
(-5.5)
[36.8]
4,041.9
(-3.7)
[26.1]
private sector3,370.6
(-1.3)
[12.9]
3,580.8
(6.2)
[11.2]
3,674.3
(2.6)
[11.6]
4,210.8
(14.6)
[22.4]
4,051.2
(-3.8)
[21.0]
1,706.2
(37.4)
[40.8]
1,262.6
(-26.0)
[12.7]
1,281.3
(1.5)
[10.3]
1,226.9
(-4.2)
[13.8]
(exc. volatile orders)2,741.4
(-1.0)
[6.6]
2,921.6
(6.6)
[8.1]
3,109.2
(6.4)
[12.6]
3,116.2
(0.2)
[10.8]
3,268.6
(4.9)
[19.9]
962.0
(-12.4)
[-1.9]
1,055.8
(9.7)
[16.9]
1,016.9
(-3.7)
[11.2]
1,069.8
(5.2)
[18.6]
manufacturing1,369.3
(5.3)
[14.0]
1,357.8
(-0.8)
[3.9]
1,493.7
(10.0)
[14.8]
1,474.8
(-1.3)
[12.5]
1,534.0
(4.0)
[12.6]
437.2
(-14.9)
[-4.7]
524.1
(19.9)
[27.4]
518.6
(-1.0)
[20.5]
527.0
(1.6)
[23.5]
non-manufacturing (exc. volatile orders)1,409.5
(-4.4)
[1.5]
1,568.1
(11.3)
[12.0]
1,666.0
(62)
[12.5]
1,627.2
(-2.3)
[9.6]
1,723.8
(5.9)
[25.6]
516.9
(-9.3)
[0.9]
540.2
(4.5)
[8.5]
525.9
(-2.6)
[5.7]
541.3
(2.9)
[10.8]
governments1,159.4
(-14.7)
[-22.7]
1,828.8
(57.7)
[-4.4]
1,439.2
(-21.3)
[-18.6]
1,183.4
(-17.8)
[-13.2]
1,521.2
(28.5)
[33.4]
374.7
(-5.0)
[-24.9]
414.2
(10.5)
[-7.3]
376.2
(-9.2)
[-25.8]
353.3
(-6.1)
[8.1]
from overseas4,624.3
(14.5)
[10.3]
4,789.4
(3.6)
[22.3]
6,275.3
(31.0)
[57.2]
6.928.8
(10.4)
[71.1]
7.016.5
(1.3)
[55.6]
2,135.5
(-4.4)
[62.2]
2,559.6
(19.9)
[83.8]
2,350.2
(-8.2)
[81.5]
2,168.7
(-7.7)
[36.9]
through agencies410.6
(0.3)
[9.1]
421.3
(2.6)
[13.1]
441.3
(4.8)
[18.7]
470.7
(6.7)
[13.7]
522.7
(11.1)
[24.7]
150.2
(-5.8)
[0.4]
161.0
(7.2)
[16.1]
163.1
(1.3)
[12.1]
152.8
(-6.3)
[17.4]

Notes

  1. Seasonally adjusted series. As all series are seasonally adjusted individually, a sum of seasonally adjusted individual/component series does not equal to seasonally adjusted totals.
  2. Figures in () represent the percentage change from the previous quarter (month). Figures in [] are the percentage change from the corresponding quarter (month) of the previous year in original series.
  3. Volatile orders: Orders for ships and those from electric power companies.

Table 2:

2025
Jul-Sep
Oct-Dec2026
Jan-Mar
Apr-Jun2026
May
JunJulAug
Manufacturing5.3-0.810.0-1.3-14.919.9-1.01.6
1. Foods and beverages-72-0.911.0-2.1-13.227.3-11.60.1
2. Textile mill products12.3-3.1-12.526.13.8-14.3-7.0-18.6
3. Pulp, paper and paper products5.09.4-7.9-2.514.35.465.2-33.2
4. Chemical and chemical products9.5-37.542.7-21.719.239.0-12.0-11.5
5. Petroleum and coal products-36.366.7-53.4-2.57.132.94.819.6
6. Ceramic, stone and clay products31.2-7.19.515.7-13.33.26.1-23.0
7. Iron and steel22.6-11.521.5-21.5-5.3-10.85.8-36.3
8. Non-ferrous metals-5.2-0.226.1-16.019.5225.3-82.2132.6
9. Fabricated metal products-6.9-5.716.448.313.8-46.113.2-10.7
10. General-purpose and production machinery7.1-4.111.0-0.8-10.318.9-1.49.3
11. Business-oriented machinery-11.52.48.219.9-14.33.2-7.2-5.7
12. Electrical machinery-6.310.3-3.020.2-12.02.246.1-5.9
13. Information and communication electronics22.3-8.611.915.1-23.629.74.713.0
14. Automobiles, parts and accessories3.8-0.813.6-0.57.46.91.513.1
15. Ship building18.8-25.765.73.9-80.594.988.9-41.0
16. Other transport equipment-4.55.936.4-11.467.14.7-41.443.7
17. Other manufacturing-1.59.9-4.2-4.6-10.2-0.6-1.36.1
Non-manufacturing-2.410.3-1.524.168.0-40.40.8-5.7
18. Agriculture, forestry and fishing10.412.20.5-23.2-24.233.011.0-4.0
19. Mining, quarrying of stone and gravel-8.4-6.93.0-24.120.723.76.725.0
20. Construction-3.18.34.09.31.6-8.55.8-17.2
21. Electricity supply1.0-1.50.291.7342.9-75.134.2-34.9
22. Transportation and postal activities7.00.1-15.85.5-23.38.93.3-13.9
23. Telecommunications-16.818.8-0.814.6-7.522.3-23.216.9
24. Wholesale and retail trade4.8-2.44.13.4-3.1-3.1-3.929.2
25. Finance and insurance-6.39.38.5-2.7-10.617.9-6.80.2
26. Real estate-20.94.714.139.7-69.3253.1-26.40.7
27. Information services-6.47.725.1-11.8-8.916.0-16.97.9
28. Goods leasing14.3-12.810.1-16.6-18.6-0.9-6.8136.0
29. Other non-manufacturing-2.541.5-2.8-5.234.9-26.620.1-28.0

Note

Percentage change from previous quarter (month) in seasonally adjusted series.
Japan-Watching: BoJ’s Koeda Points to a Longer Hiking Cycle

Her potential-growth example implies a neutral rate around 2.8%, above the Bank’s published 2.5% ceiling and well above today’s 1.25% policy rate.

[by OKUBO Takuji]

Key Takeaways

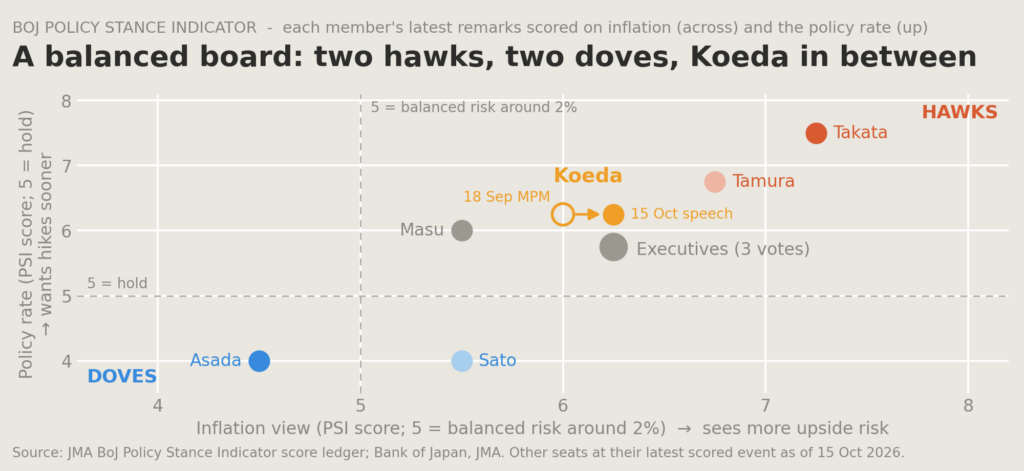
  • Koeda, probably the most influential swing vote on the board, seemed slightly more hawkish in her speech on October 15. She stopped just short of calling the 2% target achieved.
  • Her conceptual example of a neutral rate, potential growth plus 2%, points to a neutral rate well above 2%. While she is not in a hurry to push for hikes as the two hawks are, she seems open to a protracted hiking cycle.
  • I continue to think an October hike is out of the question. Koeda’s openness to a hike marginally raises the possibility of a December hike. I still consider it highly unlikely, though.

Why Koeda matters

On October 15, 2026, KOEDA Junko [小枝淳子] made her 3rd speech since she joined the BoJ policy board in 2025. She is an ex-IMF academic and yield curve specialist. She is probably the most important and influential swing vote in the current BoJ board. In her speech [archived PDF] and the following press conference (Japan Macro Advisors’ unofficial transcript), she sounded more open to continued rate increases than the three BoJ executives, although she was careful not to give any indication of the timing of the next move.

The board is balanced at both ends

As you can see in chart 1, the board is evenly balanced with two hawks at top-right and two doves at bottom-left (if you are unfamiliar with the BoJ-Policy Stance Indicator framework, please see the Japan Macro Advisors primer). That leaves KOEDA Junko [小枝 淳子] and MASU Kazuyuki [増 一行] between the two ends, sitting with the three BoJ executives: the Governor and two Deputy Governors. As BoJ executives tend to vote together, Koeda and Masu cast critical swing votes.

Chart 1

Koeda sounded more hawkish than before

In her speech [archived PDF] and the following press conference (see the Japan Macro Advisors unofficial transcript), she seemed slightly more hawkish than I anticipated. Koeda judges trend inflation to be already about 2% overall and increasingly well-anchored. She stopped just short of saying the 2% target has been achieved. She said:

“For about a year now I have described underlying inflation as roughly 2% on the whole, and I have kept checking how firmly it is taking hold. On the CPI, as I noted at Chart 11, broad-based price increases have continued for several years, and the distribution of year-on-year changes by item also suggests that this is becoming established. Wages, too, have shown stable increases overall. For these reasons, I think Japan’s inflation is becoming more persistently entrenched than before.” [Kumamoto speech, 15 October 2026, Japan Macro Advisors translation]

Koeda also offered a simplified concept of the neutral rate as the potential growth rate plus the 2% inflation target. As the Bank’s latest potential-growth estimate is about 0.8%, this could put the nominal neutral rate at 2.8%, exceeding the top of the Bank’s published nominal range of 1.1–2.5%. She did offer another version that put the neutral rate at a lower level, but it was clear that she wanted to give a higher version of a potential neutral rate.

To be clear, she did not endorse 2.8% as a policy-rate destination. At the press conference, she said the potential-growth rule does not always hold and declined to give a point estimate. But her intention was most likely to nudge the neutral rate range higher.

Koeda was clear in her message that she is open to a rate hike. She said: “I do not think we need to be overly cautious about raising rates.” [speech, Japan Macro Advisors translation]

But she was quite evasive regarding the timing of the next hike. In the press conference, reporters repeatedly asked for her view on a back-to-back rate hike, a veiled way of asking whether an October hike is possible. She was quite firm in repeating her stance that she does not have any particular pace in mind. This was an interesting contrast with Governor Ueda’s dismissive comment on the possibility of a successive or oversized rate hike (see the Japan Macro Advisors September 18 report). That does not mean she endorsed consecutive hikes. It means she left the option more open than Ueda did.

Conclusion: More open to multiple hikes

By choosing potential growth plus 2% as an example of the neutral rate, Koeda seems to be creating more space for the policy rate to eventually rise above 2%, in my view. In terms of the timing for the next hike, she was non-committal. I would still consider an October hike out of the question, but her non-committal attitude does marginally raise the possibility of a December hike, although I still consider it highly unlikely.

Japan Inc. Now Sells No Yen to Invest Abroad

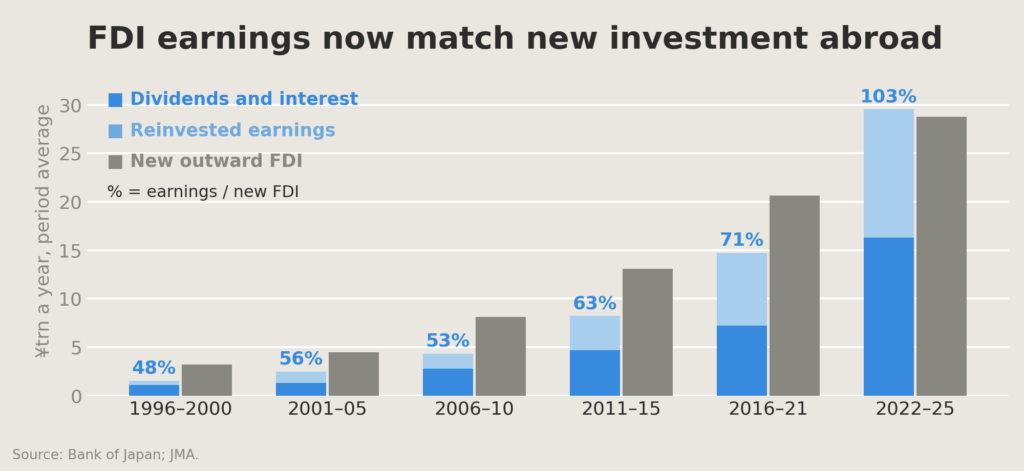
Earnings on Japan’s foreign direct investment (FDI) reached 103% of new FDI in 2022–25. With dividends and retained earnings counted together, Japan Inc. now needs to sell little yen to invest abroad.

[by OKUBO Takuji]

Key takeaways

  • Foreign affiliates now earn about as much as Japan invests abroad each year. Reinvested earnings, dividends and interest together reached 103% of new outward FDI in 2022–25, against 48% in 1996–2000.
  • Dividends from foreign affiliates account for a growing share of Japanese corporate profit. We estimate that foreign affiliates contributed 13.4% of Japan Inc.’s earnings in FY2025, up from 1.7% in FY1996.
  • Corporate investment abroad now involves little net yen selling. After dividends and interest paid home, the estimated outflow has been close to zero since 2022, down from about ¥5 trillion a year, or about 1% of GDP, on average in the 2010s.

Japan’s FDI stock now earns 103% of new investment

It is often said that Japan’s ageing population and slow growth give its companies too few investment opportunities at home. A Japanese government report in 2024 included the following passages.

“Japan’s ageing and shrinking population depresses expected demand at home. Expected returns remain higher abroad, so Japanese companies have accelerated outward direct investment” (my translation). — MATSUBAYASHI Yōichi [松林 洋一], MOF PRI, chapter 8, p.136.

“Companies invested abroad because they saw no promising investments in Japan; they are unlikely to bring back every return. On a cash-flow basis, the external balance is in deficit and is one factor behind the weak yen” (my translation). — KARAKAMA Daisuke [唐鎌 大輔], MOF PRI, chapter 10, pp.178 and 175.

However, my review of recent data shows that while their premise of low growth prospects in Japan is probably still right, the direct investment Japan has accumulated abroad has reached a level where it earns enough to cover Japan’s new investment abroad. This changes the exchange-rate implication even if Japan keeps investing abroad.

As chart 1 shows, earnings on the accumulated investment stock rose from 48% of new outward FDI in 1996–2000 to 103% in 2022–25.

Chart 1

Overseas affiliates pay interest and dividends to their parent companies in Japan. Those dividends have become a sizable part of corporate Japan’s income: we estimate that they made up 13.4% of Japanese corporate profit in FY2025, up from 1.7% in FY1996.

When foreign affiliates retain their earnings on their balance sheets, Japan’s balance of payments statistics record them as FDI from Japan, even though no money crosses the border. While the companies receiving FDI dividends and the companies paying for new FDI are not necessarily the same, Japan Inc. as a whole is now financing its FDI almost entirely from the earnings of its overseas affiliates. At the current level of FDI, little new yen needs to be converted into foreign currencies as Japan goes about investing abroad.

In the rest of this report, I explain how foreign direct investment by Japanese companies evolved, and its near-term outlook. This report is the third in a series on the yen repatriation theme that I have published over the past few weeks, following “Yen Repatriation Starts with the Whale”, on capital flows through Japan’s national pension funds, and “Mrs Watanabe No More”, on Japanese households’ assets invested abroad.

A strong yen helped drive Japan’s first outward FDI boom

Japan’s outward investment was heavily restricted after WWII, requiring case-by-case permission from the government. Approvals became more and more automatic over the years until outward investment became “free in principle” in 1980. Trade friction with the US-led Japanese carmakers to restrain their exports from 1981, pushing them to build factories abroad. The rapid appreciation of the yen was also a factor. The yen strengthened from ¥242 per dollar before the Plaza Accord in September 1985 to ¥121 by the end of 1987. Japanese producers had to move lower value-added work abroad. The strong yen also gave Japanese financial institutions sizable purchasing power for a while, until the stock and property bubbles burst in 1990 and 1991.

All of these factors contributed to a rapid increase in outward FDI through the 1980s and 1990s (chart 2).

Chart 2

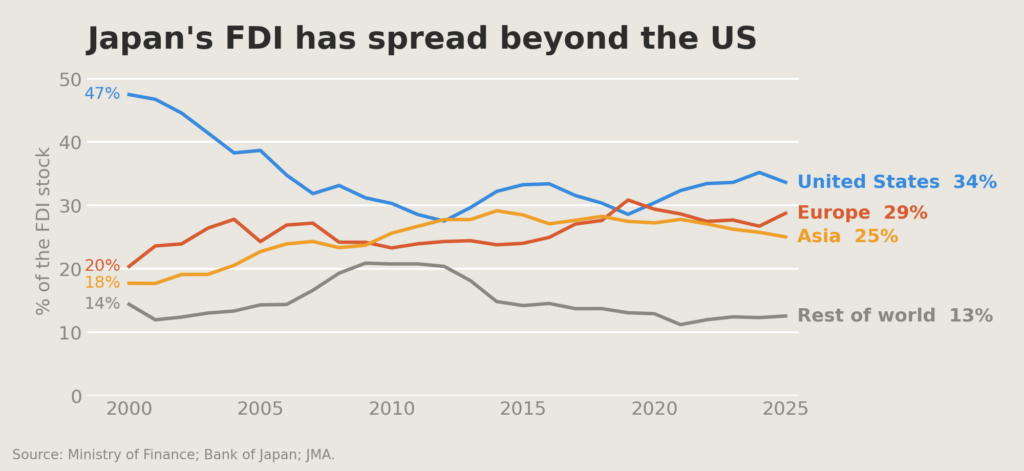
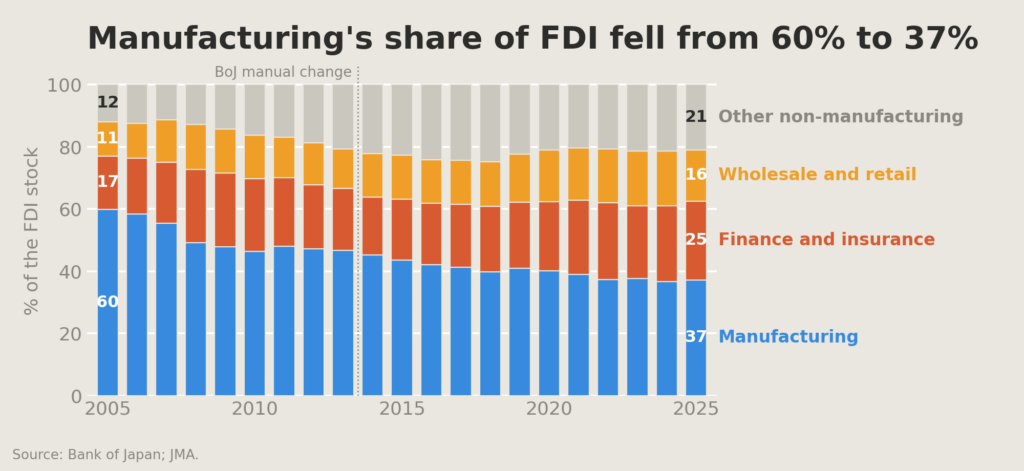
Even after the bubble burst, the strong yen kept pushing manufacturers to move abroad. In 2005, manufacturers accounted for 60% of the FDI stock. As Japanese manufacturers expanded their supply chains abroad, Asia’s share of outward FDI rose from about 12% in FY1986–90 to 19% in FY1995–99, and Asia held 23% of the FDI stock by 2005 (chart 3).

Chart 3

Japan’s outward FDI stock rose to 56% of GDP

The next phase was sustained by a different pressure. With weak growth and low interest rates at home, Japan Inc. kept investing abroad, across a broader range of industries. Between 1995 and 2025, the stock of FDI rose from 9% of Japan’s GDP to 58% (chart 4). In 2025, it is as large as about 38% of the private sector’s domestic fixed capital, on our estimate.

Chart 4

By industry composition and by destination compositions changed over time. Manufacturing’s share of the FDI stock had fallen to 37% by 2025, giving Japan’s FDI more breadth. By destination, we are seeing a revival of FDI toward the United States. It accounted for 34% of the stock in 2025, Europe 29% and Asia 25% (see earlier chart 3).

Thus, after decades of overseas investment, Japan’s FDI stock is now large enough that its earnings are sufficient to finance new investment abroad, at least for now. In the next section, I consider whether this will continue, and in particular whether Japanese companies may bring an even larger share of their overseas earnings back to Japan, given the weak yen, higher borrowing costs in yen and possibly better investment opportunities at home.

The weak yen has slowed offshoring, not reversed it

The real depreciation of the yen over the past 15 years made production in Japan more competitive. There is some evidence that manufacturers are considering bringing production back to Japan. The 2023 manufacturing white paper found more firms shifting production back from China than moving there, and they named the weak yen as one reason. We see some signs of reshoring. Japanese manufacturers’ overseas production ratio rose from 18.0% in FY2011 to 27.2% in FY2023, but it may have started to decline or at least stabilize. The ratio fell to 26.7% in FY2024. A Cabinet Office survey of listed manufacturers puts the ratio at 24.5% in FY2025, and their plan for FY2030 is broadly unchanged at 24.7%. The weak yen seems to have stabilized the wave of offshoring, but I see no firm evidence of a move back onshore yet.

Domestic investment has grown slowly despite the weak yen

There are tentative signs that domestic capital spending is starting to grow again. For three decades it grew at a very low speed. In real terms, private business investment rose only 26% between FY1997 and FY2025, less than 1% a year. In comparison, capital spending grew by about 4% a year on average in the United States. In my view, a weak currency is only one of the factors manufacturers weigh in designing their global production chains. The weak yen makes production in Japan competitive today, but they have also seen the exchange rate swing violently within short periods. Japan also has a shrinking population problem. It started to address it by opening a door to immigration, but the door is only tentatively open. Overall, my view is that the weak yen alone is unlikely to give Japan Inc. sufficient incentive to bring its capital back to Japan and to the yen.

Economic security is bringing some production home

The government is pushing harder than the currency, mostly in the name of economic security, even before the Takaichi government came along. The government currently has a ¥250 trillion domestic investment target for FY2040 and named AI and semiconductors among its 17 strategic fields. Semiconductors are where the money has gone furthest. In November 2024, under the Ishiba government, Japan committed more than ¥10 trillion of public support to AI and semiconductors by FY2030, aiming to draw more than ¥50 trillion of public and private investment over ten years. Japan managed to lure a TSMC plant to Japan, backed by a sizable subsidy. Rapidus, a government-supported Japanese semiconductor maker, has received a sizable subsidy and is building a factory in Hokkaido. Japan’s production of integrated circuits and discrete semiconductors rose from ¥2.7 trillion in 2019 to ¥4.1 trillion in 2025.

Under the name of economic security, the Japanese government is promoting other industries such as batteries, shipbuilding and pharmaceuticals. Defence spending adds to the push. Japan’s defence budget rose from about ¥5 trillion in FY2022 to ¥9.0 trillion in FY2026. Some defence contractors, such as Mitsubishi Heavy Industries, have doubled their defence revenue.

Japan’s industrial-policy record gives reason for caution

The Japanese government and the Ministry of Economy, Trade and Industry (METI), the key agency behind Japan’s industry policy, may claim some expertise in their industrial policies. Empirical studies in the past paint a poor track record, though. Rapidus, the most ambitious semiconductor project, has had no independent cost-benefit assessment (Negrine et al., 2025). While defence and economic security-driven policies have a different logic, I doubt that these industrial policies will succeed in bringing large-scale manufacturing investment back to Japan so long as macro factors such as Japan’s demography remain unfavourable.

FDI no longer appears to drive yen weakness

The weak yen and non-economic geopolitical factors do point to a halt in Japan’s four-decade offshoring trend, although it is a stabilization, rather than an economy-wide reversal of past offshoring. Japan Inc. will continue to invest more abroad, rather than within its borders. Given the sizable growth in the stock of cumulative FDI, Japan Inc. no longer needs to convert yen into overseas currency to keep investing abroad though. Net of dividends and interest paid home, Japan’s FDI sold about ¥5 trillion of yen a year, or about 1% of GDP, on average in the 2010s; since 2022 the net flow has been close to zero. There is also an interesting development in an effort to allow more share-exchange based M&A for cross-border deals that will further reduce the need for Japanese companies to spend their yen to purchase overseas assets. In my view, Japan Inc.’s FDI is no longer a factor to drive the yen weaker.

References

Can We Learn from Theologians in a Secular Age?

Let’s list some of the transitions from the pre-modern world:

Karl Barth attempts to establish a foundational explanation of the human body and soul without starting with a divine principle. He writes:

It is beyond our capacity to decide between flesh and Spirit. We can neither reject the one nor select the other. Nor are some small or large companies of men—in the Spirit, whilst others are—in the flesh. Should one claim he is competent to distinguish between those in the flesh and those in the Spirit, he thereby proclaims himself to be undoubtedly in the flesh. In time, it has already been decided that we are all in the flesh: in eternity, it has already been decided that we are all in the Spirit. We are rejected in the flesh, but elected in the Spirit. In the world of time and of men and of things we are condemned, but in the Kingdom of God we are justified. Here we are in death, there we are in life. Both decisions—rejection and election, condemnation and justification, death and life—form the foci of an ellipse, which approximate more and more closely to one another until they unite as the centre of one circle. The unity of both decisions—which is incapable of mathematical representation—is not the unity of an equilibrium, but of the infinite preeminence which the one has over the other, whereby time is swallowed up in eternity, and the flesh in the infinite victory of the Spirit.

Karl Barth, The Epistle to the Romans. Translated by Edwyn C. Hoskyns. Oxford University Press, 1968. pp. 284-285.

Barth seeks to visualize everything not as the fixed center of a circle with flesh and spirit orbiting, but rather as an ellipse with these things trying to become central. He stresses that an ellipse has two foci, rather than a circle’s singular center.

Barth wrote, “The body is totality of my existence in the flesh, in the world of time and things and men, the totality of my existence as ‘I’, as the man of this world encircled by all manner of concrete and conceivable possibilities.” (Ibid. pp. 289)

Some thinkers use “existentialization” to describe the type of concept in Barth’s statement. Barth also gives us another dimension of our situation when he wrote, “Caught up in the struggle for existence eating, drinking, sleeping, yes, above all, sleeping! marrying and giving in marriage—men stand midway between life and death. Immersed in the flux of time and history…” (Ibid. p. 89)

In his thinking, the previous framework is contained in the larger one: “Our life is confronted with a steep precipice, towering above us, hemming us in on every side, and on it are hewn the words: All things come to an end.” (Ibid. p. 170)

Think of the word matter as the root of materialism. In daily life, we ask ourselves, “Does it matter?” Contrast the realms of science and meaning. Barth attempted to connect these with divinity, which can still provide valuable insight in our secular world.

Japan-Watching: Yen Repatriation Starts with the Whale

GPIF, one of the largest national pension funds in the world, is likely to rebalance its assets from non-yen bonds to yen bonds, signaling a big turn in Japan’s cross-border capital flows.

[from Japan Macro Advisors, 10 September, 2026]

Key takeaways

  • In 2013, GPIF’s investment committee, chaired by UEDA Kazuo [植田和男], now the BoJ governor, saw a fair chance of a JGB crash within five to ten years. Its CEO priced the crash as the 10-year rising from 0.5% to 3%. Subsequently, GPIF cut its target weight for domestic bonds from 60% to 25% as an emergency measure against abnormally low yields.
  • The 10-year is now at 3%. On my replication of GPIF’s own allocation rule, a real return on JGBs near zero points to a 50% weight in domestic bonds, against 25% today. I expect GPIF to raise the weight, if it has not already started in the September quarter.
  • How GPIF decides its asset allocation and communicates it publicly is a very delicate and political issue. But regardless of how it communicates it, a change in asset allocation is inevitable. In my view, it signifies a big turn in Japan’s cross-border capital flows.

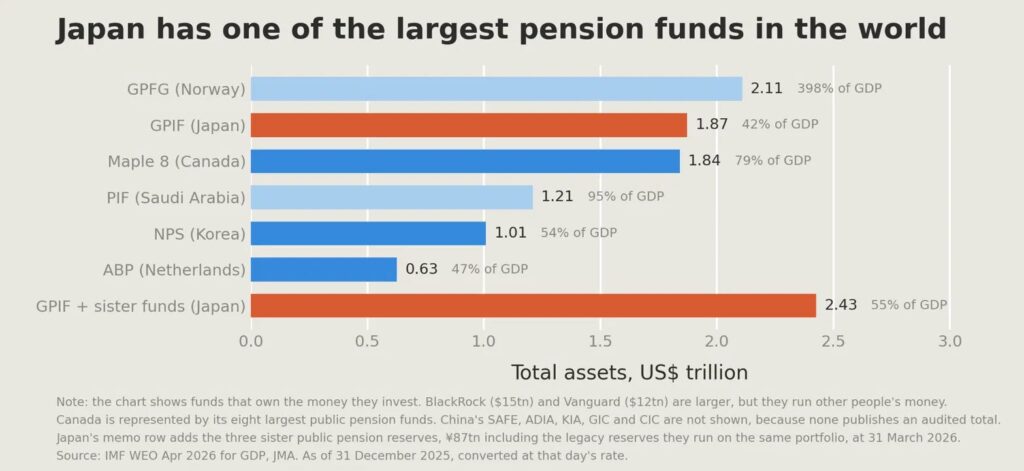
Japan has one of the Largest Pension Funds in the World

Japan has the second largest public pension fund in the world. Norway’s is the biggest, although it is not strictly a pension fund. Canada’s pension funds, when all eight of its variants are added together, come a close third.

Japan set up its first national pension fund in 1961 and it has since gone through various reforms and reorganization over the last 65 years. Its current form is called the Government Pension Investment Fund (GPIF). As explained in a later section, GPIF has a few siblings, and when we add them together, Japan’s public pension funds can be said to be the largest in the world.

Chart 1

GPIF used to invest most of its asset into JGBs

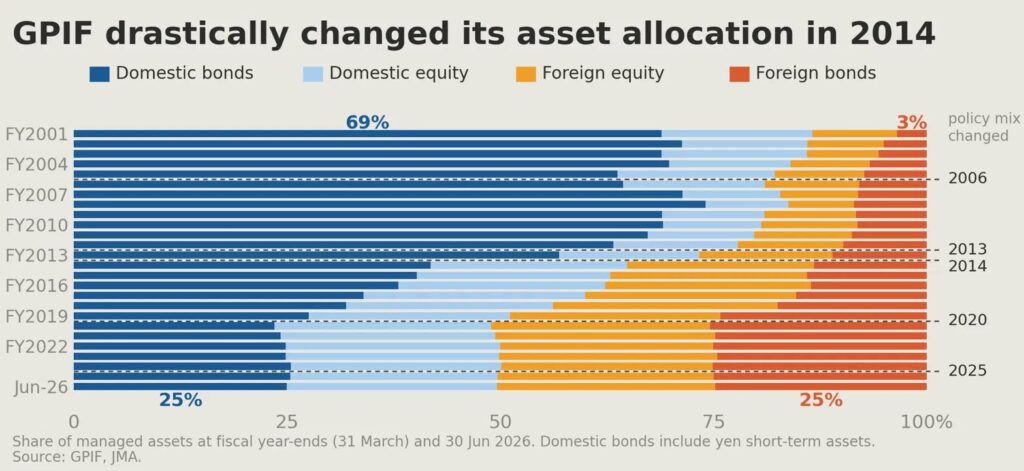
GPIF used to invest the majority of its fund as loans to the national government and into Japanese government bonds (JGBs). At the end of FY2012, 62% of its assets consisted of domestic bonds. However, in 2014 it went through a radical asset reallocation and the target weight for domestic bonds was reduced from 60% to 35%, and then further down to 25% in 2020. Its current target allocation is a clean four-way 25% split into domestic bonds, domestic equity, foreign equity and foreign bonds.

As one of the largest pension funds in the world, its asset allocations attract market attention and there is speculation that it is about to raise its allocation into domestic bonds. In my view, there is indeed a very high chance that GPIF will be raising its allocation into domestic bonds, if it has not already started to do so in the current quarter ending in September 2026.

Chart 2

UEDA in 2013 Saw a Bond Crash Coming

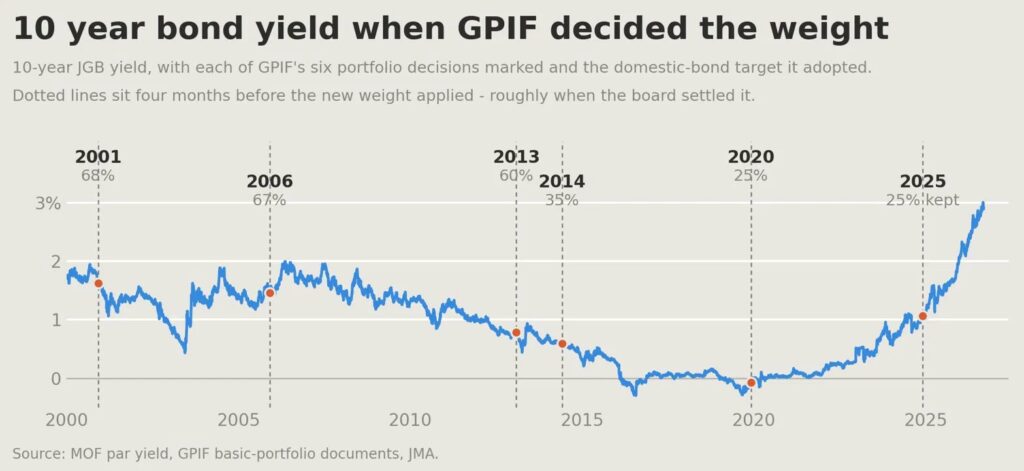
To understand why GPIF is highly likely to raise its allocation into domestic bonds, we need to go back in history to 2013. Why 2013? Of course, it is the year the Bank of Japan (BoJ) started its massive quantitative easing. The 10-year JGB yield started 2013 at 0.8% and it fell to 0.3% by the end of 2015 before briefly hitting a negative rate of -0.3% in 2016. If you were the chairperson of the GPIF investment committee, you would have been concerned about the wisdom of continuing to invest in JGBs at such a policy-driven low rate. The actual chairperson was UEDA Kazuo [植田和男], the current BoJ governor. In the minutes for October 2013, UEDA said, “I think there is a fair chance that bonds will crash at some point in the next five to ten years [unofficial translation].”

The minutes were released only seven years later; otherwise the use of the word “crash” would have been controversial.

GPIF CEO Priced the Crash at 3% in 2014. We Are There Now

If you read through the GPIF minutes between 2013 and 2014, you would see that GPIF officials were increasingly conscious of the precariousness of investing in JGBs. Long story short, as this process was highly political and a sensitive subject, they decided to radically lower the target allocation weight for JGBs to 35% in 2014, presented it as the result of a philosophical change in the way GPIF is managed and how the concept of “risk” should be considered. Investment in JGBs was no longer considered low risk in real terms. The asset allocation for domestic bonds was further lowered to 25% in 2020. The following is what MITANI Takahiro [三谷隆博], the GPIF CEO at the time and an ex-BoJ senior official, said in the October 2014 GPIF minutes.

“Yields are just under 0.5% now, so a move to near 3% would mean a loss of about ¥25 trillion. (…). So I think the clearest way to explain it is that reducing the weight on JGBs to some degree is simply unavoidable [unofficial translation]”

The 2014 cut in the weight was partly an emergency escape

As I wrote earlier, the radical asset reallocation in 2014 was part a shift in the concept of risk from “nominal” to “real”, so that JGB is no longer risk free assets. But the change was also at least partly an emergency measure to escape the abnormally low-yield environment. Then the next natural question is, now that the JGB yields are no longer abnormally low, what should happen to its asset allocation? Pensions are paid in yen, so long-duration Japanese government bonds are a natural match, while GPIF should also be holding some non-yen assets and equities to diversify its assets and protect the overall balance sheet from inflation. In the next section, I will show you a simplified replication of how GPIF decides its asset allocation and what GPIF’s asset allocation could be now that JGB yields are normal.

How GPIF decides its weights

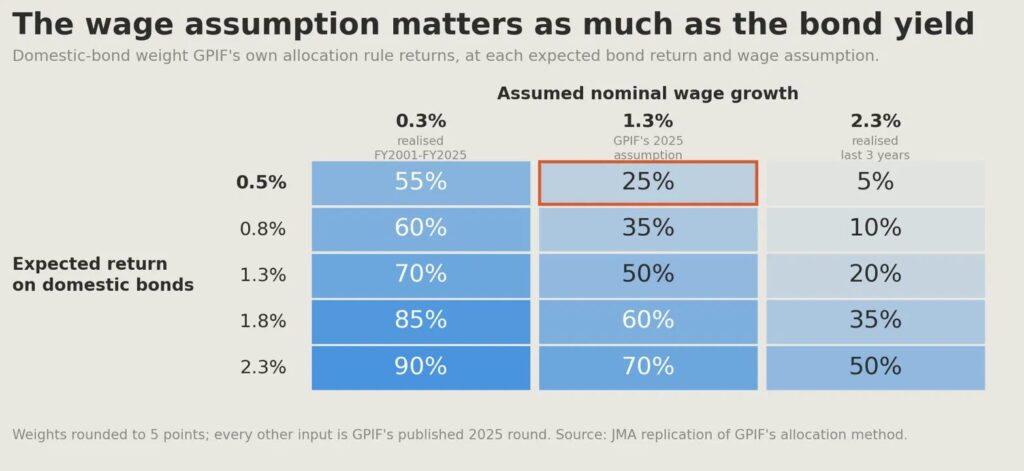
Put simply, GPIF’s target weights are the output of an optimizer with a few rules. Find the portfolio that, at the required real return, has the smallest average shortfall below wage growth in the years when it falls short, and round it to the nearest 5%.

When GPIF last decided to keep the current 25% weight for domestic bonds in 2025, JGBs were assumed to produce a nominal return of 0.5% against wage growth of 1.3%, so a real return of minus 0.8%. Exhibit 1 shows a simplified matrix of weights depending on expected nominal return on bonds and wage growth. The red box shows the assumption behind the 2025 weights decision mentioned above. If we use a higher wage growth assumption of 2.3%, an expected nominal return of 1.8% on bonds gives a weight of 35%. GPIF’s bond portfolio has an average maturity around 10 years, and the 10-year bond is yielding 3% now. A lot of thought and estimation is needed to form a view on the expected real return on domestic bonds, but in my view, it is clear that the minus 0.8% used in their last review is too low given where bond yields are.

Why GPIF kept the weight in 2025 and why circumstances changed

In late 2024 when the GPIF was reviewing the weight as part of its five-year plan, the BoJ was already in the process of exiting from QE and raising its policy rate. However, the JGB market was still in the process of adjustment and bond yields had a lot of room to rise. For example, the 10-year yield was 0.89% at the end of September 2024, rose to 2% by the end of 2025 and now, in September 2026, stands at 3%. You can understand why GPIF decided to keep its weight on domestic bonds unchanged as it would have incurred capital losses on bond purchases in 2025. But in my view, as I wrote in the report “The Long Climb in JGB Yields Is Nearly Over” [archived PDF], long bond yields are getting closer to a stability point. If the GPIF board shares my view, it is a good time to think about raising its target weight into domestic yen bonds.

The Whale Problem and the Washington Problem

How high should the new weight be for domestic bonds? The reality of determining appropriate weights and how to announce it is a lot harder than the simplified model I explained above. Other than forming a reasonable view on the expected real return on asset classes, there are a few factors that complicate the process.

Firstly, GPIF needs to think about how such an announcement would affect the market. GPIF is what financial market professionals call a whale, a massive investor whose investment decisions sway market prices. There is also a related argument that given the dominance of GPIF in the domestic market, GPIF should be increasing its asset weight abroad to reduce its impact on domestic asset markets.

Secondly, changing asset allocation weights carries political considerations. If GPIF decides to raise the target weight for domestic bonds, foreign bonds are the likely asset class whose weight will go down. More than 50% of its foreign bonds are in US dollars. With all the news circulating in the market now, Scott Bessent will not like a public announcement that one of the largest pension funds in the world is reducing its purchase of US treasuries. There are domestic political considerations as well, as the Takaichi government contemplates how best to fund its deficits.

These are the issues GPIF officials must be debating. How GPIF decides its asset allocation in the near future will be a revealing case study for those who want to study how policy-making works in Japan. Those who are interested in this topic should read the transcripts of an interesting government committee in 2014 that focused on how GPIF could shield itself from political meddling. Guess who chaired the committee? UEDA Kazuo [植田和男].

Whatever the near-term decision GPIF makes regarding its target weight, I think it is fairly clear that GPIF should be increasing its investment into domestic bonds. The following table shows how much GPIF could buy in net terms, depending on the eventual rise in the target weight.

How much GPIF buys: ¥32tn at 35%, ¥80tn at 50%

Domestic Bond TargetGPIF BuysWith the Sister Funds
30%¥16tn¥20tn
35%¥32tn¥20tn
40%¥48tn¥20tn
50%¥80tn¥20tn

Additional domestic-bond holdings from re-weighting the fund at 30 June 2026 (managed assets ·317.8tn). Foreign bonds sold first.
Source: GPIF, JMA.

Three things in this table matter for the market. GPIF is allowed to deviate its asset allocation by six points either side of 25% without any announcement, so 39% target is already possible without any public announcement. In 2014 GPIF moved inside its band first and announced the new portfolio afterwards, and I would expect the same sequence this time. Second, these are static figures, which do not account for the growth of the fund over time.

The sister funds move with the whale

As mentioned earlier, GPIF has a few siblings. The Pension Fund Association for Local Government Officials (¥35.5tn), the Federation of National Public Service Personnel Mutual Aid Associations, known as KKR (¥11.5tn), and the Promotion and Mutual Aid Corporation for Private Schools of Japan (¥4.9tn) manage the pension reserves of local government employees, national government employees and private-school teachers. These sisters run their funds on the same 25/25/25/25 model, and with the legacy reserves they also run, they hold a further ¥87tn on top of GPIF’s.

Conclusion

GPIF cut its domestic bond weight from 60% to 35% in 2014, and later to 25%, to safeguard its assets from the manipulated low JGB yields at the time and the eventual crash they foresaw. That crash, as GPIF’s CEO MITANI defined it in 2014, has now happened with the 10-year yield rising to 3%. In my view, JGB yields have largely normalized and there is no emergency reason to avoid domestic bonds. It is only natural that GPIF would raise its allocation into domestic bonds, although how GPIF communicates this publicly is a touchy issue they need to figure out. When GPIF raises its domestic bond allocation, foreign bonds are the likely asset class to take the hit. GPIF publishes quarterly results and the next publication for the end-September 2026 quarter, expected in early November 2026, will be closely watched. Judging from market movements in the last few weeks, the market has started to sense that what I described in this article is already happening and Japanese money is starting to come back to the yen. While it should be characterized as rebalancing, rather than a repatriation, it seems we are observing a big turn in Japanese cross-border capital flows.

Japan’s Deadliest Delicacy Is Getting More Dangerous

Rising sea temperatures are pushing pufferfish species together, spawning hybrids that even specialist chefs cannot safely prepare

[from South China Morning Post]

by Julian Ryall

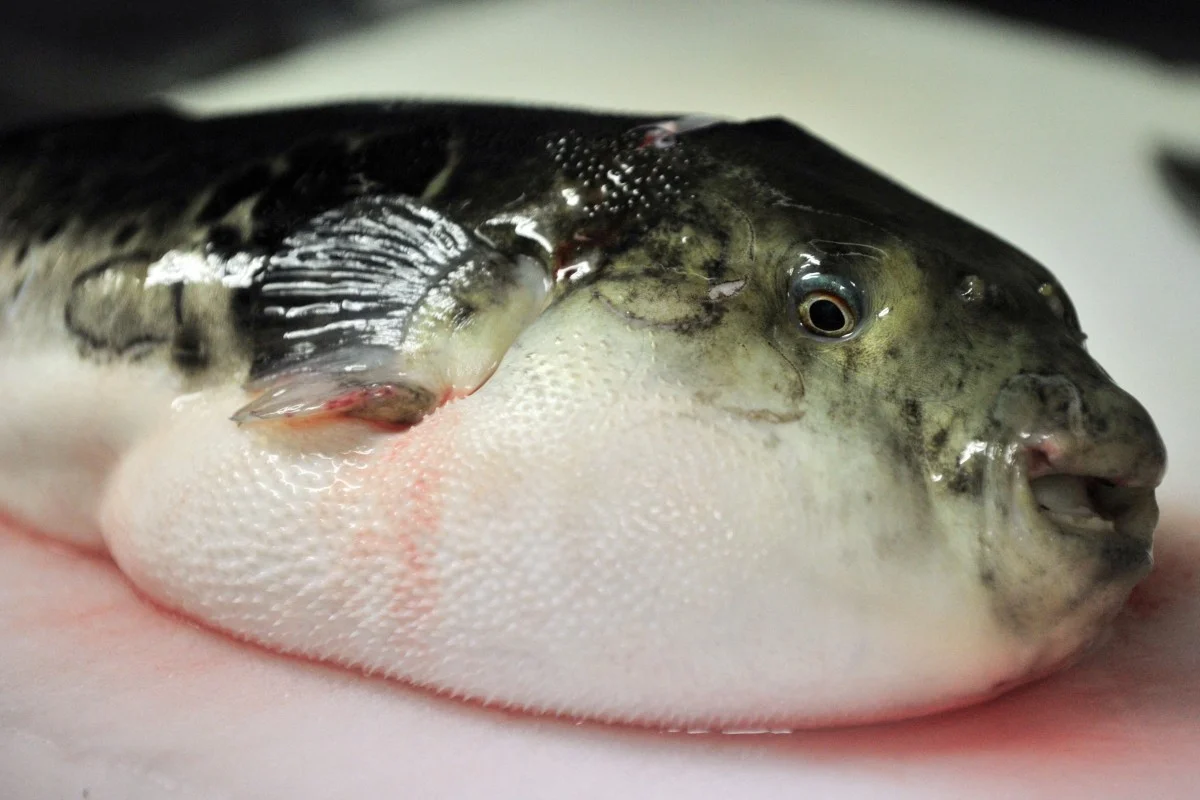
Japan’s most dangerous delicacy is getting harder to prepare safely as warming seas push different pufferfish species into the same waters, where they are inbreeding to produce hybrids whose lethal toxins are not yet fully understood.

Fugu – the collective Japanese name for several species of edible pufferfish – is prized as much for the danger surrounding its preparation as for its subtle flavour.

Many species contain tetrodotoxin, a powerful neurotoxin with no known antidote that can cause paralysis, respiratory failure and death.

Since 1958, anyone wishing to prepare pufferfish for public consumption has had to obtain a licence first, a process that takes at least two years and defeats roughly two-thirds of those who attempt it.

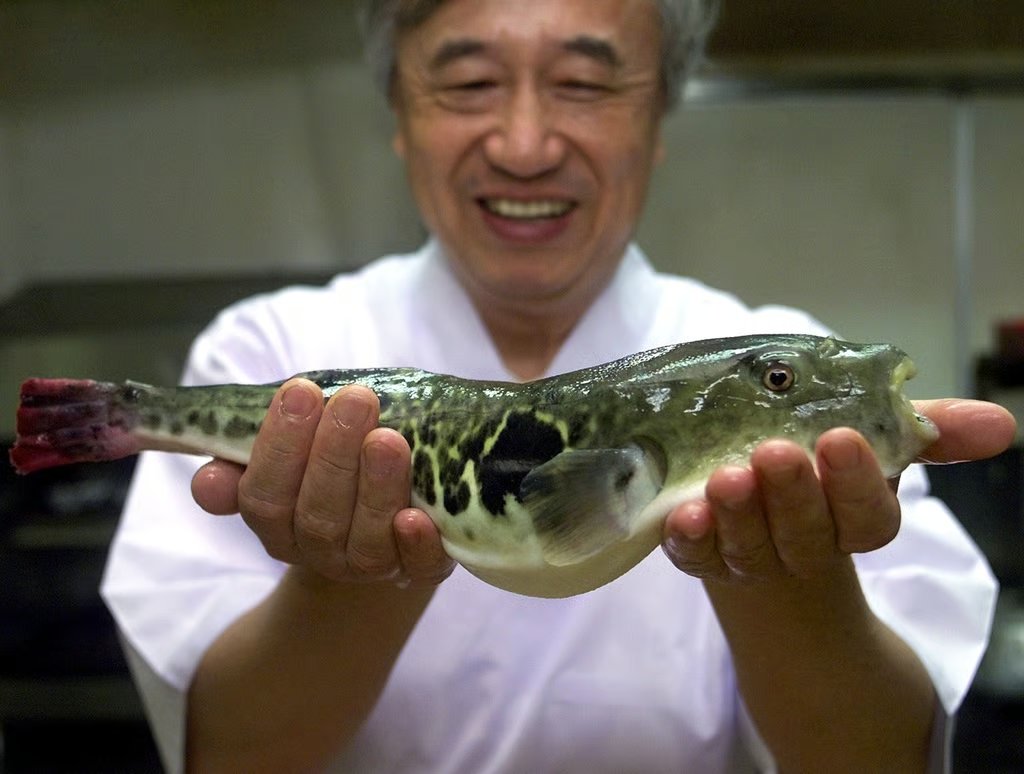
A restaurateur shows off a “fugu”, or pufferfish, at a restaurant in Shimonoseki, Japan. Photo: AP

Chefs learn to strip out the fish’s liver, ovaries, eyes and skin – tissues where the poison concentrates – with the precision of a brain surgeon and the nerve of a bomb-disposal technician.

But that hard-won expertise is now being undermined by climate-induced interbreeding, as experts say Japan’s coastal waters are heating up at roughly twice the global average rate.

Spotted pufferfish, once largely confined to the Sea of Japan, have spent the past decade steadily pushing northward in search of cooler currents. Some slipped through the Tsugaru Strait – the channel separating Honshu from far northern Hokkaido – where they have met and mated with the region’s native pufferfish species.

The resulting hybrids now make up as much as 40 per cent of local catches, according to a recent study of fish caught off Fukushima and Ibaraki prefectures.

“We started seeing these spotted fugu on the Pacific coast in 2012 as temperatures in the Sea of Japan became too high for them,” said Professor Hiroshi Takahashi of the National Fisheries University in Shimonoseki, Yamaguchi prefecture.

Temperatures in the waters there were “among the fastest rising anywhere in the world”, he told This Week in Asia, adding that the changes in pufferfish had been happening just as fast.

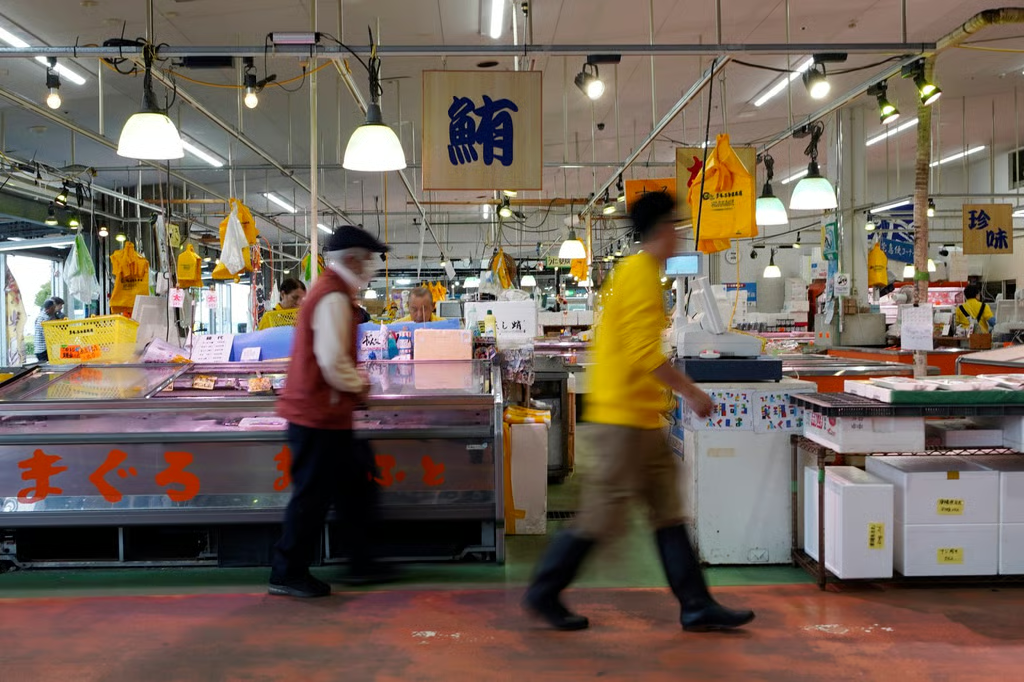
Customers visit a seafood market in Japan’s Fukushima prefecture. Photo: AP

Some spotted pufferfish had ventured down the east coast as far south as Tokyo Bay, Takahashi said, only to be driven north again as those waters also warmed.

Tiger pufferfish had likewise moved north from their usual range to interbreed with common pufferfish in and around Tokyo Bay, he added.

The trouble is not that hybrids are more toxic than their ancestors, it is that nobody yet knows how interbreeding has affected the distribution of toxins.

Each species of pufferfish stores tetrodotoxin in a different combination of organs and Japan’s health ministry has not yet been able to establish which parts of the new hybrids are safe to eat and which are not.

Until it does, the government has banned the sale or consumption of hybrid fugu – but this ban is almost impossible to enforce.

“They are very hard to identify,” said Takahashi, whose team has developed a DNA test capable of distinguishing hybrid fish and hopes to make the technology commercially available to fishermen who currently have no reliable way of screening their catch.

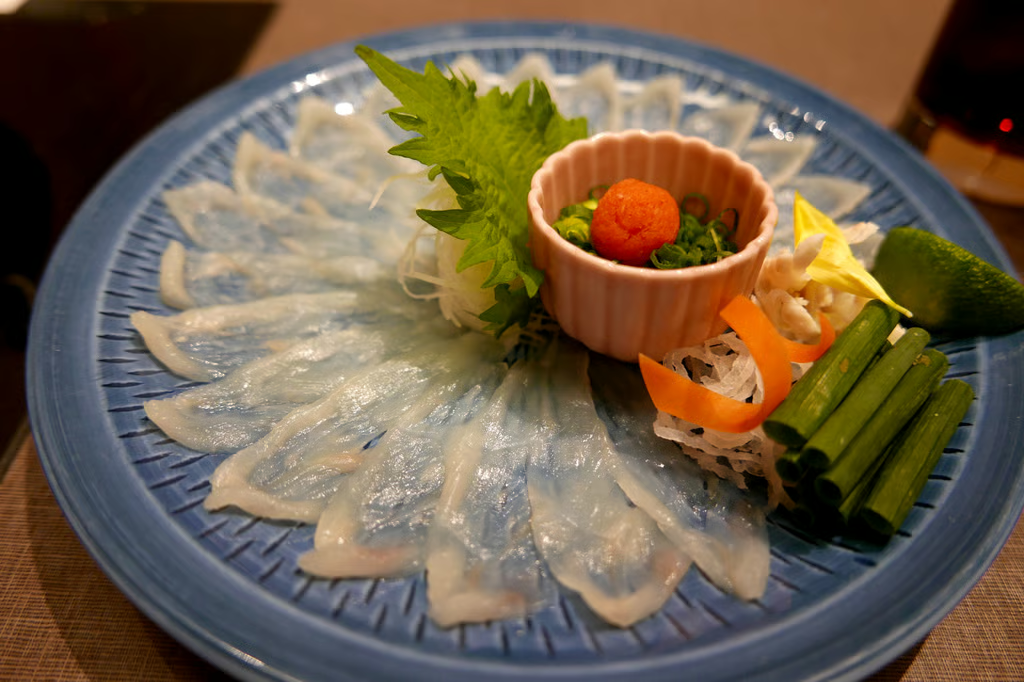
Pufferfish, or “fugu”, sashimi prepared for eating at a restaurant in Japan. Photo: Shutterstock

Fatal attraction

None of this is likely to diminish fugu’s deadly mystique. The dish has been eaten in Japan for centuries, enjoyed despite – or because of – the risks involved.

Every year, new tales emerge of amateur anglers preparing the fish to eat against the advice of anxious relatives and not surviving the attempt.

Diners speak of a faint numbness in the lips as evidence of a narrow escape and the emperor of Japan is barred from eating fugu altogether, lest even a licensed chef makes a mistake.

Urban legend holds that chefs who do poison a customer are honour-bound to end their own life, with their own knife, in atonement – though this is a myth.

For their part, Japanese restaurateurs are, perhaps unsurprisingly, keen to play down the risks.

A spokeswoman for Miyawaki Fugu Club, an upscale restaurant in Tokyo’s Ginza district, said its chef works exclusively with farmed tiger pufferfish from a long-established supplier, which she insisted were “completely safe”.

James Reimer, a professor of marine biology at the University of the Ryukyus, said the fugu phenomenon fit a wider pattern of marine life relocating in response to global warming.

“What happens to marine ecosystems is one of the hot-button issues of the day, particularly in Japan, because the waters here are warming at twice the global average rate,” he said.

During fieldwork off the Izu peninsula, south of Tokyo, three years ago, local fishermen told him that they had lost virtually their entire kelp crop and that the abalone once abundant in those waters had vanished.

A sea turtles in waters off Japan’s Amami Islands. Turtles are increasingly venturing farther north, fishermen say. Photo: Shutterstock

In their place, they said they were seeing far more sea turtles, as well as large schools of brightly coloured fusiliers – the prefectural fish of Okinawa, some 1,400km (870 miles) to the south.

“Last year, our summer in Okinawa was 30 days longer than average, and we had 120 days when the water temperature was around 30 degrees Celsius (86 degrees Fahrenheit),” Reimer said.

He warns that the picture is not simply one of fish and other marine life swimming steadily north in search of more comfortable temperatures, however.

Global warming is also destabilising weather patterns, making them less predictable. Waters off Kyushu, the southernmost of Japan’s main islands, that might otherwise suit certain species are increasingly prone to temperature swings that could make them unsuitable after all.

Even so, the broader direction is unmistakable. Kyushu’s waters have seen a marked rise in shark sightings in recent years, including large tiger sharks – one more sign of the changes occurring beneath the surface of Japan’s seas.

Chance and Necessity from the Perspective of W.B. Yeats

We have just seen “Chance and Necessity” from the perspective of Thomas Bayes and Jacques Monod. Before we get to the case of William Butler Yeats, let’s briefly consider famous non-scientific cases like Joseph Conrad’s Chance, Charles Sanders Peirce’s anthology of essays, Values in a Universe of Chance, and the phrase “nothing but chance,” which was central to the philosophy of Simone Weil.

Yeats attempted to use words to express largely numerical concepts. In the collection Mythologies, he wrote, “I think that all religious men have believed that there is a hand not ours in the events of life, and that, as somebody says in Wilhelm Meister, accident is destiny;…” (p. 336) Here we have chance, but what about necessity? He later states, “I do not doubt those heaving circles, those winding arcs, whether in one man’s life or in that of an age, are mathematical…” (p. 340).

Finally, we read, “I have always sought to bring my mind close to the mind of Indian and Japanese poets, old women in Connacht, mediums in Soho, lay brothers whom I imagine dreaming in some mediaeval monastery the dreams of their village, learned authors who refer all to antiquity; to immerse it in the general mind where that mind is scarce separable from what we have begun to call ‘the subconscious’; to liberate it from all that comes of councils and committees, from the world as it is seen from universities…” (p. 343).

As may be expected from a fundamentally poetic nature, Yeats parts company with the mathematics and science of Bayes and Monod. Like the philosopher Heidegger, who valued equipmental being in use, Yeats is profoundly ruralist, revering the Irish peasant, who has a more primordial connection to nature and folklore. Yeats’ view of “chance and necessity” both mirrors mathematical or scientific thought while trying to remain divorced from it.

Chance and Necessity

If you free-associate the word “chance,” you may arrive at “I’ll take my chances” before potentially arriving at Thomas Bayes’ “Doctrine of Chances”. Jacques Monod was an early explorer of the collision of probability and chance in biology.

THE PRINCE OF CHANCE

Jacques Monod grew up just down the coast from Monte Carlo in Cannes, France, another town famous for its casinos and, later, its film festival. Graced with movie star looks—one prominent French journalist described him as a “prince” who resembled Hollywood icon Henry Fonda, as well as considerable musical talent, and an exceptional intellect, Monod struggled to decide on a career path through his twenties. After distinguishing himself in the French Resistance, Monod rose to fame not as an actor or musician, but as a brilliant biologist. He shared the 1965 Nobel Prize in Physiology or Medicine for seminal discoveries about how genes work.

A pioneer in the field of molecular biology, Monod was privy to the blizzard of discoveries in the 1950s and early 1960s about the molecules that determined the characteristics of living things—what Monod and others dubbed “the secrets of life.” He kept close company with a relatively small international community of leading researchers. For example, when James Watson and Francis Crick cracked the structure of DNA (deoxyribonucleic acid) in 1953, Monod was one of the first with whom Watson shared the breakthrough.

But as a Frenchman steeped in his culture’s deep philosophical traditions, Monod was interested in science for more than just science’s sake. After the war, Monod befriended France’s leading philosopher-writer Albert Camus, and the two men pondered questions of human existence in Left Bank cafés. Monod felt that the public misunderstood the principal purpose of science as being the creation of technology. Rather, Monod believed technology was merely a by-product. He said, “the most important results of science have been to change the relationship of man to the universe, or the way he sees himself in the universe”—a relationship of equally intense interest to his friend Camus.

Monod thought that there were profound philosophical implications of the new molecular biology, particularly in the realm of heredity, which had gone largely unnoted in the broader culture. Several years after his Nobel Prize and Camus’ untimely death, he decided to write a book to try to bring the meaning of modern biology to laypersons.

“[T]he ‘secret of life’…has been laid bare,” he wrote.

“This, a considerable event, ought certainly to make itself strongly felt in contemporary thinking.”

Monod used several chapters to describe the insights that had very recently emerged from the study of DNA and the deciphering of the genetic code. He understood this knowledge would be unfamiliar to most readers, so he included an appendix with chemical structures of proteins and nucleic acids, and a primer on how the genetic code worked.

In a matter-of-fact style, he explained genetic mutations as accidental alterations—substitutions, additions, deletions, or rearrangements—in the text of DNA, in the sequence of the long strings of chemical bases (ACTTGATAA, etc.) that make up genes.

Then, almost without warning, he turned to the broader implications of how mutations arise in DNA. It is worth quoting him at length for after 111 pages of background, he delivered one of the most powerful ideas in five centuries of science (all italics are original):

“We call these events accidental; we say they are random occurrences. And since they constitute the only possible source of modifications in the genetic text, itself the sole repository of the organism’s hereditary structure, it necessarily follows that chance alone is at the source of every innovation, of all creation in the biosphere.

“Pure chance, absolutely free but blind, at the very root of the stupendous edifice of evolution: this central concept of modern biology is no longer one among other possible or even conceivable hypotheses. It is today the sole conceivable hypothesis, the only one that squares with observed and tested fact. And nothing warrants the supposition—or the hope—that on this score our position is likely ever to be revised.

“There is no scientific concept, in any of the sciences, more destructive of anthropocentrism than this one.”

In essence, heretofore obscure discoveries in biochemistry and genetics (largely studied at that time in simple bacteria) had upended two millennia of philosophy and religion that put humans at the center or apex of creation. “Man was the product of an incalculable number of fortuitous events,” Monod wrote. “The result of a huge Monte Carlo game, where our number eventually did come out, when it might not well have appeared.”

Le Hasard et la nécessité (Chance and Necessity) appeared in France in October 1970. It was a fairly technical book with several chapters on philosophy and genetics, and those appendices full of chemical diagrams. A first-time author, Monod did not know what reactions to expect.

The merde hit the fan.

The book received dozens of reviews across France and quickly became a bestseller—second only to the French translation of Erich Segal’s Love Story (this was France after all. After it was translated into English, reviews and interviews with Monod were featured in several of the most prominent British and American newspapers and magazines.

Many commentators immediately recognized the threat chance posed to traditional ideas of humanity’s origins and purpose. To Arthur Peacocke, a British biochemist turned prominent theologian, Monod had put forth “one of the strongest and most influential attacks of the century on theism.” A flurry of articles and books appeared with titles such as Anti-Chance: A Reply to Monod’s Chance and Necessity, Beyond Chance and Necessity, and God, Chance, and Necessity. Monod was invited to debate philosophers and theologians both in France and abroad, on television, radio, and in print.

American Calvinist theologian and pastor R.C. Sproul summed up the high stakes posed by chance in the first page of his book Not A Chance:

“It is not necessary for chance to rule in order to supplant God. Indeed, chance requires little authority at all if it is to depose God; all it needs to do the job is to exist. The mere existence of chance is enough to rip God from his cosmic throne. Chance does not need to rule; it does not need to be sovereign. If it exists as a mere impotent, humble servant, it leaves God not only out of date, but out of a job.” More than two hundred pages later, Sproul concluded:

“Chance as a real force is a myth. It has no basis in reality and no place in scientific inquiry. For science and philosophy to continue to advance in knowledge, chance must be demythologized once and for all.”

Sproul and other critics argued that what scientists perceived as chance merely reflected a lack of knowledge of true causes. Perhaps that was the expression of hope to which Monod alluded—the hope that as scientists learned more, our position on the role of chance would somehow be revised.

A SECOND CHANCE

The ensuing fifty years have not played out as either Monod or his detractors hoped. The Frenchman thought that the new insights from molecular biology should be a turning point for modern society-away from traditional beliefs about causes in the natural world toward one that embraced randomness and our chance existence.

Ha! Fat chance. The excitement and fuss stirred by Chance and Necessity simmered down, and Monod passed away a few years later. Surveys reveal that the majority of Americans, for example, continue to believe that everything on earth happens for His reasons.

But Monod’s critics should take no comfort. The province of chance in the biosphere and human life has been revised, although not at all in the scope or direction that they hoped.

The domain of chance has expanded into realms neither Monod nor anyone else imagined.

As we have learned much more about the history and workings of the planet, we have been startled to discover how the course of life has been buffeted by a variety of cosmological and geological accidents—without which we would not be here. As we have explored human history, we have seen how pandemics, droughts, and other civilization-changing episodes have been triggered by random, singular events in nature that easily might not have happened. And as we have probed human biology and the factors that impact our individual lives, we have caught chance red-handed, reigning over the often-thin line between life and death.

This book tells the stories that Monod could not—of astonishing discoveries from the planetary to the molecular scale, from great upheavals across the globe to the machinery of chance that operates within every cell of every creature, including ourselves. And while these discoveries vaporize the comforts of anthropocentrism, the story of chance, I hope you will come to agree, is much more than highfalutin philosophy or the refutation of theologians’ wishful thinking.

I hope that you are awed—awed by the power and the drama of asteroids slamming into the planet, of continents colliding, and of the rapid rising and falling of ice and oceans; awed by the realization that we live on (and are at the mercy of a planet that is far more unstable than our short lives perceive; awed by the knowledge of how random chance is at the source of all of the beautiful and wondrous creatures with whom we share the planet; awed by the unique invisible accidents that made each one of us; and awed by the fact that we humans, recent descendants of bands of hunter-gatherers who persevered through a period of exceptional chaos, have in just the last fifty years or so, figured all of this out!

My goal here is to be comprehensible without being comprehensive. It is almost trivial to claim that the world is the way it is or that we are here because of a long chain of chance, albeit fortunate, events. The explanatory power I seek comes from specificity. It is essential to unpack some of those events to appreciate how they shape the direction of life. The layout of the book follows a simple three-part logic. I’ll begin with inanimate, external chance events that have shaped the conditions for life (Part One, “Stuff Happens”), and then turn to the internal random mechanism within every creature that generates the adaptations to those conditions (Part Two, “A World of Mistakes”). Then, I bring the story to the personal level (Part Three, “23 and You”) and how chance impacts our natural lives, as well as our deaths. Our chance-driven existence shatters long-held beliefs about humanity’s place and raises challenging questions about the meaning and purpose of our lives. In the Afterword, I’ll offer some possible replies with the help of some special guests.

This is a relatively small book for a really big idea. Science has given us a handful of really big ideas over the centuries, but they have been received in funny ways. Darwin had a huge idea that was very simple to understand, and even though the evidence is massive and everywhere, many refuse to believe it. Einstein had a brand new idea, and even though few understand it or the evidence for it, most everyone seems to believe it. Monod had a great idea, but these days most people (other than scholars) have not heard of it, or of him.

My greatest hope, then, is that this short book might be chance’s second chance.

Sean B. Carroll, A Series of Fortunate Events: Chance and the Making of the Planet, Life, and You, Princeton University Press, 2020, pp. 6-12.

Modern biology as described by Monod pushes the linkage of probability, randomness and chance to the center. At the time, this was a very radical and profound way of looking at biology. If we combine Monod’s biology with theoretical physics like Lawrence Krauss’ A Universe from Nothing: Why There Is Something Rather than Nothing, we realize that accidentality is the bedrock on which our knowledge of the universe is built.

Modernity and its Nightmares

Scholars console themselves with the notion that calamitous acts of death and destruction such as The Holocaust, the Bengal famine, and the atomic bombings of Hiroshima and Nagasaki are freak, singular aberrations. Psychologically, it’s reassuring to pigeonhole these as exotic historical events for academic study and push them away.

In 1989, Zygmunt Bauman published Modernity and the Holocaust, in which he argues the opposite: that these events are intrinsically linked to modernity. A symptom of the nightmare of modernity can be seen in Shlomo Sternberg’s Dynamical Systems, where he includes a photo of Felix Hausdorff, with a caption explaining the latter’s suicide (to avoid an extermination camp) amid his brilliant mathematical analysis.

At the end of World War II, Allied forces agents detained ten leading German scientists who were thought to have worked on Nazi Germany’s nuclear program. When one of these men, the Nobel Prize-winning chemist Otto Hahn, heard about the atomic bombings of Hiroshima and Nagasaki, he is said to have had a nervous breakdown, feeling guilt for his discovery and its use in this tragedy.

The Harvard Nobel Prize-winning economist Amartya Sen focused on the Bengal famine. In Poverty and Famines: An Essay on Entitlement and Deprivation, he explained that the Bengal famine was not the result of food shortages due to flooding, locusts or crop failures, but rather resulted from income shortages and lack of political clout.

The rise of bureaucracy, entwined with modernity, has removed any sense of culpability, as technological breakthroughs can be used to cause horrific events. You may have seen the 2023 film Oppenheimer, which depicts the American theoretical physicist’s guilt over developing atomic weapons amid Congressional hearings. In this framework, Fritz Haber was instrumental in developing the large-scale synthesis of fertilizers and explosives and is considered the “father of chemical warfare” in contrast to the advances he gave us in agriculture.

To quote Stephen Dedalus from James Joyce’s Ulysses, “History is a nightmare from which I am trying to awake.”