Japan Inc. Now Sells No Yen to Invest Abroad

Earnings on Japan’s foreign direct investment (FDI) reached 103% of new FDI in 2022–25. With dividends and retained earnings counted together, Japan Inc. now needs to sell little yen to invest abroad.

[by OKUBO Takuji]

Key takeaways

  • Foreign affiliates now earn about as much as Japan invests abroad each year. Reinvested earnings, dividends and interest together reached 103% of new outward FDI in 2022–25, against 48% in 1996–2000.
  • Dividends from foreign affiliates account for a growing share of Japanese corporate profit. We estimate that foreign affiliates contributed 13.4% of Japan Inc.’s earnings in FY2025, up from 1.7% in FY1996.
  • Corporate investment abroad now involves little net yen selling. After dividends and interest paid home, the estimated outflow has been close to zero since 2022, down from about ¥5 trillion a year, or about 1% of GDP, on average in the 2010s.

Japan’s FDI stock now earns 103% of new investment

It is often said that Japan’s ageing population and slow growth give its companies too few investment opportunities at home. A Japanese government report in 2024 included the following passages.

“Japan’s ageing and shrinking population depresses expected demand at home. Expected returns remain higher abroad, so Japanese companies have accelerated outward direct investment” (my translation). — MATSUBAYASHI Yōichi [松林 洋一], MOF PRI, chapter 8, p.136.

“Companies invested abroad because they saw no promising investments in Japan; they are unlikely to bring back every return. On a cash-flow basis, the external balance is in deficit and is one factor behind the weak yen” (my translation). — KARAKAMA Daisuke [唐鎌 大輔], MOF PRI, chapter 10, pp.178 and 175.

However, my review of recent data shows that while their premise of low growth prospects in Japan is probably still right, the direct investment Japan has accumulated abroad has reached a level where it earns enough to cover Japan’s new investment abroad. This changes the exchange-rate implication even if Japan keeps investing abroad.

As chart 1 shows, earnings on the accumulated investment stock rose from 48% of new outward FDI in 1996–2000 to 103% in 2022–25.

Chart 1
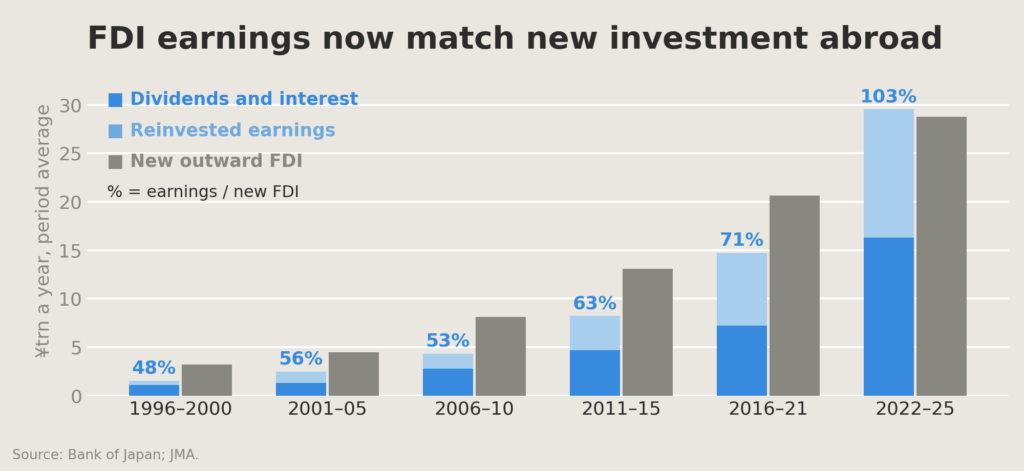
Overseas affiliates pay interest and dividends to their parent companies in Japan. Those dividends have become a sizable part of corporate Japan’s income: we estimate that they made up 13.4% of Japanese corporate profit in FY2025, up from 1.7% in FY1996.

When foreign affiliates retain their earnings on their balance sheets, Japan’s balance of payments statistics record them as FDI from Japan, even though no money crosses the border. While the companies receiving FDI dividends and the companies paying for new FDI are not necessarily the same, Japan Inc. as a whole is now financing its FDI almost entirely from the earnings of its overseas affiliates. At the current level of FDI, little new yen needs to be converted into foreign currencies as Japan goes about investing abroad.

In the rest of this report, I explain how foreign direct investment by Japanese companies evolved, and its near-term outlook. This report is the third in a series on the yen repatriation theme that I have published over the past few weeks, following “Yen Repatriation Starts with the Whale”, on capital flows through Japan’s national pension funds, and “Mrs Watanabe No More”, on Japanese households’ assets invested abroad.

A strong yen helped drive Japan’s first outward FDI boom

Japan’s outward investment was heavily restricted after WWII, requiring case-by-case permission from the government. Approvals became more and more automatic over the years until outward investment became “free in principle” in 1980. Trade friction with the US-led Japanese carmakers to restrain their exports from 1981, pushing them to build factories abroad. The rapid appreciation of the yen was also a factor. The yen strengthened from ¥242 per dollar before the Plaza Accord in September 1985 to ¥121 by the end of 1987. Japanese producers had to move lower value-added work abroad. The strong yen also gave Japanese financial institutions sizable purchasing power for a while, until the stock and property bubbles burst in 1990 and 1991.

All of these factors contributed to a rapid increase in outward FDI through the 1980s and 1990s (chart 2).

Chart 2

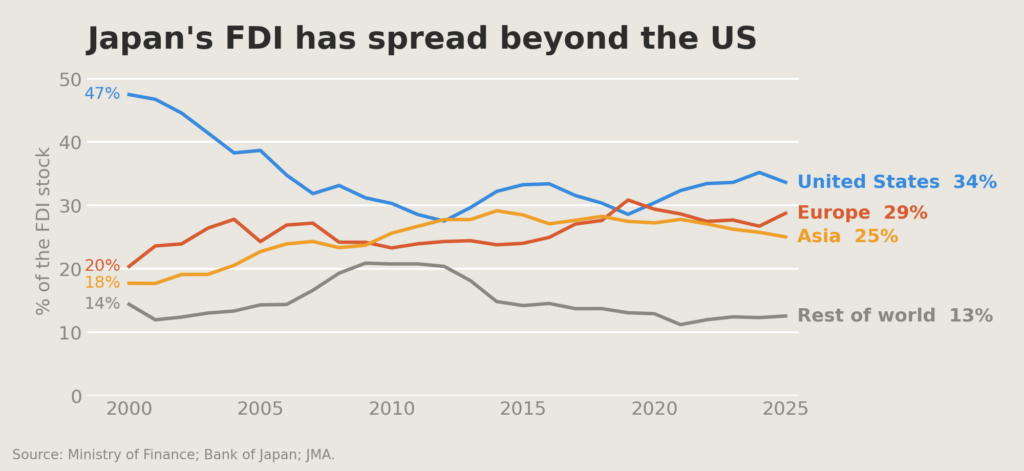
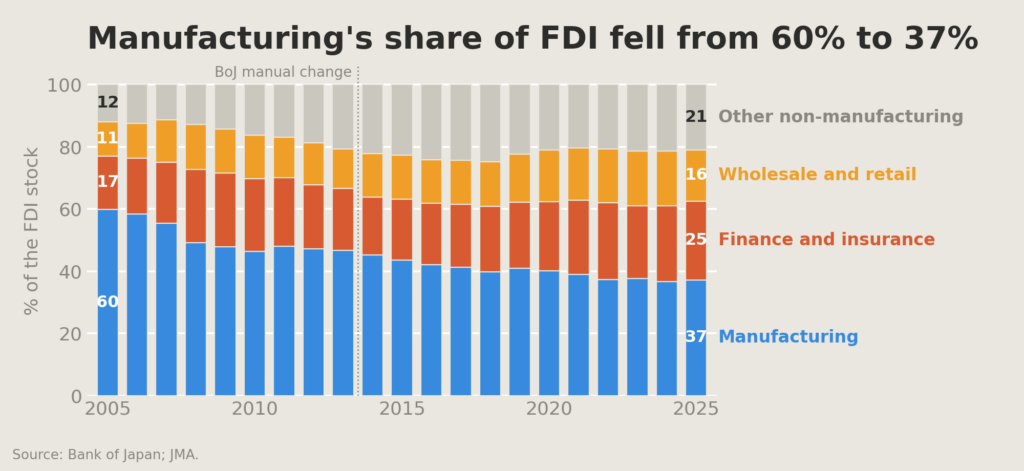
Even after the bubble burst, the strong yen kept pushing manufacturers to move abroad. In 2005, manufacturers accounted for 60% of the FDI stock. As Japanese manufacturers expanded their supply chains abroad, Asia’s share of outward FDI rose from about 12% in FY1986–90 to 19% in FY1995–99, and Asia held 23% of the FDI stock by 2005 (chart 3).

Chart 3
Japan’s outward FDI stock rose to 56% of GDP

The next phase was sustained by a different pressure. With weak growth and low interest rates at home, Japan Inc. kept investing abroad, across a broader range of industries. Between 1995 and 2025, the stock of FDI rose from 9% of Japan’s GDP to 58% (chart 4). In 2025, it is as large as about 38% of the private sector’s domestic fixed capital, on our estimate.

Chart 4

By industry composition and by destination compositions changed over time. Manufacturing’s share of the FDI stock had fallen to 37% by 2025, giving Japan’s FDI more breadth. By destination, we are seeing a revival of FDI toward the United States. It accounted for 34% of the stock in 2025, Europe 29% and Asia 25% (see earlier chart 3).
Thus, after decades of overseas investment, Japan’s FDI stock is now large enough that its earnings are sufficient to finance new investment abroad, at least for now. In the next section, I consider whether this will continue, and in particular whether Japanese companies may bring an even larger share of their overseas earnings back to Japan, given the weak yen, higher borrowing costs in yen and possibly better investment opportunities at home.

The weak yen has slowed offshoring, not reversed it

The real depreciation of the yen over the past 15 years made production in Japan more competitive. There is some evidence that manufacturers are considering bringing production back to Japan. The 2023 manufacturing white paper found more firms shifting production back from China than moving there, and they named the weak yen as one reason. We see some signs of reshoring. Japanese manufacturers’ overseas production ratio rose from 18.0% in FY2011 to 27.2% in FY2023, but it may have started to decline or at least stabilize. The ratio fell to 26.7% in FY2024. A Cabinet Office survey of listed manufacturers puts the ratio at 24.5% in FY2025, and their plan for FY2030 is broadly unchanged at 24.7%. The weak yen seems to have stabilized the wave of offshoring, but I see no firm evidence of a move back onshore yet.

Domestic investment has grown slowly despite the weak yen

There are tentative signs that domestic capital spending is starting to grow again. For three decades it grew at a very low speed. In real terms, private business investment rose only 26% between FY1997 and FY2025, less than 1% a year. In comparison, capital spending grew by about 4% a year on average in the United States. In my view, a weak currency is only one of the factors manufacturers weigh in designing their global production chains. The weak yen makes production in Japan competitive today, but they have also seen the exchange rate swing violently within short periods. Japan also has a shrinking population problem. It started to address it by opening a door to immigration, but the door is only tentatively open. Overall, my view is that the weak yen alone is unlikely to give Japan Inc. sufficient incentive to bring its capital back to Japan and to the yen.

Economic security is bringing some production home

The government is pushing harder than the currency, mostly in the name of economic security, even before the Takaichi government came along. The government currently has a ¥250 trillion domestic investment target for FY2040 and named AI and semiconductors among its 17 strategic fields. Semiconductors are where the money has gone furthest. In November 2024, under the Ishiba government, Japan committed more than ¥10 trillion of public support to AI and semiconductors by FY2030, aiming to draw more than ¥50 trillion of public and private investment over ten years. Japan managed to lure a TSMC plant to Japan, backed by a sizable subsidy. Rapidus, a government-supported Japanese semiconductor maker, has received a sizable subsidy and is building a factory in Hokkaido. Japan’s production of integrated circuits and discrete semiconductors rose from ¥2.7 trillion in 2019 to ¥4.1 trillion in 2025.

Under the name of economic security, the Japanese government is promoting other industries such as batteries, shipbuilding and pharmaceuticals. Defence spending adds to the push. Japan’s defence budget rose from about ¥5 trillion in FY2022 to ¥9.0 trillion in FY2026. Some defence contractors, such as Mitsubishi Heavy Industries, have doubled their defence revenue.

Japan’s industrial-policy record gives reason for caution

The Japanese government and the Ministry of Economy, Trade and Industry (METI), the key agency behind Japan’s industry policy, may claim some expertise in their industrial policies. Empirical studies in the past paint a poor track record, though. Rapidus, the most ambitious semiconductor project, has had no independent cost-benefit assessment (Negrine et al., 2025). While defence and economic security-driven policies have a different logic, I doubt that these industrial policies will succeed in bringing large-scale manufacturing investment back to Japan so long as macro factors such as Japan’s demography remain unfavourable.

FDI no longer appears to drive yen weakness

The weak yen and non-economic geopolitical factors do point to a halt in Japan’s four-decade offshoring trend, although it is a stabilization, rather than an economy-wide reversal of past offshoring. Japan Inc. will continue to invest more abroad, rather than within its borders. Given the sizable growth in the stock of cumulative FDI, Japan Inc. no longer needs to convert yen into overseas currency to keep investing abroad though. Net of dividends and interest paid home, Japan’s FDI sold about ¥5 trillion of yen a year, or about 1% of GDP, on average in the 2010s; since 2022 the net flow has been close to zero. There is also an interesting development in an effort to allow more share-exchange based M&A for cross-border deals that will further reduce the need for Japanese companies to spend their yen to purchase overseas assets. In my view, Japan Inc.’s FDI is no longer a factor to drive the yen weaker.

References

Japan-Watching: Economics in the Age of AI

A Thought Experiment Envisioning A “Fully Automated Society”

from REITI, by IKEUCHI Kenta [池内 健太], Senior Fellow (Policy Economist)

In a world where human labor has become unnecessary because of AI, what should be the focus of the study of economics? In the future, if AI and robots have become capable of producing all goods and services necessary for our society, what kind of economic problems could remain?

Of course, a fully automated society is not predicted for the near future. This article imagines such an extreme type of society as a thought experiment designed to consider economic systems in the age of AI. Here, a fully automated society refers not only to one in which corporate production is automated, but also to one in which the legislative, administrative, and judicial functions of government are substantially supported—and in some cases automated—by AI.

I started thinking about this matter when I heard from a researcher acquaintance that a paper concerning AI’s impact on employment had caused quite a stir on X, and I decided to read it out of curiosity. The paper discussed the possibility that AI-driven job cuts could reduce workers’ incomes, weaken consumer demand, and ultimately backfire on firms themselves (Falk and Tsoukalas 2026). Companies may earn higher profits in the short term by taking advantage of AI to cut back on personnel costs. However, if most companies follow that same approach, overall market demand would weaken because workers are also consumers.

The purpose of this article is not to question the validity of that paper’s argument. Rather, the focus is on what economic problems would remain in a future society if AI not only partially replaces human labor but also produces most goods and services.

Scarcity Will Continue to Be a Problem

There has already been extensive research regarding the impact of AI on employment. For example, Acemoğlu and Restrepo (2019) argued that while automation may replace existing human jobs, it may also create new ones. Moreover, the possibility that technological advances could free humans from labor and greatly alleviate economic problems was discussed long ago by Keynes (1930).

If AI and robots become capable of producing goods and services on a sufficiently large scale, would economic problems disappear? That would not necessarily be the case. Even in a fully automated society, scarce resources such as land, location, natural environments, energy, and rare metals will remain limited. Moreover, social status, influence, and political decision-making power are deeply connected to human intentions and perception, and cannot simply be delegated to AI. More land will not become available simply because more people wish to live in convenient urban locations. Quiet natural environments, advanced healthcare resources, social attention, and political influence also cannot be maximized for everyone at the same time.

Therefore, even in a fully automated society, some economic problems will remain. However, the main focus will shift from the “problem of insufficient ordinary commodities” to “how to allocate fundamentally scarce resources.” As production capacity increases, the value of true scarcity only becomes clearer.

In that case, the roles of markets and prices will still exist. Prices are not merely figures that allow for corporate earnings; they convey information about which resources are scarce and to what extent, how much demand there is for those resources, and what supply constraints there are. That perspective connects to a classic argument made by Hayek (1945), who argued that prices function as a mechanism through which dispersed information can be aggregated.

However, if AI becomes deeply integrated into the market, the concept of price itself may change. At present, prices serve as one-dimensional signals representing the levels of various factors, such as scarcity, quality, demand, supply, environmental impact, and future risks, expressed in terms of a single metric, that is, monetary value. If AI agents become capable of processing large volumes of information on behalf of consumers and companies, it is possible that multi-dimensional market signals that convey information concerning all those various factors, including quality, environmental impact, congestion, delivery time, reliability and social impact may come into use. Narita (2025) also discussed the possibility that the roles of money and prices may change, with more diverse evaluation standards becoming involved in economic coordination.

For People to Enjoy Affluence

In a fully automated society, how people participate in the market and society will become more important than ever. If the premise that people earn income through labor becomes obsolete, it will be necessary to develop a mechanism whereby purchasing power is distributed to everyone. In this context, universal basic income (UBI) may be reframed not only as relief for the unemployed, but as a form of fundamental purchasing power used by people to express their preferences. Managi [馬奈木 俊介] (2025) also pointed out that governance over the equitable distribution of the benefits of AI is essential.

Moreover, UBI may not be limited to simple monetary payments. In the future, UBI may take the form of a system combining other benefits as well, including energy use quotas, rights of access to basic healthcare services and education, and rights to refuse or control the use of personal data. In a fully automated society, UBI would therefore be a matter not only of how much to provide, but also of what kinds of access to guarantee and over what time horizon.

Another important issue is whether it is appropriate to treat people merely as consumers. In a fully automated society, the need for people to work for a living may diminish. However, even without such a necessity, humans will likely still possess the desire to create or to be creative. It is human nature to try new things and to try to surprise or impress other people. The spirit of fun and curiosity, a desire for self-expression, an inquisitive mind, and an appetite for challenges are deeply and fundamentally connected to human nature. Therefore, when designing a future UBI system, it will be important to treat people not merely as consumers but as agents who can participate in creation and exploration.

Additionally, the question of who owns and controls AI systems, robots, foundation models, and computing infrastructure is also a major issue. Even if a certain level of income is distributed to everyone, there may remain a power gap between those who control AI systems and robots and those who merely have access to them, in place of the income gap that currently exists in society.

All of the above-mentioned points for debate are relevant to the study of economics. How scarce resources should be allocated, how to guarantee people’s range of choices, and how to design ownership and controlling rights are problems central to economics. A fully automated society is not a near-future prediction. However, this extreme thought experiment serves as a useful guide for considering economic systems in the age of AI. Economics in the age of AI is not about discarding the intellectual legacy of economics, but about inheriting it and extending it toward a new society.

References

June 12, 2026

Economics-Watching: Estimating the Effects of Monetary Policy: An Ongoing Evolution

New monetary policy tools have lengthened the interval over which policy news is transmitted and processed.

[from the Federal Reserve Bank of Kansas City, 2 October 2025]

by Karlye Dilts Stedman, Amaze Lusompa & Phillip An

Disentangling how the economy responds to a monetary policy decision from its response to macroeconomic conditions at the time of the decision is an ongoing challenge. One popular method researchers use to measure the effect of a monetary policy announcement—high-frequency identification—analyzes the reaction of fast-moving financial variables immediately following the policy announcement, using a time window long enough for markets to respond but not so long that the response is contaminated by other information.

Since high-frequency identification was introduced in the early 2000s, policymakers have introduced tools such as forward guidance and large-scale asset purchases. Karlye Dilts Stedman, Amaze Lusompa, and Phillip An examine how the evolution of monetary policy has changed high-frequency identification and assess whether additional changes might be necessary to better capture the effect of modern monetary policy surprises. Although researchers have continually updated the asset mix used in high-frequency identification over time, they have not updated the measurement window. Because the timing of monetary policy communication has changed significantly in recent years, refining the length of this measurement window may be necessary going forward.

Read the full article [archived PDF].

Economics-Watching: Tracking the Economy in Real‑Time Through Regional Business Surveys

[from the Federal Reserve Bank of New York’s The Teller Window, 23 September 2025]

by Richard Deitz and Kartik Athreya

Federal Reserve policymakers need current information about economic conditions to make well-informed monetary policy decisions. But hard data, such as GDP and the unemployment rate, is released with a significant lag, making it difficult to get a precise, real-time read on the economy, especially during times of rapid change.

To help fill the gap, the New York Fed conducts two monthly regional business surveys: the Empire State Manufacturing Survey of manufacturers in New York state and the Business Leaders Survey, which covers service sector firms in New York state, northern New Jersey, and Fairfield County, Conn. These surveys provide timely soft data, available well before hard data is released.

Hard data is based on precise quantitative measurements, such as sales figures or the specific prices firms are charging. By contrast, soft data is qualitative, focusing on trends, expectations, and sentiment around economic activity. And while hard data looks backward, soft data from the regional surveys can look forward—providing important information about expectations for the future and emerging trends.

Gathering soft data quickly can be impactful—for example, the Empire State Manufacturing and Business Leaders surveys signaled a sharp downturn in economic activity in early March 2020 [archived PDF], providing a warning weeks before official statistics captured the full extent of the COVID pandemic’s economic impact.  

How the Surveys Work

The New York Fed launched the Empire State Manufacturing Survey in 2001. It was modeled after the Philadelphia Fed’s Business Outlook Survey, a long-running manufacturing survey that has historically been watched by financial markets and policymakers as an early signal about national manufacturing conditions. The Business Leaders Survey was launched later in 2004 and was among the first regional business surveys to target the service sector.

The surveys are sent to over 300 business executives and managers at firms across industries during the first week of every month. While about two-thirds of participating firms have 100 or fewer employees, some have hundreds or thousands of workers.

Leaders at the firms fill out a short questionnaire asking if business activity has increased, decreased, or stayed the same compared to the prior month. The surveys ask about indicators such as prices–yielding insights into inflationary pressures–as well as employment, orders, and capital spending. Respondents answer questions about how they expect these indicators to change over the next six months, offering a forward-looking perspective on the economy’s trajectory.

From the responses, New York Fed researchers construct diffusion indexes by calculating the difference between the percentage of firms reporting increased activity and those reporting decreased activity. Positive values indicate that more firms say activity increased than decreased, suggesting activity expanded over the month. Higher positive values indicate stronger growth, while lower negative values indicate stronger declines.

The surveys include local businesses, like restaurants and car dealerships, as well as firms with national and global reach, such as software manufacturers and shipping enterprises. As a result, the economic indicators derived from the surveys are often early predictors of national economic patterns, frequently aligning with hard data released later.

Getting Answers on Current Issues

The surveys regularly ask supplemental questions about current economic issues to get real-time answers. Over the last few years, the surveys have asked about firms’ experience with tariffs, inflation expectations, if the use of AI is leading to a reduction in employment, how often employees work from home [archived PDF], and whether supply availability was affecting their businesses.

Going Beyond the Indicators

In addition to providing data to track economic conditions, the regional surveys also provide a channel to hear directly from local business leaders. Every month, survey respondents are asked for their comments, offering the opportunity for businesses to share their thoughts, concerns, and experiences with the New York Fed. This helps researchers and policymakers understand how businesses are being affected by economic conditions.

The surveys act as one of the bridges between the New York Fed and the business community, ensuring the voices of regional businesses are considered in economic assessments and policy discussions as well as enhancing the ability of policymakers to make informed decisions to respond effectively to economic challenges.

Executives, owners, or managers of businesses in New York, northern New Jersey, or Fairfield County, Conn., interested in participating in the New York Fed’s monthly business surveys can find more information here. The next survey results will be released on Oct. 15 and 16.

Newspapers and the “Manufacture of Consent”

When we think about newspapers, various associations come to mind. Examples include Jeff Bezos purchasing The Washington Post or William Randolph Hearst inspiring Citizen Kane. Newspapers have, to some extent, devolved into a vehicle for propaganda, as described in Walter Lippmann’s Public Opinion.

Lippmann is famously quoted for advocating the “manufacture of consent.”

Max Weber describes the economic function of newspapers:

The newspaper as an institution came into the service of commerce at an astonishingly late date.

The newspaper, as an institution, is not a product of capitalism. It brought together in the first place political news and then mainly all sorts of curiosities from the world at large. The advertisement, however, made its way into the newspaper very late. It was never entirely absent but originally it related to family announcements, while the advertisement as a notice by the merchant, directed toward finding a market, first becomes an established phenomenon at the end of the 18th century—in the journal which for a century was the first in the world, the “Times.” Official price bulletins did not become general until the 19th century; originally all the exchanges were closed clubs, as they have remained in America virtually down to the present. Hence in the 18th century, business depended on the organized exchange of letters. Rational trading between regions was impossible without secure transmission of letters. This was accomplished partly by the merchant guilds and in part by butchers, wheelwrights, etc. The final stage in the rationalization of transmission of letters was brought about by the post, which collected letters and in connection therewith made tariff agreements with commercial houses. In Germany, the family of Thurn and Taxis, who held the postal concession, made notable advances in the rationalization of communication by letter. Yet the volume of correspondence is in the beginning surprisingly small. In 1633, a million letters were posted in all England while today a place of 4,000 population will equal the number.

Max Weber, General Economic History, Collier Books, 1966 (Third Printing), page 220.

Herbert Hunt provides a useful overview of the newspaper as a political tool in his introduction to Honoré de Balzac’s Lost Illusions (French: Illusions perdues).

The first half of the nineteenth century witnessed the rapid rise to power of the periodical press. Journalism had been active — though dangerous to those engaged in it — during the Revolutionary period. Napoleon had kept the press under his thumb, as Giroudeau points out on page 235. The ‘freedom’ of the press was one of the most controversial issues both under the Restoration and the July Monarchy. Under Louis XVIII and Charles X the struggle between those who, like the Liberals and Bonapartists, wanted to keep the Revolutionary principles and gains intact, and the Conservatives of various hues, especially the ‘Ultras’, who wanted to put the political clock back, was an affair of major importance; likewise, under Louis-Philippe, the conflict between the spirit of stagnation and the parties in favour of ‘movement’. Balzac’s contention is that the majority of journalists under these three monarchs, instead of recognizing that they were called to a serious, even sacred mission, turned the Press into an instrument for self-advancement, prostituted principles to intrigue and used journalism merely as a means of acquiring money, position and power. He is reluctant to admit that there were great, responsible press organs, like Le Journal des Débats, Le Conservateur, Le Constitutionnel and, from 1824, Le Globe, which stood firm on principle; he is above all aware of the vogue which the petits journaux enjoyed after the fall of Napoleon, and of the role they played as political privateers.

The petits journaux were so-called because they were produced in smaller format than the important dailies or weeklies, which were more or less grave, staid and ponderous. They proliferated in Paris once the fall of the Empire had given a relative, though still precarious liberty to the Press — precarious because it was constantly threatened by the increasingly reactionary governments of the time. The politicians of the Right found it difficult to keep the newspapers under control even by such means as stamp-duty, caution-money, fines, suspensions and suppressions, the object of these being mainly to put obstacles in the way of would-be founders of hostile periodicals. The ‘little papers’, short-lived as they often proved to be, were much given to journalistic sharp-shooting. They preferred satire, personal attack, sarcasm and scandal-mongering to serious argument or the affirmation of ideals. They were mostly Opposition journals and were a constant thorn in the flesh of the Government. Balzac’s aim was to expose their addiction to ‘graft’, intrigue, blackmail and the misuse of the feuilleton, namely the bottom portion of the first page or other pages generally reserved for critical articles and frequently devoted to the malicious task of slashing literary reputations. Andoche Finot — the prototype of such later newspaper magnates as Émile de Girardin and Armand Dutacq, pioneers in 1836 in the founding of cheap dailies which relied on advertisement and serialized novels as a chief source of income — acquires a large share in a big daily and hands on to the equally unprincipled Lousteau the editorship of the ‘little paper’ he already owns. Balzac probably had Le Figaro chiefly in mind, a periodical which was constantly going bankrupt or being suppressed but kept popping up again under different editors. Hector Merlin’s royalist Drapeau Blanc, edited by Martainville, really existed, having been founded in 1819; so did Le Réveil. Other examples of ‘little papers’ before 1830 were Le Nain Jaume (Bonapartist), Le Diable Boiteux and Le Corsaire (both Liberal), Le Voleur, La Mode, La Silhouette, and, under Louis-Philippe, not only the phoenix-like Figaro, but also La Caricature, Le Charivari (ancestor of our English Punch), and once more Le Corsaire: a few among many. Louis-Philippe and his Cabinets were easy prey for these stinging gad-flies whose unremitting satire and innuendo remind one of the present-day Canard Enchaîné.

It is an amusing thought that, in the late twenties and early thirties, Balzac had himself been a contributor to these disreputable rags and sometimes had a hand in the running of them; for instance he had helped Philipon to found La Caricature. Throughout his career he contributed many novels in serial form to the more important newspapers, notably those founded by Girardin and Dutacq — La Presse and Le Siècle. But by the time he was writing A Great Man in Embryo he had left the petits journaux far behind him. He himself tried his luck as a newspaper-proprietor and editor: he bought La Chronique de Paris in 1836 and founded La Revue Parisienne in 1840. Both of these ventures failed. We can well imagine therefore what a large amount of bile was accumulating inside him. On the whole, reviews of his works appearing in periodicals had been hostile if not harsh. He suffered much from the disparagement of editors and critics such as Sainte-Beuve and Jules Janin respectively. He was always quarrelling with Émile de Girardin. And so he took his revenge. He had already made a preliminary attack on the periodical press in The Skin. And he followed up his attack of 1839 with his Monograph of the Paris Press (1842).

Honoré de Balzac, Lost Illusions, translated and introduced by Herbert Hunt, Penguin Books, 1971, pages xiv-xvi.

Balzac’s novel is very concerned with all aspects of journalism. For example, chapter 17 is titled “How a news-sheet is edited” and chapter 18 is a symposium on newspapers. Chapter 18 quotes a German guest who states, “I thank god there are no newspapers in my country.” (page 312). Another participant states, “In corporate crimes no one is implicated.” “A newspaper can behave in the most atrocious manner and no one on the staff considers that his own hands are soiled.” (page 314).

‘The influence and power of newspapers are only just dawning,’ said Finot. ‘Journalism is in its infancy; it will grow up. In ten years from now, everything will be subject to publicity. Thought will enlighten the world…’

Honoré de Balzac, Lost Illusions, Penguin Books, 1971, page 313.

‘Newspapers are an evil,’ said Claude Vignon. ‘An evil which could be utilized, but the Government wants to fight it. There’ll be a conflict. Who will go under? That’s the question.’

Honoré de Balzac, Lost Illusions, Penguin Books, 1971, page 313.

We should heed Vignon’s warning. Nazi Germany’s three main newspapers confirm this danger.

Economics-Watching: SF FedViews: September 4, 2025

[from the Federal Reserve Bank of San Francisco]

Andrew Foerster, senior research advisor at the Federal Reserve Bank of San Francisco, shared views on the current economy and the outlook from the Economic Research Department as of September 4, 2025.

While economic activity in the United States has remained resilient, recent data show some softening in the labor market. Swings in net exports affected GDP in the first half of 2025, with imports surging in the first quarter followed by imports declining in the second quarter. Inflation remains above the Fed’s 2% goal, and a near-term rise from tariffs appears likely. Job gains in recent months have slowed. Downward revisions for recent job growth estimates have been large, but the magnitudes of these revisions are not out of line with historical values. Job growth estimates remain reliable despite data collection challenges. With the balance of risks surrounding the Fed’s dual mandate now shifting, market participants are projecting an easing of monetary policy in coming months.

Read the full article [archived PDF].

Price Revolutions and Their Historical Impact

In 1996, leading economic historian, David Hackett Fischer, published The Great Wave: Price Revolutions and the Rhythm of History. If you ponder the subtitle, you may grasp the work’s ambition.

Nobel Prize-winning economist Paul Krugman has been arguing with Fischer for many years that, in making the transition from business to historical cycles, Fischer’s position is problematic.

There are, of course, detailed histories of prices, such as Thomas Tooke’s A History of Prices and of the State of the Circulation during the Years 1793–1856 (6 volumes, 1838–1857).

In the first four volumes he treats (a) of the prices of corn, and the circumstances affecting prices; (b) the prices of produce other than corn; and (c) the state of the circulation. The two final volumes, written with William Newmarch, deal with railways, free trade, banking in Europe and the effects of new discoveries of gold.

Wikipedia (links added)

Tooke-type price histories are one thing, but what about Fischer’s price revolutions? Max Weber (who predates Fischer by almost a century) seems to endorse this concept. In Weber’s General Economic History (German: Wirtschaftsgeschichte), he writes:

The great price revolution of the 16th and 17th centuries provided a powerful lever for the specifically capitalistic tendencies of seeking profit through cheapening production and lowering the price. This revolution is rightly ascribed to the continuous inflow of precious metals, in consequence of the great overseas discoveries. It lasted from the thirties of the 16th century down to the time of the Thirty Years’ War, but affected different branches of economic life in quite different ways. In the case of agricultural products an almost universal rise in price set in, making it possible for them to go over to production for the market. It was quite otherwise with the course of prices for industrial products. By and large these remained stable or rose in price relatively little, thus really falling, in comparison with the agricultural products. This relative decline was made possible only through a shift in technology and economics, and exerted a pressure in the direction of increasing profit by repeated cheapening of production. Thus the development did not follow the order that capitalism set in first and the decline in prices followed, but the reverse; first the prices fell relatively and then came capitalism.

Max Weber, General Economic History, Collier Books (3rd printing), 1966, pages 230-231.

Notice the last sentence above, Weber explicitly describes price revolutions exactly as Fischer argues.

In the history books we read, the emphasis is always on colorful personalities, inventions and other more theatrical events. This obviously omits the idea of phenomena like price revolutions. We cannot explain history merely by these personalities; we need to zoom out and view the larger picture.

World-Watching: USDA GAIN Reports from 19 August 2025

[from the United States Department of Agriculture, Foreign Agricultural Service: Global Agricultural Information Network (GAIN)]

Australia: Stone Fruit Annual

Stone fruit production in Australia is forecast to decline in marketing year (MY) 2025/26, primarily due to the Bureau of Meteorology’s (BOM) projection of a wetter-than-average spring. If realized, these conditions are expected to negatively affect both yields and fruit quality. Cherry production is forecast to fall by ten percent, while peach and nectarine production is expected to drop by seven percent. Growing conditions to date have been favorable, with excellent winter chill hours supporting strong bud burst and production potential. However, the anticipated shift to wet spring weather is likely to undermine these early-season advantages. As a result, cherry exports are forecast to decrease by nine percent and peach and nectarine exports by seven percent. Imports, though starting from a low base, are projected to rise modestly in MY 2025/26.

Read the full article [archived PDF]

Chile: Stone Fruit Annual

Post projects exports of Chilean cherries to grow significantly in the coming years, driven by strong international demand, particularly from China. Post estimates cherry production in marketing year (MY) 2024/25 to reach 730,000 metric tons (MT), a 6.7 increase over MY 2024/25. Chilean cherry exports will increase by 7.2 percent reaching 670,000 MT. In MY 2024/25, Post estimates nectarine and peach production to total 205,000 MT, a 3.4 percent increase over MY 2024/25. Peach and nectarine exports will increase by 3.4 percent totaling 146,000 metric tons. This growth reflects the continued expansion of nectarine planting, which offsets the decline in fresh peach area planted.

Read the full article [archived PDF]

China: Call for Domestic Comments on 30 National Food Safety Standards

On August 1, 2025, the Chinese government announced a public comment period for 30 national food safety standards, open until September 26, 2025, via the national standards management system. The standards have not yet been notified to the WTO. This report includes an unofficial translation of the announcement and the list of standards, and stakeholders are advised to review the regulations for potential market or regulatory impacts.

Read the full article [archived PDF]

China: New CCP Regulation Expands Anti-Corruption and Frugality Measures

On May 18, 2025, the Chinese Communist Party and State Council issued a revised regulation on “Strict Economy and Opposing Waste by Party and Government Organs.” The regulation bans drinking alcohol at public receptions and events and discourages other forms of consumption that could be seen as extravagant. The FAS China offices are monitoring the potential impact on high-value U.S. agricultural products.

Read the full article [archived PDF]

China: Revised National Food Safety Standard for Paddy Rice Notified

On July 25, 2025, China notified a National Food Safety Standard for Paddy Rice to the WTO under G/TBT/N/CHN/2091. This national food safety standard includes mandatory requirements for quality, testing, inspection, packaging, and labeling of domestic and imported commercial paddy rice. This report provides an unofficial translation of the notified standard. Comments may be submitted to the China’s TBT National Notification and Enquiry Center at tbt@customs.gov.cn until August 24, 2025.

Read the full article [archived PDF]

Guatemala: Retail Foods Annual

Guatemala boasts a young population with a median age of 26 years and a growing middle class, driving increased demand for modern retail formats. However, traditional markets and informal retail remain prevalent across the country. In 2024, the United States exported $1.9 billion in agricultural and related products to Guatemala, with $886 million attributed to consumer-oriented goods. Key export categories included red meats, poultry, dairy products, fresh fruits, and processed vegetables.

Read the full article [archived PDF]

India: Cotton and Products Update

FAS Mumbai estimates MY 2025/26 India cotton production at 24.5 million 480-lb bales from 11.2 million hectares, down two percent from the previous estimate as farmers shift to higher-return crops like paddy, pulses, and cereals; kharif sowing decreased 2.4 percent from last year (as of August 1). An eight percent increase in the minimum support price (MSP) for medium- and long-staple cotton, effective October 1, is pushing fiber prices higher, encouraging mills to increase imports. Mill consumption is forecast at 25.7 million 480-lb bales, supported by steady yarn and apparel demand in key export markets and a potential export surge following ratification of the U.K.-India Comprehensive Economic and Trade Agreement (CETA).

Read the full article [archived PDF]

Japan: Stone Fruit Annual

Japan’s fresh cherry production for the 2025/26 marketing year (MY) is projected to be 12,500 tons. This forecast is a result of production losses caused by high temperatures during the pollination period in the country’s largest cherry-producing region. While this represents an 8.7 percent increase compared to the previous year’s historically poor harvest, it is expected to be a low yield year with a 25 percent decrease from the average production year. Due to the poor domestic production, demand for U.S. cherries is expected to remain strong for the 2025/26 MY, continuing the trend from the previous year. For peach production in Japan, the absolute number of fruits is anticipated to be equivalent to the previous year; however, the total production volume by weight is forecasted to decrease by approximately 10 percent because of high temperatures and low rainfall during the critical fruit growing period.

Read the full article [archived PDF]

Nicaragua: Nicaragua Peanut Report Annual

Nicaragua’s peanut farmers are expected to reduce harvested areas by at least five percent in marketing year (MY) 2025/26 in anticipation of lower prices due to increased Brazilian peanut production. FAS Managua expects farmers to be more rigorous in selecting production areas based on historical yields in MY 2025/26, excluding marginal lands with less fertile soil. Even with fluctuating market prices and adjustments to planted areas, Nicaragua is expected to remain a stable peanut producer in the region, with exports of shelled peanuts exceeding 70,000 metric tons annually.

Read the full article [archived PDF]

For more information, or for an archive of all FAS GAIN reports, please visit gain.fas.usda.gov.