Japan-Watching: BoJ’s Koeda Points to a Longer Hiking Cycle

Her potential-growth example implies a neutral rate around 2.8%, above the Bank’s published 2.5% ceiling and well above today’s 1.25% policy rate.

[by OKUBO Takuji]

Key Takeaways

  • Koeda, probably the most influential swing vote on the board, seemed slightly more hawkish in her speech on October 15. She stopped just short of calling the 2% target achieved.
  • Her conceptual example of a neutral rate, potential growth plus 2%, points to a neutral rate well above 2%. While she is not in a hurry to push for hikes as the two hawks are, she seems open to a protracted hiking cycle.
  • I continue to think an October hike is out of the question. Koeda’s openness to a hike marginally raises the possibility of a December hike. I still consider it highly unlikely, though.

Why Koeda matters

On October 15, 2026, KOEDA Junko [小枝淳子] made her 3rd speech since she joined the BoJ policy board in 2025. She is an ex-IMF academic and yield curve specialist. She is probably the most important and influential swing vote in the current BoJ board. In her speech [archived PDF] and the following press conference (Japan Macro Advisors’ unofficial transcript), she sounded more open to continued rate increases than the three BoJ executives, although she was careful not to give any indication of the timing of the next move.

The board is balanced at both ends

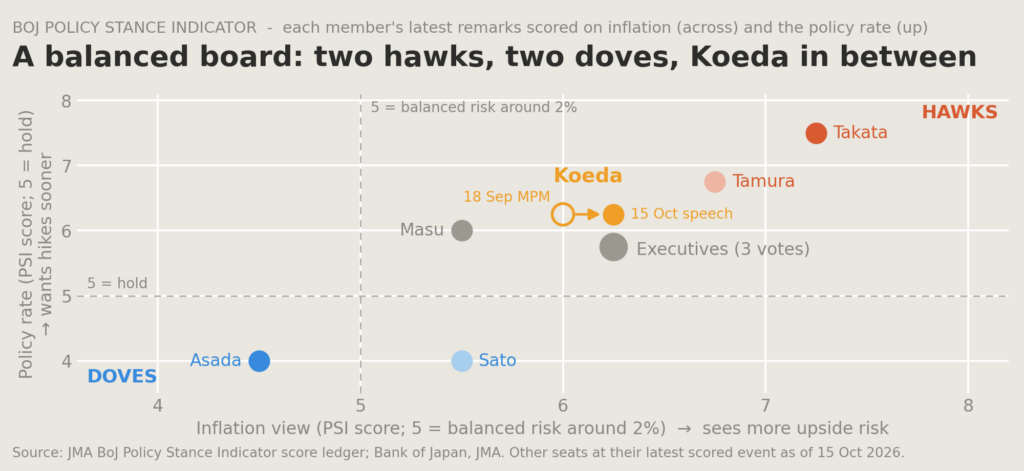
As you can see in chart 1, the board is evenly balanced with two hawks at top-right and two doves at bottom-left (if you are unfamiliar with the BoJ-Policy Stance Indicator framework, please see the Japan Macro Advisors primer). That leaves KOEDA Junko [小枝 淳子] and MASU Kazuyuki [増 一行] between the two ends, sitting with the three BoJ executives: the Governor and two Deputy Governors. As BoJ executives tend to vote together, Koeda and Masu cast critical swing votes.

Chart 1

Koeda sounded more hawkish than before

In her speech [archived PDF] and the following press conference (see the Japan Macro Advisors unofficial transcript), she seemed slightly more hawkish than I anticipated. Koeda judges trend inflation to be already about 2% overall and increasingly well-anchored. She stopped just short of saying the 2% target has been achieved. She said:

“For about a year now I have described underlying inflation as roughly 2% on the whole, and I have kept checking how firmly it is taking hold. On the CPI, as I noted at Chart 11, broad-based price increases have continued for several years, and the distribution of year-on-year changes by item also suggests that this is becoming established. Wages, too, have shown stable increases overall. For these reasons, I think Japan’s inflation is becoming more persistently entrenched than before.” [Kumamoto speech, 15 October 2026, Japan Macro Advisors translation]

Koeda also offered a simplified concept of the neutral rate as the potential growth rate plus the 2% inflation target. As the Bank’s latest potential-growth estimate is about 0.8%, this could put the nominal neutral rate at 2.8%, exceeding the top of the Bank’s published nominal range of 1.1–2.5%. She did offer another version that put the neutral rate at a lower level, but it was clear that she wanted to give a higher version of a potential neutral rate.

To be clear, she did not endorse 2.8% as a policy-rate destination. At the press conference, she said the potential-growth rule does not always hold and declined to give a point estimate. But her intention was most likely to nudge the neutral rate range higher.

Koeda was clear in her message that she is open to a rate hike. She said: “I do not think we need to be overly cautious about raising rates.” [speech, Japan Macro Advisors translation]

But she was quite evasive regarding the timing of the next hike. In the press conference, reporters repeatedly asked for her view on a back-to-back rate hike, a veiled way of asking whether an October hike is possible. She was quite firm in repeating her stance that she does not have any particular pace in mind. This was an interesting contrast with Governor Ueda’s dismissive comment on the possibility of a successive or oversized rate hike (see the Japan Macro Advisors September 18 report). That does not mean she endorsed consecutive hikes. It means she left the option more open than Ueda did.

Conclusion: More open to multiple hikes

By choosing potential growth plus 2% as an example of the neutral rate, Koeda seems to be creating more space for the policy rate to eventually rise above 2%, in my view. In terms of the timing for the next hike, she was non-committal. I would still consider an October hike out of the question, but her non-committal attitude does marginally raise the possibility of a December hike, although I still consider it highly unlikely.

Japan Inc. Now Sells No Yen to Invest Abroad

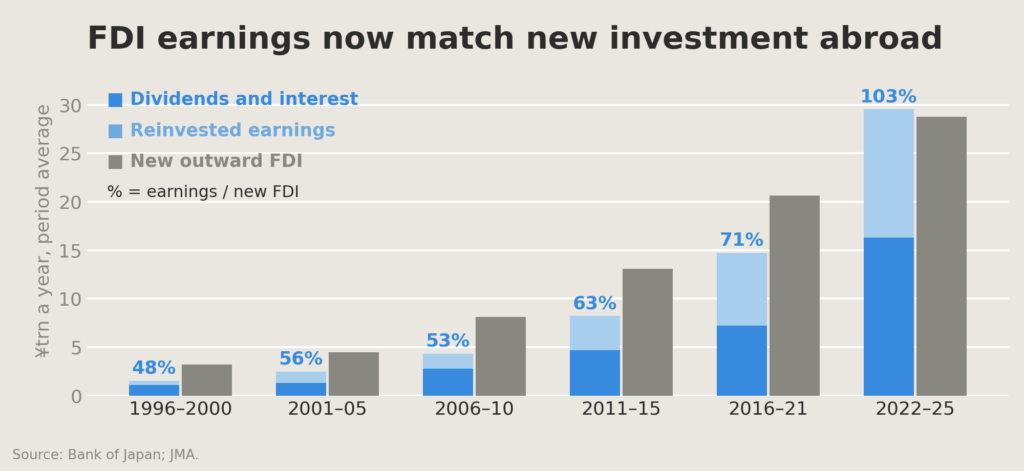
Earnings on Japan’s foreign direct investment (FDI) reached 103% of new FDI in 2022–25. With dividends and retained earnings counted together, Japan Inc. now needs to sell little yen to invest abroad.

[by OKUBO Takuji]

Key takeaways

  • Foreign affiliates now earn about as much as Japan invests abroad each year. Reinvested earnings, dividends and interest together reached 103% of new outward FDI in 2022–25, against 48% in 1996–2000.
  • Dividends from foreign affiliates account for a growing share of Japanese corporate profit. We estimate that foreign affiliates contributed 13.4% of Japan Inc.’s earnings in FY2025, up from 1.7% in FY1996.
  • Corporate investment abroad now involves little net yen selling. After dividends and interest paid home, the estimated outflow has been close to zero since 2022, down from about ¥5 trillion a year, or about 1% of GDP, on average in the 2010s.

Japan’s FDI stock now earns 103% of new investment

It is often said that Japan’s ageing population and slow growth give its companies too few investment opportunities at home. A Japanese government report in 2024 included the following passages.

“Japan’s ageing and shrinking population depresses expected demand at home. Expected returns remain higher abroad, so Japanese companies have accelerated outward direct investment” (my translation). — MATSUBAYASHI Yōichi [松林 洋一], MOF PRI, chapter 8, p.136.

“Companies invested abroad because they saw no promising investments in Japan; they are unlikely to bring back every return. On a cash-flow basis, the external balance is in deficit and is one factor behind the weak yen” (my translation). — KARAKAMA Daisuke [唐鎌 大輔], MOF PRI, chapter 10, pp.178 and 175.

However, my review of recent data shows that while their premise of low growth prospects in Japan is probably still right, the direct investment Japan has accumulated abroad has reached a level where it earns enough to cover Japan’s new investment abroad. This changes the exchange-rate implication even if Japan keeps investing abroad.

As chart 1 shows, earnings on the accumulated investment stock rose from 48% of new outward FDI in 1996–2000 to 103% in 2022–25.

Chart 1

Overseas affiliates pay interest and dividends to their parent companies in Japan. Those dividends have become a sizable part of corporate Japan’s income: we estimate that they made up 13.4% of Japanese corporate profit in FY2025, up from 1.7% in FY1996.

When foreign affiliates retain their earnings on their balance sheets, Japan’s balance of payments statistics record them as FDI from Japan, even though no money crosses the border. While the companies receiving FDI dividends and the companies paying for new FDI are not necessarily the same, Japan Inc. as a whole is now financing its FDI almost entirely from the earnings of its overseas affiliates. At the current level of FDI, little new yen needs to be converted into foreign currencies as Japan goes about investing abroad.

In the rest of this report, I explain how foreign direct investment by Japanese companies evolved, and its near-term outlook. This report is the third in a series on the yen repatriation theme that I have published over the past few weeks, following “Yen Repatriation Starts with the Whale”, on capital flows through Japan’s national pension funds, and “Mrs Watanabe No More”, on Japanese households’ assets invested abroad.

A strong yen helped drive Japan’s first outward FDI boom

Japan’s outward investment was heavily restricted after WWII, requiring case-by-case permission from the government. Approvals became more and more automatic over the years until outward investment became “free in principle” in 1980. Trade friction with the US-led Japanese carmakers to restrain their exports from 1981, pushing them to build factories abroad. The rapid appreciation of the yen was also a factor. The yen strengthened from ¥242 per dollar before the Plaza Accord in September 1985 to ¥121 by the end of 1987. Japanese producers had to move lower value-added work abroad. The strong yen also gave Japanese financial institutions sizable purchasing power for a while, until the stock and property bubbles burst in 1990 and 1991.

All of these factors contributed to a rapid increase in outward FDI through the 1980s and 1990s (chart 2).

Chart 2

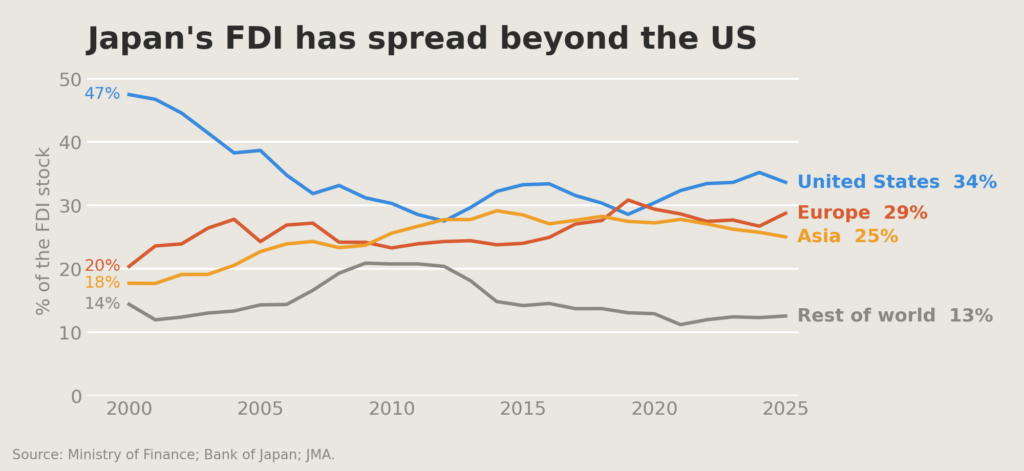
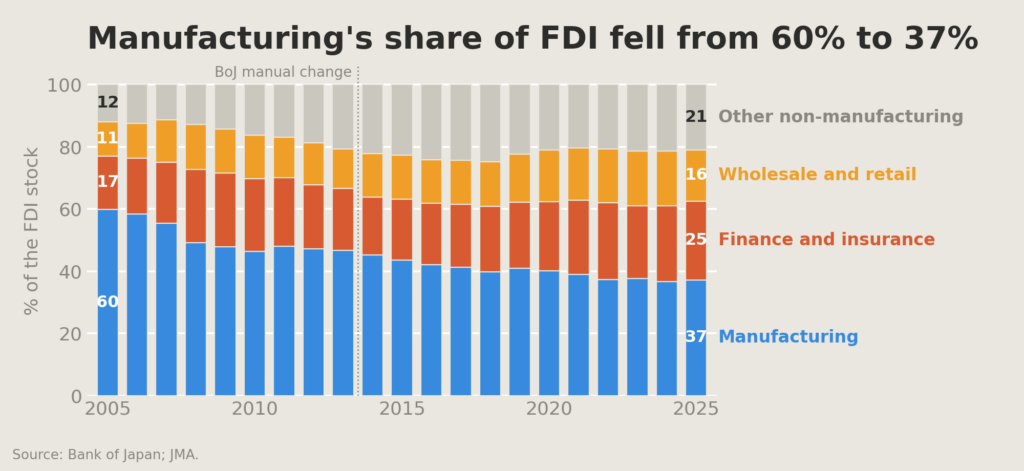
Even after the bubble burst, the strong yen kept pushing manufacturers to move abroad. In 2005, manufacturers accounted for 60% of the FDI stock. As Japanese manufacturers expanded their supply chains abroad, Asia’s share of outward FDI rose from about 12% in FY1986–90 to 19% in FY1995–99, and Asia held 23% of the FDI stock by 2005 (chart 3).

Chart 3

Japan’s outward FDI stock rose to 56% of GDP

The next phase was sustained by a different pressure. With weak growth and low interest rates at home, Japan Inc. kept investing abroad, across a broader range of industries. Between 1995 and 2025, the stock of FDI rose from 9% of Japan’s GDP to 58% (chart 4). In 2025, it is as large as about 38% of the private sector’s domestic fixed capital, on our estimate.

Chart 4

By industry composition and by destination compositions changed over time. Manufacturing’s share of the FDI stock had fallen to 37% by 2025, giving Japan’s FDI more breadth. By destination, we are seeing a revival of FDI toward the United States. It accounted for 34% of the stock in 2025, Europe 29% and Asia 25% (see earlier chart 3).

Thus, after decades of overseas investment, Japan’s FDI stock is now large enough that its earnings are sufficient to finance new investment abroad, at least for now. In the next section, I consider whether this will continue, and in particular whether Japanese companies may bring an even larger share of their overseas earnings back to Japan, given the weak yen, higher borrowing costs in yen and possibly better investment opportunities at home.

The weak yen has slowed offshoring, not reversed it

The real depreciation of the yen over the past 15 years made production in Japan more competitive. There is some evidence that manufacturers are considering bringing production back to Japan. The 2023 manufacturing white paper found more firms shifting production back from China than moving there, and they named the weak yen as one reason. We see some signs of reshoring. Japanese manufacturers’ overseas production ratio rose from 18.0% in FY2011 to 27.2% in FY2023, but it may have started to decline or at least stabilize. The ratio fell to 26.7% in FY2024. A Cabinet Office survey of listed manufacturers puts the ratio at 24.5% in FY2025, and their plan for FY2030 is broadly unchanged at 24.7%. The weak yen seems to have stabilized the wave of offshoring, but I see no firm evidence of a move back onshore yet.

Domestic investment has grown slowly despite the weak yen

There are tentative signs that domestic capital spending is starting to grow again. For three decades it grew at a very low speed. In real terms, private business investment rose only 26% between FY1997 and FY2025, less than 1% a year. In comparison, capital spending grew by about 4% a year on average in the United States. In my view, a weak currency is only one of the factors manufacturers weigh in designing their global production chains. The weak yen makes production in Japan competitive today, but they have also seen the exchange rate swing violently within short periods. Japan also has a shrinking population problem. It started to address it by opening a door to immigration, but the door is only tentatively open. Overall, my view is that the weak yen alone is unlikely to give Japan Inc. sufficient incentive to bring its capital back to Japan and to the yen.

Economic security is bringing some production home

The government is pushing harder than the currency, mostly in the name of economic security, even before the Takaichi government came along. The government currently has a ¥250 trillion domestic investment target for FY2040 and named AI and semiconductors among its 17 strategic fields. Semiconductors are where the money has gone furthest. In November 2024, under the Ishiba government, Japan committed more than ¥10 trillion of public support to AI and semiconductors by FY2030, aiming to draw more than ¥50 trillion of public and private investment over ten years. Japan managed to lure a TSMC plant to Japan, backed by a sizable subsidy. Rapidus, a government-supported Japanese semiconductor maker, has received a sizable subsidy and is building a factory in Hokkaido. Japan’s production of integrated circuits and discrete semiconductors rose from ¥2.7 trillion in 2019 to ¥4.1 trillion in 2025.

Under the name of economic security, the Japanese government is promoting other industries such as batteries, shipbuilding and pharmaceuticals. Defence spending adds to the push. Japan’s defence budget rose from about ¥5 trillion in FY2022 to ¥9.0 trillion in FY2026. Some defence contractors, such as Mitsubishi Heavy Industries, have doubled their defence revenue.

Japan’s industrial-policy record gives reason for caution

The Japanese government and the Ministry of Economy, Trade and Industry (METI), the key agency behind Japan’s industry policy, may claim some expertise in their industrial policies. Empirical studies in the past paint a poor track record, though. Rapidus, the most ambitious semiconductor project, has had no independent cost-benefit assessment (Negrine et al., 2025). While defence and economic security-driven policies have a different logic, I doubt that these industrial policies will succeed in bringing large-scale manufacturing investment back to Japan so long as macro factors such as Japan’s demography remain unfavourable.

FDI no longer appears to drive yen weakness

The weak yen and non-economic geopolitical factors do point to a halt in Japan’s four-decade offshoring trend, although it is a stabilization, rather than an economy-wide reversal of past offshoring. Japan Inc. will continue to invest more abroad, rather than within its borders. Given the sizable growth in the stock of cumulative FDI, Japan Inc. no longer needs to convert yen into overseas currency to keep investing abroad though. Net of dividends and interest paid home, Japan’s FDI sold about ¥5 trillion of yen a year, or about 1% of GDP, on average in the 2010s; since 2022 the net flow has been close to zero. There is also an interesting development in an effort to allow more share-exchange based M&A for cross-border deals that will further reduce the need for Japanese companies to spend their yen to purchase overseas assets. In my view, Japan Inc.’s FDI is no longer a factor to drive the yen weaker.

References

Japan-Watching: Yen Repatriation Starts with the Whale

GPIF, one of the largest national pension funds in the world, is likely to rebalance its assets from non-yen bonds to yen bonds, signaling a big turn in Japan’s cross-border capital flows.

[from Japan Macro Advisors, 10 September, 2026]

Key takeaways

  • In 2013, GPIF’s investment committee, chaired by UEDA Kazuo [植田和男], now the BoJ governor, saw a fair chance of a JGB crash within five to ten years. Its CEO priced the crash as the 10-year rising from 0.5% to 3%. Subsequently, GPIF cut its target weight for domestic bonds from 60% to 25% as an emergency measure against abnormally low yields.
  • The 10-year is now at 3%. On my replication of GPIF’s own allocation rule, a real return on JGBs near zero points to a 50% weight in domestic bonds, against 25% today. I expect GPIF to raise the weight, if it has not already started in the September quarter.
  • How GPIF decides its asset allocation and communicates it publicly is a very delicate and political issue. But regardless of how it communicates it, a change in asset allocation is inevitable. In my view, it signifies a big turn in Japan’s cross-border capital flows.

Japan has one of the Largest Pension Funds in the World

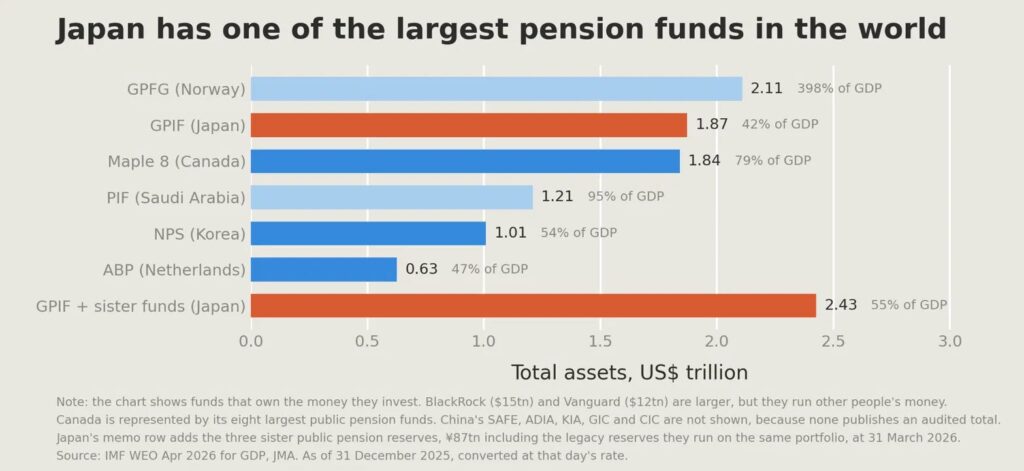
Japan has the second largest public pension fund in the world. Norway’s is the biggest, although it is not strictly a pension fund. Canada’s pension funds, when all eight of its variants are added together, come a close third.

Japan set up its first national pension fund in 1961 and it has since gone through various reforms and reorganization over the last 65 years. Its current form is called the Government Pension Investment Fund (GPIF). As explained in a later section, GPIF has a few siblings, and when we add them together, Japan’s public pension funds can be said to be the largest in the world.

Chart 1

GPIF used to invest most of its asset into JGBs

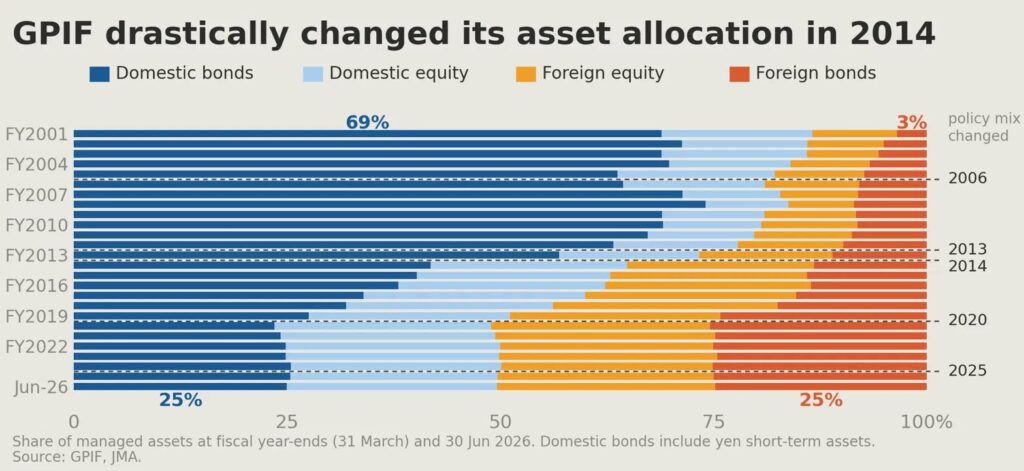
GPIF used to invest the majority of its fund as loans to the national government and into Japanese government bonds (JGBs). At the end of FY2012, 62% of its assets consisted of domestic bonds. However, in 2014 it went through a radical asset reallocation and the target weight for domestic bonds was reduced from 60% to 35%, and then further down to 25% in 2020. Its current target allocation is a clean four-way 25% split into domestic bonds, domestic equity, foreign equity and foreign bonds.

As one of the largest pension funds in the world, its asset allocations attract market attention and there is speculation that it is about to raise its allocation into domestic bonds. In my view, there is indeed a very high chance that GPIF will be raising its allocation into domestic bonds, if it has not already started to do so in the current quarter ending in September 2026.

Chart 2

UEDA in 2013 Saw a Bond Crash Coming

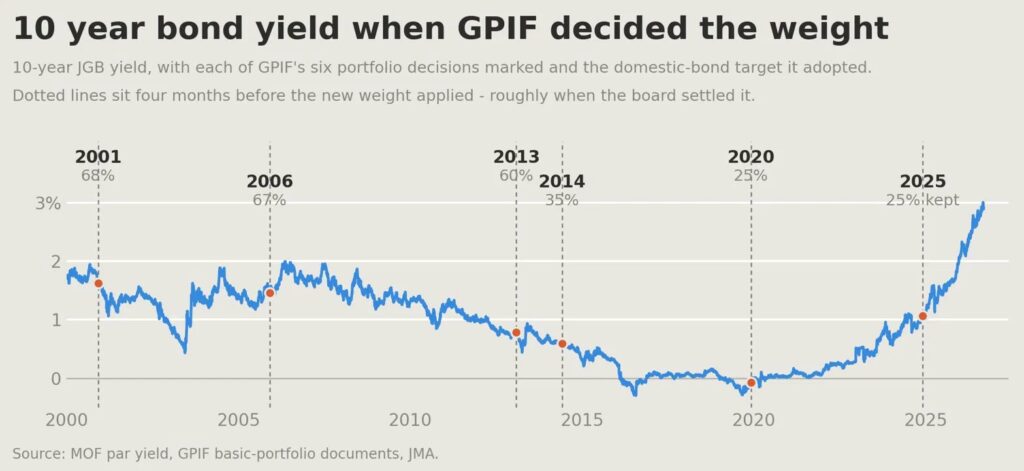
To understand why GPIF is highly likely to raise its allocation into domestic bonds, we need to go back in history to 2013. Why 2013? Of course, it is the year the Bank of Japan (BoJ) started its massive quantitative easing. The 10-year JGB yield started 2013 at 0.8% and it fell to 0.3% by the end of 2015 before briefly hitting a negative rate of -0.3% in 2016. If you were the chairperson of the GPIF investment committee, you would have been concerned about the wisdom of continuing to invest in JGBs at such a policy-driven low rate. The actual chairperson was UEDA Kazuo [植田和男], the current BoJ governor. In the minutes for October 2013, UEDA said, “I think there is a fair chance that bonds will crash at some point in the next five to ten years [unofficial translation].”

The minutes were released only seven years later; otherwise the use of the word “crash” would have been controversial.

GPIF CEO Priced the Crash at 3% in 2014. We Are There Now

If you read through the GPIF minutes between 2013 and 2014, you would see that GPIF officials were increasingly conscious of the precariousness of investing in JGBs. Long story short, as this process was highly political and a sensitive subject, they decided to radically lower the target allocation weight for JGBs to 35% in 2014, presented it as the result of a philosophical change in the way GPIF is managed and how the concept of “risk” should be considered. Investment in JGBs was no longer considered low risk in real terms. The asset allocation for domestic bonds was further lowered to 25% in 2020. The following is what MITANI Takahiro [三谷隆博], the GPIF CEO at the time and an ex-BoJ senior official, said in the October 2014 GPIF minutes.

“Yields are just under 0.5% now, so a move to near 3% would mean a loss of about ¥25 trillion. (…). So I think the clearest way to explain it is that reducing the weight on JGBs to some degree is simply unavoidable [unofficial translation]”

The 2014 cut in the weight was partly an emergency escape

As I wrote earlier, the radical asset reallocation in 2014 was part a shift in the concept of risk from “nominal” to “real”, so that JGB is no longer risk free assets. But the change was also at least partly an emergency measure to escape the abnormally low-yield environment. Then the next natural question is, now that the JGB yields are no longer abnormally low, what should happen to its asset allocation? Pensions are paid in yen, so long-duration Japanese government bonds are a natural match, while GPIF should also be holding some non-yen assets and equities to diversify its assets and protect the overall balance sheet from inflation. In the next section, I will show you a simplified replication of how GPIF decides its asset allocation and what GPIF’s asset allocation could be now that JGB yields are normal.

How GPIF decides its weights

Put simply, GPIF’s target weights are the output of an optimizer with a few rules. Find the portfolio that, at the required real return, has the smallest average shortfall below wage growth in the years when it falls short, and round it to the nearest 5%.

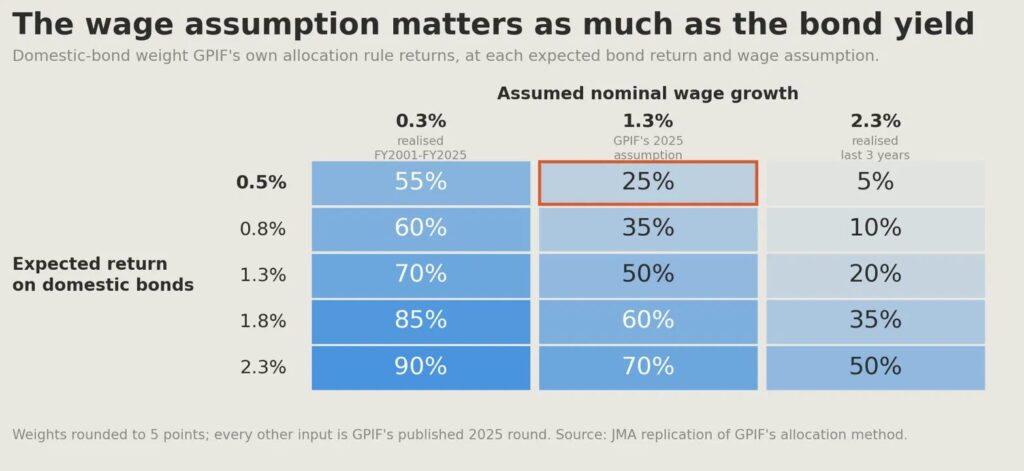
When GPIF last decided to keep the current 25% weight for domestic bonds in 2025, JGBs were assumed to produce a nominal return of 0.5% against wage growth of 1.3%, so a real return of minus 0.8%. Exhibit 1 shows a simplified matrix of weights depending on expected nominal return on bonds and wage growth. The red box shows the assumption behind the 2025 weights decision mentioned above. If we use a higher wage growth assumption of 2.3%, an expected nominal return of 1.8% on bonds gives a weight of 35%. GPIF’s bond portfolio has an average maturity around 10 years, and the 10-year bond is yielding 3% now. A lot of thought and estimation is needed to form a view on the expected real return on domestic bonds, but in my view, it is clear that the minus 0.8% used in their last review is too low given where bond yields are.

Why GPIF kept the weight in 2025 and why circumstances changed

In late 2024 when the GPIF was reviewing the weight as part of its five-year plan, the BoJ was already in the process of exiting from QE and raising its policy rate. However, the JGB market was still in the process of adjustment and bond yields had a lot of room to rise. For example, the 10-year yield was 0.89% at the end of September 2024, rose to 2% by the end of 2025 and now, in September 2026, stands at 3%. You can understand why GPIF decided to keep its weight on domestic bonds unchanged as it would have incurred capital losses on bond purchases in 2025. But in my view, as I wrote in the report “The Long Climb in JGB Yields Is Nearly Over” [archived PDF], long bond yields are getting closer to a stability point. If the GPIF board shares my view, it is a good time to think about raising its target weight into domestic yen bonds.

The Whale Problem and the Washington Problem

How high should the new weight be for domestic bonds? The reality of determining appropriate weights and how to announce it is a lot harder than the simplified model I explained above. Other than forming a reasonable view on the expected real return on asset classes, there are a few factors that complicate the process.

Firstly, GPIF needs to think about how such an announcement would affect the market. GPIF is what financial market professionals call a whale, a massive investor whose investment decisions sway market prices. There is also a related argument that given the dominance of GPIF in the domestic market, GPIF should be increasing its asset weight abroad to reduce its impact on domestic asset markets.

Secondly, changing asset allocation weights carries political considerations. If GPIF decides to raise the target weight for domestic bonds, foreign bonds are the likely asset class whose weight will go down. More than 50% of its foreign bonds are in US dollars. With all the news circulating in the market now, Scott Bessent will not like a public announcement that one of the largest pension funds in the world is reducing its purchase of US treasuries. There are domestic political considerations as well, as the Takaichi government contemplates how best to fund its deficits.

These are the issues GPIF officials must be debating. How GPIF decides its asset allocation in the near future will be a revealing case study for those who want to study how policy-making works in Japan. Those who are interested in this topic should read the transcripts of an interesting government committee in 2014 that focused on how GPIF could shield itself from political meddling. Guess who chaired the committee? UEDA Kazuo [植田和男].

Whatever the near-term decision GPIF makes regarding its target weight, I think it is fairly clear that GPIF should be increasing its investment into domestic bonds. The following table shows how much GPIF could buy in net terms, depending on the eventual rise in the target weight.

How much GPIF buys: ¥32tn at 35%, ¥80tn at 50%

Domestic Bond TargetGPIF BuysWith the Sister Funds
30%¥16tn¥20tn
35%¥32tn¥20tn
40%¥48tn¥20tn
50%¥80tn¥20tn

Additional domestic-bond holdings from re-weighting the fund at 30 June 2026 (managed assets ·317.8tn). Foreign bonds sold first.
Source: GPIF, JMA.

Three things in this table matter for the market. GPIF is allowed to deviate its asset allocation by six points either side of 25% without any announcement, so 39% target is already possible without any public announcement. In 2014 GPIF moved inside its band first and announced the new portfolio afterwards, and I would expect the same sequence this time. Second, these are static figures, which do not account for the growth of the fund over time.

The sister funds move with the whale

As mentioned earlier, GPIF has a few siblings. The Pension Fund Association for Local Government Officials (¥35.5tn), the Federation of National Public Service Personnel Mutual Aid Associations, known as KKR (¥11.5tn), and the Promotion and Mutual Aid Corporation for Private Schools of Japan (¥4.9tn) manage the pension reserves of local government employees, national government employees and private-school teachers. These sisters run their funds on the same 25/25/25/25 model, and with the legacy reserves they also run, they hold a further ¥87tn on top of GPIF’s.

Conclusion

GPIF cut its domestic bond weight from 60% to 35% in 2014, and later to 25%, to safeguard its assets from the manipulated low JGB yields at the time and the eventual crash they foresaw. That crash, as GPIF’s CEO MITANI defined it in 2014, has now happened with the 10-year yield rising to 3%. In my view, JGB yields have largely normalized and there is no emergency reason to avoid domestic bonds. It is only natural that GPIF would raise its allocation into domestic bonds, although how GPIF communicates this publicly is a touchy issue they need to figure out. When GPIF raises its domestic bond allocation, foreign bonds are the likely asset class to take the hit. GPIF publishes quarterly results and the next publication for the end-September 2026 quarter, expected in early November 2026, will be closely watched. Judging from market movements in the last few weeks, the market has started to sense that what I described in this article is already happening and Japanese money is starting to come back to the yen. While it should be characterized as rebalancing, rather than a repatriation, it seems we are observing a big turn in Japanese cross-border capital flows.

Rail Congestion Edges Up in Japan, but Far from Pre-Pandemic Levels

[from Nippon.com, August 24, 2026]

Rail congestion rose again in Japan [日本]’s major cities in fiscal 2025, but trains are still far less packed than they were before the pandemic.

Slight Rise in Tokyo

A report from the Ministry of Land, Infrastructure, Transport and Tourism [国土交通省] showed that the rail congestion rate in the Tokyo [東京都] metropolitan area rose slightly in fiscal 2025, but still remains low compared with before the pandemic.

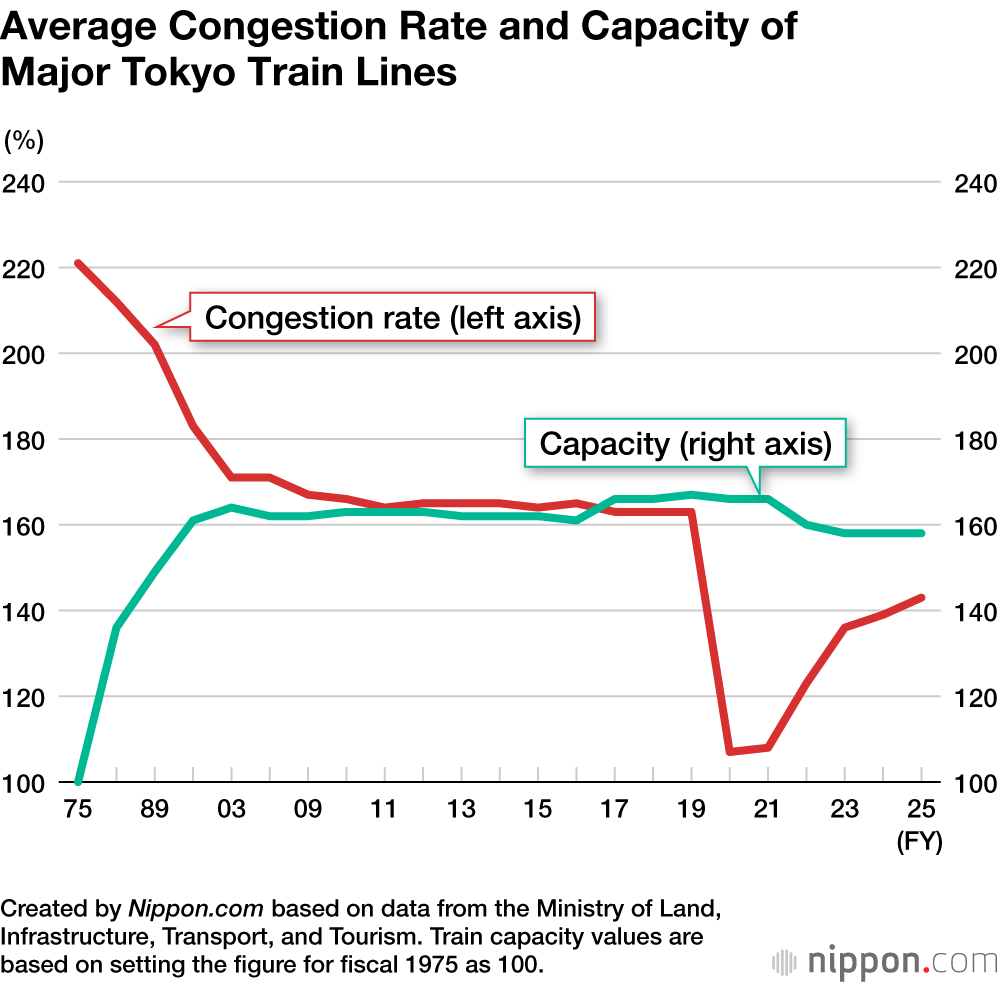
The average rate of congestion during peak morning hours for the Tokyo [東京都], Osaka [大阪市], and Nagoya [名古屋市] metropolitan areas was 143% (up 4 points year on year), 117% (up 1 point), and 126% (no change), respectively. After plunging in fiscal 2020 due to the pandemic, and remaining flat the following year, congestion rates have been rising since fiscal 2022.

The graph below shows the changes in rate of congestion and train capacity for 31 major train lines in the Tokyo metropolitan area. Before the pandemic, the rate was above 160%, but now it is around 20 points lower.

A congestion rate of 143%, or 43% more than the standard capacity, is characterized by a situation where passengers are able to either sit down, hold on to a strap, or hold on to a bar near the train door, but there is almost no direct physical contact with other riders.

On the most crowded lines, congestion rates in the Tokyo metropolitan area prior to the pandemic were close to 200%, a level at which there is considerable body contact and people near the doors are unable to move. However, the congestion rates for such lines in fiscal 2025 were much lower.

Data Sources

(Translated from Japanese.)

Japan-Watching: Economics in the Age of AI

A Thought Experiment Envisioning A “Fully Automated Society”

from REITI, by IKEUCHI Kenta [池内 健太], Senior Fellow (Policy Economist)

In a world where human labor has become unnecessary because of AI, what should be the focus of the study of economics? In the future, if AI and robots have become capable of producing all goods and services necessary for our society, what kind of economic problems could remain?

Of course, a fully automated society is not predicted for the near future. This article imagines such an extreme type of society as a thought experiment designed to consider economic systems in the age of AI. Here, a fully automated society refers not only to one in which corporate production is automated, but also to one in which the legislative, administrative, and judicial functions of government are substantially supported—and in some cases automated—by AI.

I started thinking about this matter when I heard from a researcher acquaintance that a paper concerning AI’s impact on employment had caused quite a stir on X, and I decided to read it out of curiosity. The paper discussed the possibility that AI-driven job cuts could reduce workers’ incomes, weaken consumer demand, and ultimately backfire on firms themselves (Falk and Tsoukalas 2026). Companies may earn higher profits in the short term by taking advantage of AI to cut back on personnel costs. However, if most companies follow that same approach, overall market demand would weaken because workers are also consumers.

The purpose of this article is not to question the validity of that paper’s argument. Rather, the focus is on what economic problems would remain in a future society if AI not only partially replaces human labor but also produces most goods and services.

Scarcity Will Continue to Be a Problem

There has already been extensive research regarding the impact of AI on employment. For example, Acemoğlu and Restrepo (2019) argued that while automation may replace existing human jobs, it may also create new ones. Moreover, the possibility that technological advances could free humans from labor and greatly alleviate economic problems was discussed long ago by Keynes (1930).

If AI and robots become capable of producing goods and services on a sufficiently large scale, would economic problems disappear? That would not necessarily be the case. Even in a fully automated society, scarce resources such as land, location, natural environments, energy, and rare metals will remain limited. Moreover, social status, influence, and political decision-making power are deeply connected to human intentions and perception, and cannot simply be delegated to AI. More land will not become available simply because more people wish to live in convenient urban locations. Quiet natural environments, advanced healthcare resources, social attention, and political influence also cannot be maximized for everyone at the same time.

Therefore, even in a fully automated society, some economic problems will remain. However, the main focus will shift from the “problem of insufficient ordinary commodities” to “how to allocate fundamentally scarce resources.” As production capacity increases, the value of true scarcity only becomes clearer.

In that case, the roles of markets and prices will still exist. Prices are not merely figures that allow for corporate earnings; they convey information about which resources are scarce and to what extent, how much demand there is for those resources, and what supply constraints there are. That perspective connects to a classic argument made by Hayek (1945), who argued that prices function as a mechanism through which dispersed information can be aggregated.

However, if AI becomes deeply integrated into the market, the concept of price itself may change. At present, prices serve as one-dimensional signals representing the levels of various factors, such as scarcity, quality, demand, supply, environmental impact, and future risks, expressed in terms of a single metric, that is, monetary value. If AI agents become capable of processing large volumes of information on behalf of consumers and companies, it is possible that multi-dimensional market signals that convey information concerning all those various factors, including quality, environmental impact, congestion, delivery time, reliability and social impact may come into use. Narita (2025) also discussed the possibility that the roles of money and prices may change, with more diverse evaluation standards becoming involved in economic coordination.

For People to Enjoy Affluence

In a fully automated society, how people participate in the market and society will become more important than ever. If the premise that people earn income through labor becomes obsolete, it will be necessary to develop a mechanism whereby purchasing power is distributed to everyone. In this context, universal basic income (UBI) may be reframed not only as relief for the unemployed, but as a form of fundamental purchasing power used by people to express their preferences. Managi [馬奈木 俊介] (2025) also pointed out that governance over the equitable distribution of the benefits of AI is essential.

Moreover, UBI may not be limited to simple monetary payments. In the future, UBI may take the form of a system combining other benefits as well, including energy use quotas, rights of access to basic healthcare services and education, and rights to refuse or control the use of personal data. In a fully automated society, UBI would therefore be a matter not only of how much to provide, but also of what kinds of access to guarantee and over what time horizon.

Another important issue is whether it is appropriate to treat people merely as consumers. In a fully automated society, the need for people to work for a living may diminish. However, even without such a necessity, humans will likely still possess the desire to create or to be creative. It is human nature to try new things and to try to surprise or impress other people. The spirit of fun and curiosity, a desire for self-expression, an inquisitive mind, and an appetite for challenges are deeply and fundamentally connected to human nature. Therefore, when designing a future UBI system, it will be important to treat people not merely as consumers but as agents who can participate in creation and exploration.

Additionally, the question of who owns and controls AI systems, robots, foundation models, and computing infrastructure is also a major issue. Even if a certain level of income is distributed to everyone, there may remain a power gap between those who control AI systems and robots and those who merely have access to them, in place of the income gap that currently exists in society.

All of the above-mentioned points for debate are relevant to the study of economics. How scarce resources should be allocated, how to guarantee people’s range of choices, and how to design ownership and controlling rights are problems central to economics. A fully automated society is not a near-future prediction. However, this extreme thought experiment serves as a useful guide for considering economic systems in the age of AI. Economics in the age of AI is not about discarding the intellectual legacy of economics, but about inheriting it and extending it toward a new society.

References

June 12, 2026

Economics-Watching: Bank of Japan Updates (June 25th)

[from the Bank of Japan (日本銀行), June 25, 2026]

Economic Activity, Prices, and Monetary Policy in Japan

Speech at a Meeting with Local Leaders in Hyogo

TAMURA Naoki [田村 直樹], Member of the Policy Board, June 25, 2026

Read the full translated speech [Archived PDF]

Flow of Funds Accounts (Retroactive Revision and 1st Quarter 2026, Preliminary Figures)

The Bank released the following data today.

The Overview of Japan, US, and the Euro area is renewed once a year after the Flow of Funds Accounts is released in June.

The Bank of Japan retroactively revises data for the Flow of Funds Accounts (FFA), in principle once a year, to reflect information updates, such as newly obtained source data and institutional changes, and to incorporate revised estimation methods. The retroactive revision of 2026 was implemented on June 25 and data from the first quarter of 2005 onward has been updated accordingly. The majority of the revision contents are unchanged from the Planned Retroactive Revision to the Flow of Funds Accounts [Archived PDF] released on May 25, 2026.

To download the retroactively revised data, please use the BOJ Time-Series Data Search.

Monthly Report on the Services Producer Price Index

Read the full May report [Archived PDF]

Updates to the Bank of Japan’s statistical data are available at BOJ Time-Series Data Search.

Japan-Watching: Ministry of Finance, Japan

Preliminary determination of Anti-Dumping Duty Investigation of Nickel-added cold-rolled stainless steel coil, sheet, and strip originating in the People’s Republic of China and the Separate Customs Territory of Taiwan, Penghu, Kinmen, and Matsu

  1. Upon receipt of an application from NIPPON STEEL CORPORATION [日本製鉄株式会社], Nippon Yakin Kogyo Co., Ltd. [日本冶金工業株式会社], NAS Stainless Steel Strip MFG. Co., Ltd. [ナス鋼帯株式会社の画像] and NIPPON KINZOKU CO., LTD. [日本金属株式会社] on May 12, 2025, the Ministry of Finance (MOF) [財務省] and the Ministry of Economy, Trade and Industry (METI) [経済産業省] began conducting an investigation since July 22, 2025, to determine whether or not to impose an anti-dumping duty on Nickel-added cold-rolled stainless-steel coil, sheet, and stripa originating in the People’s Republic of Chinab and the Separate Customs Territory of Taiwan, Penghu, Kinmen, and Matsu.
    1. Note: An alloy steel containing 10.5% or more of chromium and containing by weight more than 0.6% nickel. The characteristics of this product are that it combines corrosion resistance, the functionality of steel, and a beautiful and clean design by manufacturing methods. Also, it is used in various fields of demand.
    2. Note: Excluding the regions of Hong Kong and Macau.
  2. MOF and METI have explored objective evidence collected from interested parties, including suppliers in the People’s Republic of China and the Separate Customs Territory of Taiwan, Penghu, Kinmen, and Matsu, providing opportunities for them to present evidence and to express their views. As a result, MOF and METI today made a preliminary determination in the anti-dumping investigation of the product, presuming the fact of the importation of the dumped product and the fact of the material injury to the domestic industry caused by such importation. (Public Notice on June 19, 2026)

    MOF and METI will continue the investigation in accordance with the provisions of the international rules under the WTO Agreements and related domestic laws and regulations, providing the interested parties with an appropriate opportunity to present evidence and express their views relating to the preliminary determination.

    Following the further investigation, the Government of Japan will determine whether or not the product has been imported into Japan at dumped prices and if such dumped imports have caused material injury to the domestic industry, and make a decision whether or not to impose a definitive anti-dumping duty on the product.

    The interim report on preliminary determination offers details of the investigation.
Reference

Public Notice on June 19, 2026 [Archived PDF]

Interim report on preliminary determination [Archived PDF]

[Provisional Translation, June 19, 2026, Ministry of Finance, Ministry of Economy, Trade and Industry]

Extension of the Period of Investigation of Nickel-added cold-rolled stainless steel coil, sheet and strip originating in the People’s Republic of China and the Separate Customs Territory of Taiwan, Penghu, Kinmen, and Matsu

  1. With regard to the Anti-Dumping Duty Investigation on Nickel-added cold-rolled stainless-steel coil, sheet, and stripa originating in the People’s Republic of Chinab and the Separate Customs Territory of Taiwan, Penghu, Kinmen, and Matsu, the Ministry of Finance (MOF) [財務省] and the Ministry of Economy, Trade and Industry (METI) [経済産業省] have decided to extend the period of investigation by three months until September 21, 2026. The purpose of this extension is to carefully review the evidence and relevant documents submitted by interested parties, while ensuring full transparency and fairness throughout the investigation process.
    1. Note: An alloy steel containing 10.5% or more of chromium and containing by weight more than 0.6% nickel. The characteristics of this product are that it combines corrosion resistance, the functionality of steel, and a beautiful and clean design by manufacturing methods. Also, it is used in various fields of demand.
    2. Note: Excluding the regions of Hong Kong, China, and Macau, China.
  2. MOF and METI have been conducting the investigation since July 22, 2025. The investigation was to be concluded within one year, but the period can be extended by six months at most if it is found necessary for special reasons.
Reference

Notice of the Ministry of Finance Relating to the Extension of the Period of Investigation (No. 178, June 19, 2026) [Archived PDF]

[Provisional Translation, June 19, 2026, Ministry of Finance, Ministry of Economy, Trade and Industry]

Issues Re-opened through Liquidity Enhancement Auction on June 19, 2026

SecuritiesIssue NumbersRe-opened Amounts (billion yen face value)
10-Year363133.7
10-Year3648.4
10-Year36534.8
10-Year36927.7
10-Year37048.9
20-Year12875.1
20-Year129110.6
20-Year1329.0
20-Year1332.5
20-Year1364.9
20-Year14216.0
20-Year1436.8
20-Year1532.0
20-Year1549.9
20-Year1590.7
30-Year65.0
30-Year70.1
30-Year135.0
30-Year140.1
30-Year1514.1
30-Year160.2
30-Year1725.6
30-Year194.9
30-Year2053.0
30-Year238.6
30-Year2432.4
30-Year268.9

Result of Liquidity Enhancement Auction on June 19, 2026 (For JGB Market Special Participants)

Auction DateIssue DateAmounts of Competitive Bids (billion yen)Amounts of Bids Accepted (billion yen)Highest Accepted Spread*Allotment for Bids at the Highest Accepted SpreadAverage Accepted Spread*
6/196/221,897.8648.9+0.020%98.6666%+0.016%
Note

These columns indicate the spreads from the reference rate.

Auction Result of Treasury Discount Bills on June 19, 2026

Issue NumberAuction DateIssue DateMaturity DateAmounts of Compet. Bids (billion yen)Amounts of Bids Accepted (billion yen)Lowest Accepted Price (per 100 yen)Yield at the Lowest Accepted PriceAllotment for Bids at the Lowest Accepted PriceWeighted Average Price (per 100 yen)Yield at the Average PriceAmounts of Non-price compet. Auction Ⅰ* (billion yen)
13896/196/229/249,637.503,150.3899.76300.9224%79.2411%99.76600.9107%949.60
Note

For JGB Market Special Participants.

Interest Rate (June 2026)

Date1Y2Y3Y4Y5Y6Y7Y8Y9Y10Y15Y20Y25Y30Y40Y
6/11.123%1.4%1.558%1.775%1.948%2.094%2.243%2.397%2.538%2.682%3.225%3.567%3.871%3.863%3.8%
6/21.114%1.38%1.522%1.722%1.889%2.019%2.157%2.31%2.447%2.577%3.141%3.493%3.801%3.81%3.742%
6/31.126%1.401%1.56%1.767%1.943%2.077%2.219%2.373%2.508%2.645%3.183%3.521%3.817%3.817%3.748%
6/41.148%1.417%1.579%1.787%1.966%2.105%2.242%2.395%2.535%2.671%3.225%3.554%3.835%3.833%3.749%
6/51.14%1.412%1.574%1.778%1.955%2.096%2.233%2.391%2.532%2.669%3.222%3.551%3.838%3.841%3.753%
6/81.144%1.42%1.588%1.793%1.978%2.128%2.274%2.432%2.575%2.715%3.269%3.604%3.878%3.876%3.789%
6/91.146%1.42%1.582%1.784%1.962%2.101%2.242%2.398%2.537%2.669%3.217%3.543%3.824%3.823%3.759%
6/10%1.147%1.426%1.594%1.796%1.971%2.112%2.257%2.412%2.549%2.681%3.218%3.538%3.806%3.811%3.739%
6/111.149%1.427%1.592%1.792%1.963%2.108%2.258%2.411%2.551%2.682%3.23%3.554%3.821%3.823%3.774%
6/121.15%1.417%1.579%1.772%1.938%2.077%2.218%2.373%2.511%2.643%3.189%3.508%3.77%3.767%3.713%
6/151.141%1.409%1.556%1.743%1.901%2.039%2.175%2.322%2.46%2.589%3.143%3.461%3.73%3.725%3.674%
6/161.147%1.414%1.585%1.783%1.945%2.084%2.227%2.382%2.522%2.655%3.206%3.52%3.763%3.747%3.692%
6/171.139%1.398%1.552%1.745%1.897%2.034%2.182%2.335%2.479%2.613%3.17%3.49%3.741%3.709%3.654%
6/181.146%1.4%1.553%1.746%1.898%2.045%2.193%2.353%2.497%2.628%3.19%3.512%3.765%3.737%3.68%

Treasury Discount Bills to Be Auctioned on June 26, 2026

1. Auction Date:June 26, 2026
2. Issue Date:June 29, 2026
3. Maturity Date:September 28, 2026
4. Offering Amount:About 4,100 billion yen
5. Others:The above offering amount may be changed. In such a case, the revised amount will be announced on the day before the auction date.

[Provisional Translation, June 19, 2026, Ministry of Finance]

Economics-Watching: Where Could Reshoring Manufacturers Find Workers?

[from the Federal Reserve Bank of Cleveland, 9 October, 2025]

by Stephan D. Whitaker, Senior Policy Economist

The United States has lost millions of manufacturing jobs in recent decades, but a variety of policies have been enacted to incentivize the creation of manufacturing jobs in America. This District Data Brief analyzes where manufacturers might find US workers to fill these roles.

Introduction

The announcement of new tariffs this year has reignited the discussion of whether the United States can expand its manufacturing employment by millions of workers. Reversing decades of manufacturing job losses is one explicit goal of the new higher tariffs. This District Data Brief presents measures of employment and demographics as context around the current and potential employment in US manufacturing. Raising manufacturing employment by 4 to 6 million workers would constitute a large increase relative to current levels. However, an increase of this scale would not be large relative to the global growth of manufacturing employment in recent decades, the current US labor force size, or the number of US adults not engaged in high-paying work.

With different priorities and approaches, policymakers have spent much of the past decade addressing issues related to the loss or absence of manufacturing in the United States. For example, America’s dependence on imported manufactured goods was highlighted at the beginning of the COVID-19 pandemic as supply chain disruptions led to shortages of medical equipment, pharmaceuticals, microchips, and other products. The CHIPS and Science Act and the Inflation Reduction Act featured tax breaks and subsidies to expand US manufacturing capacity for semiconductors, electric vehicles, and renewable energy equipment.

At the same time, economists have been documenting the loss of work opportunities and earning power by workers without college degrees as manufacturing employment has declined. In 2013, David Autor, David Dorn, and Gordon Hanson published a study that estimated the labor market impacts resulting from increased trade competition following China’s entrance into the World Trade Organization, an effect often referred to as the “China shock.” Dozens of studies have since used the regional variation in job and income losses caused by the China shock to measure the adverse impacts of job displacement on family structures, crime, health, and other social indicators. Some supporters of industrial subsidies and higher tariffs have expressed the hope that these dynamics can be put into reverse.

Read the full article [archived PDF].