From the Corner Café to the Global Market: Building an Inclusive Intellectual Property System Across APEC

[from APEC News, by María Gloria Riethmüller Harland, Singapore]

Every day, I pass by small businesses that bring life to our neighborhoods. A corner café with its own blend, a family bakery known for its special recipe, a local designer selling clothes under her own brand. Few of them would think of themselves as intellectual property owners, yet in many ways they are.

Their innovative brands, recipes and ideas are often their most valuable assets. But for most small businesses, intellectual property still feels like something meant for large companies with legal teams.

Over the last two years of chairing the APEC Intellectual Property Rights Experts’ Group (IPEG), one conviction has only grown stronger. Intellectual property should not be a privilege for a few. It should be the foundation that lets anyone with a good idea earn from its expression and grow. It should spark more creativity across our region. It should help build new businesses, new jobs and shared prosperity.

In practice, for a small business owner, the system can feel complex, costly and hard to navigate. The landscape is also changing quickly, as new technologies and online trade reshape how ideas are made, shared and protected.

When IPEG was created in 1997, its focus was making global trade rules on intellectual property work between economies. Over time, its work has grown to place small businesses, along with women, young innovators and local communities, at the center.

Our work over the past two years has been about making that shift real.

Small businesses, big ideas

Micro, small and medium enterprises (MSMEs) account for more than 97 percent of businesses in the APEC region. The challenge is not whether they have valuable ideas, they do. The challenge is turning those ideas into growth.

Intellectual property can help small businesses protect what makes them different, secure finance and expand into new markets with confidence.

The difference can be striking. A study [archived PDF] by IP Australia found that new small businesses that filed for intellectual property in their first year were twice as likely to achieve strong sales and employment growth. Yet the study found that only a small fraction of MSMEs own intellectual property.

That is why small businesses sit at the heart of IPEG’s 2025-2026 Work Plan.

Some of the most valuable lessons came from simply listening. Last year August in Incheon, I moderated our Policy Dialogue on Intellectual Property for Business, with a focus on SMEs. Our conversations were honest and practical, from making the system more user-friendly for small business owners to the opportunities e-commerce opens for them.

Conversations matter, but only if they lead to change. This one did. Following the dialogue, the World Intellectual Property Organization (WIPO) offered member economies the opportunity to embark on a project, asking small businesses directly how they understand, use and perceive intellectual property, and what stands in their way. Such projects aim to help offices and policymakers across the region build systems and support around real needs, not assumptions.

When we met in Dalian this August, the progress was clear. Some economies shared how they are running training workshops that help firms, especially technology startups, identify and actively manage their intellectual property strategically. Others are offering support in valuing patents, so small businesses can use their inventions to secure loans.

Step by step, intellectual property is becoming a tool small business owners and innovators can actually use, not just one they hear about.

Keeping pace with technology

Technology is changing how ideas come to a reality and are sold. But it is also changing how we protect those inventions, giving intellectual property offices new tools to work faster, smarter while making systems simpler for business owners.

Take patents, which protect new inventions. To get one, an inventor has to prove their idea is genuinely new. With a record 3.7 million patent applications filed worldwide in 2024, that is no small task.

Artificial intelligence search tools can now help compare applications more thoroughly rather than simple keyword matches. Chatbots walk first-time applicants through the search process. New translation tools make it simpler to understand patents filed across the region.

For a small business, this is far from a technical detail. Faster and more accurate searches mean knowing early whether an idea is genuinely new, before spending money on an application and investing in their venture.

Used well, technology can turn a complex process into a quicker, clearer path to protection.

Every idea counts

But a system is only as strong as the people it reaches.

Women, for example, accounted for just 18 percent [archived PDF] of inventors named in international patent applications in 2024. For the people and communities behind unprotected good inventions, that means missed income, missed recognition and missed growth.

Changing that takes partnership. By enhancing dialogue with APEC’s Policy Partnership on Women and the Economy, IPEG can build women entrepreneurs’ know-how on using intellectual property to protect their brands and designs, helping them to grow internationally.

Every region also has its own valuable cultural or geographical assets, while communities also carry traditions passed down over generations, from recipes and crafts to songs and stories. They are not just part of communities’ heritage and pride. For many, these traditions and assets can become sources of income. Intellectual property plays a vital role here too.

Geographical indications, labels that tie a product’s name to its place of origin, are one way to do that. Across the region, they are helping more small local businesses and women-led enterprises stand out from imitations, reach new buyers and become more competitive.

Copyright is reaching folk art too, from traditional stories to music and designs. Clear rights give communities the confidence to share their traditions widely and give new generations a reason to keep creating with them.

Inclusion is not a side project for intellectual property. It is the test of whether the system works at all. When intellectual property reaches more people, more creations reach the world, benefiting workers, MSMEs, communities and consumers. That simple belief has guided IPEG’s work for the past two years.

In August, I chaired my final IPEG meeting in Dalian. What I value most is not any single outcome, but the spirit behind our work.

IPEG is a space for dialogue. A space to ensure intellectual property drives resilience, innovation and growth. A space where economies with different experiences work together to make intellectual property more meaningful and accessible.

That space matters more than ever. New technologies, new business models and new forms of creativity are creating both opportunities and challenges. I encourage IPEG to keep using this forum not only to exchange information, but to thinking creatively about where APEC cooperation can make more tangible differences.

Because in the end, the measure of our work is simple. It is whether the corner café, the family bakery and the young designer down the street can turn their innovations into a lasting livelihood.
María Gloria Riethmüller is the Chair of the APEC Intellectual Property Rights Experts’ Group (IPEG) and Legal Advisor at the Intellectual Property Department of Chile’s Undersecretariat of International Economic Affairs.

Japan Inc. Now Sells No Yen to Invest Abroad

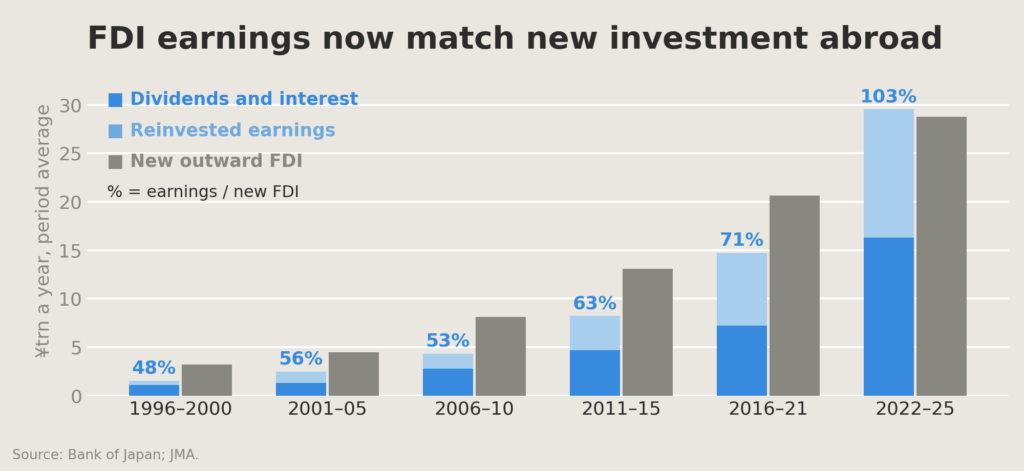
Earnings on Japan’s foreign direct investment (FDI) reached 103% of new FDI in 2022–25. With dividends and retained earnings counted together, Japan Inc. now needs to sell little yen to invest abroad.

[by OKUBO Takuji]

Key takeaways

  • Foreign affiliates now earn about as much as Japan invests abroad each year. Reinvested earnings, dividends and interest together reached 103% of new outward FDI in 2022–25, against 48% in 1996–2000.
  • Dividends from foreign affiliates account for a growing share of Japanese corporate profit. We estimate that foreign affiliates contributed 13.4% of Japan Inc.’s earnings in FY2025, up from 1.7% in FY1996.
  • Corporate investment abroad now involves little net yen selling. After dividends and interest paid home, the estimated outflow has been close to zero since 2022, down from about ¥5 trillion a year, or about 1% of GDP, on average in the 2010s.

Japan’s FDI stock now earns 103% of new investment

It is often said that Japan’s ageing population and slow growth give its companies too few investment opportunities at home. A Japanese government report in 2024 included the following passages.

“Japan’s ageing and shrinking population depresses expected demand at home. Expected returns remain higher abroad, so Japanese companies have accelerated outward direct investment” (my translation). — MATSUBAYASHI Yōichi [松林 洋一], MOF PRI, chapter 8, p.136.

“Companies invested abroad because they saw no promising investments in Japan; they are unlikely to bring back every return. On a cash-flow basis, the external balance is in deficit and is one factor behind the weak yen” (my translation). — KARAKAMA Daisuke [唐鎌 大輔], MOF PRI, chapter 10, pp.178 and 175.

However, my review of recent data shows that while their premise of low growth prospects in Japan is probably still right, the direct investment Japan has accumulated abroad has reached a level where it earns enough to cover Japan’s new investment abroad. This changes the exchange-rate implication even if Japan keeps investing abroad.

As chart 1 shows, earnings on the accumulated investment stock rose from 48% of new outward FDI in 1996–2000 to 103% in 2022–25.

Chart 1

Overseas affiliates pay interest and dividends to their parent companies in Japan. Those dividends have become a sizable part of corporate Japan’s income: we estimate that they made up 13.4% of Japanese corporate profit in FY2025, up from 1.7% in FY1996.

When foreign affiliates retain their earnings on their balance sheets, Japan’s balance of payments statistics record them as FDI from Japan, even though no money crosses the border. While the companies receiving FDI dividends and the companies paying for new FDI are not necessarily the same, Japan Inc. as a whole is now financing its FDI almost entirely from the earnings of its overseas affiliates. At the current level of FDI, little new yen needs to be converted into foreign currencies as Japan goes about investing abroad.

In the rest of this report, I explain how foreign direct investment by Japanese companies evolved, and its near-term outlook. This report is the third in a series on the yen repatriation theme that I have published over the past few weeks, following “Yen Repatriation Starts with the Whale”, on capital flows through Japan’s national pension funds, and “Mrs Watanabe No More”, on Japanese households’ assets invested abroad.

A strong yen helped drive Japan’s first outward FDI boom

Japan’s outward investment was heavily restricted after WWII, requiring case-by-case permission from the government. Approvals became more and more automatic over the years until outward investment became “free in principle” in 1980. Trade friction with the US-led Japanese carmakers to restrain their exports from 1981, pushing them to build factories abroad. The rapid appreciation of the yen was also a factor. The yen strengthened from ¥242 per dollar before the Plaza Accord in September 1985 to ¥121 by the end of 1987. Japanese producers had to move lower value-added work abroad. The strong yen also gave Japanese financial institutions sizable purchasing power for a while, until the stock and property bubbles burst in 1990 and 1991.

All of these factors contributed to a rapid increase in outward FDI through the 1980s and 1990s (chart 2).

Chart 2

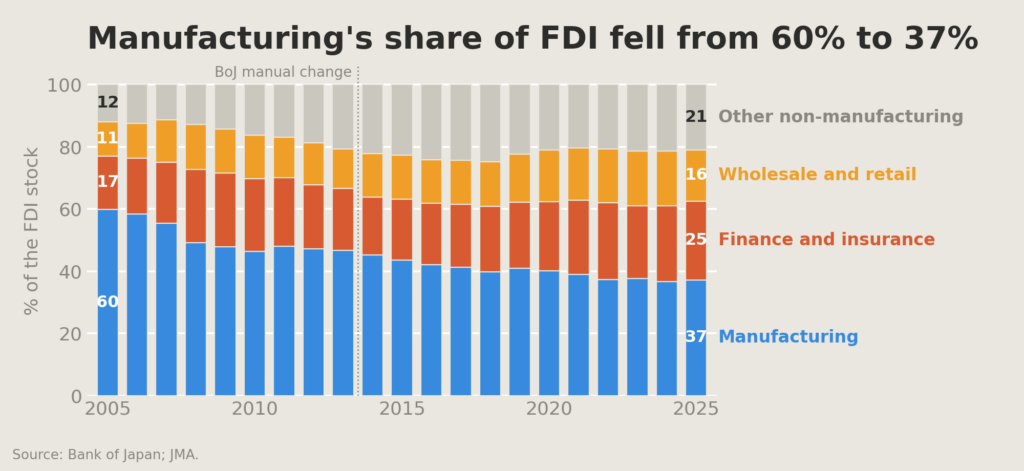
Even after the bubble burst, the strong yen kept pushing manufacturers to move abroad. In 2005, manufacturers accounted for 60% of the FDI stock. As Japanese manufacturers expanded their supply chains abroad, Asia’s share of outward FDI rose from about 12% in FY1986–90 to 19% in FY1995–99, and Asia held 23% of the FDI stock by 2005 (chart 3).

Chart 3

Japan’s outward FDI stock rose to 56% of GDP

The next phase was sustained by a different pressure. With weak growth and low interest rates at home, Japan Inc. kept investing abroad, across a broader range of industries. Between 1995 and 2025, the stock of FDI rose from 9% of Japan’s GDP to 58% (chart 4). In 2025, it is as large as about 38% of the private sector’s domestic fixed capital, on our estimate.

Chart 4

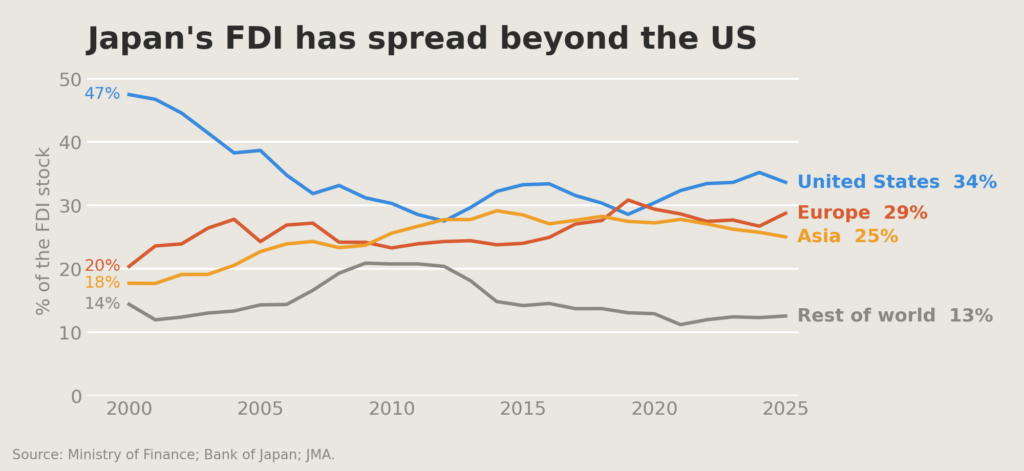
By industry composition and by destination compositions changed over time. Manufacturing’s share of the FDI stock had fallen to 37% by 2025, giving Japan’s FDI more breadth. By destination, we are seeing a revival of FDI toward the United States. It accounted for 34% of the stock in 2025, Europe 29% and Asia 25% (see earlier chart 3).

Thus, after decades of overseas investment, Japan’s FDI stock is now large enough that its earnings are sufficient to finance new investment abroad, at least for now. In the next section, I consider whether this will continue, and in particular whether Japanese companies may bring an even larger share of their overseas earnings back to Japan, given the weak yen, higher borrowing costs in yen and possibly better investment opportunities at home.

The weak yen has slowed offshoring, not reversed it

The real depreciation of the yen over the past 15 years made production in Japan more competitive. There is some evidence that manufacturers are considering bringing production back to Japan. The 2023 manufacturing white paper found more firms shifting production back from China than moving there, and they named the weak yen as one reason. We see some signs of reshoring. Japanese manufacturers’ overseas production ratio rose from 18.0% in FY2011 to 27.2% in FY2023, but it may have started to decline or at least stabilize. The ratio fell to 26.7% in FY2024. A Cabinet Office survey of listed manufacturers puts the ratio at 24.5% in FY2025, and their plan for FY2030 is broadly unchanged at 24.7%. The weak yen seems to have stabilized the wave of offshoring, but I see no firm evidence of a move back onshore yet.

Domestic investment has grown slowly despite the weak yen

There are tentative signs that domestic capital spending is starting to grow again. For three decades it grew at a very low speed. In real terms, private business investment rose only 26% between FY1997 and FY2025, less than 1% a year. In comparison, capital spending grew by about 4% a year on average in the United States. In my view, a weak currency is only one of the factors manufacturers weigh in designing their global production chains. The weak yen makes production in Japan competitive today, but they have also seen the exchange rate swing violently within short periods. Japan also has a shrinking population problem. It started to address it by opening a door to immigration, but the door is only tentatively open. Overall, my view is that the weak yen alone is unlikely to give Japan Inc. sufficient incentive to bring its capital back to Japan and to the yen.

Economic security is bringing some production home

The government is pushing harder than the currency, mostly in the name of economic security, even before the Takaichi government came along. The government currently has a ¥250 trillion domestic investment target for FY2040 and named AI and semiconductors among its 17 strategic fields. Semiconductors are where the money has gone furthest. In November 2024, under the Ishiba government, Japan committed more than ¥10 trillion of public support to AI and semiconductors by FY2030, aiming to draw more than ¥50 trillion of public and private investment over ten years. Japan managed to lure a TSMC plant to Japan, backed by a sizable subsidy. Rapidus, a government-supported Japanese semiconductor maker, has received a sizable subsidy and is building a factory in Hokkaido. Japan’s production of integrated circuits and discrete semiconductors rose from ¥2.7 trillion in 2019 to ¥4.1 trillion in 2025.

Under the name of economic security, the Japanese government is promoting other industries such as batteries, shipbuilding and pharmaceuticals. Defence spending adds to the push. Japan’s defence budget rose from about ¥5 trillion in FY2022 to ¥9.0 trillion in FY2026. Some defence contractors, such as Mitsubishi Heavy Industries, have doubled their defence revenue.

Japan’s industrial-policy record gives reason for caution

The Japanese government and the Ministry of Economy, Trade and Industry (METI), the key agency behind Japan’s industry policy, may claim some expertise in their industrial policies. Empirical studies in the past paint a poor track record, though. Rapidus, the most ambitious semiconductor project, has had no independent cost-benefit assessment (Negrine et al., 2025). While defence and economic security-driven policies have a different logic, I doubt that these industrial policies will succeed in bringing large-scale manufacturing investment back to Japan so long as macro factors such as Japan’s demography remain unfavourable.

FDI no longer appears to drive yen weakness

The weak yen and non-economic geopolitical factors do point to a halt in Japan’s four-decade offshoring trend, although it is a stabilization, rather than an economy-wide reversal of past offshoring. Japan Inc. will continue to invest more abroad, rather than within its borders. Given the sizable growth in the stock of cumulative FDI, Japan Inc. no longer needs to convert yen into overseas currency to keep investing abroad though. Net of dividends and interest paid home, Japan’s FDI sold about ¥5 trillion of yen a year, or about 1% of GDP, on average in the 2010s; since 2022 the net flow has been close to zero. There is also an interesting development in an effort to allow more share-exchange based M&A for cross-border deals that will further reduce the need for Japanese companies to spend their yen to purchase overseas assets. In my view, Japan Inc.’s FDI is no longer a factor to drive the yen weaker.

References

Japan-Watching: Economics in the Age of AI

A Thought Experiment Envisioning A “Fully Automated Society”

from REITI, by IKEUCHI Kenta [池内 健太], Senior Fellow (Policy Economist)

In a world where human labor has become unnecessary because of AI, what should be the focus of the study of economics? In the future, if AI and robots have become capable of producing all goods and services necessary for our society, what kind of economic problems could remain?

Of course, a fully automated society is not predicted for the near future. This article imagines such an extreme type of society as a thought experiment designed to consider economic systems in the age of AI. Here, a fully automated society refers not only to one in which corporate production is automated, but also to one in which the legislative, administrative, and judicial functions of government are substantially supported—and in some cases automated—by AI.

I started thinking about this matter when I heard from a researcher acquaintance that a paper concerning AI’s impact on employment had caused quite a stir on X, and I decided to read it out of curiosity. The paper discussed the possibility that AI-driven job cuts could reduce workers’ incomes, weaken consumer demand, and ultimately backfire on firms themselves (Falk and Tsoukalas 2026). Companies may earn higher profits in the short term by taking advantage of AI to cut back on personnel costs. However, if most companies follow that same approach, overall market demand would weaken because workers are also consumers.

The purpose of this article is not to question the validity of that paper’s argument. Rather, the focus is on what economic problems would remain in a future society if AI not only partially replaces human labor but also produces most goods and services.

Scarcity Will Continue to Be a Problem

There has already been extensive research regarding the impact of AI on employment. For example, Acemoğlu and Restrepo (2019) argued that while automation may replace existing human jobs, it may also create new ones. Moreover, the possibility that technological advances could free humans from labor and greatly alleviate economic problems was discussed long ago by Keynes (1930).

If AI and robots become capable of producing goods and services on a sufficiently large scale, would economic problems disappear? That would not necessarily be the case. Even in a fully automated society, scarce resources such as land, location, natural environments, energy, and rare metals will remain limited. Moreover, social status, influence, and political decision-making power are deeply connected to human intentions and perception, and cannot simply be delegated to AI. More land will not become available simply because more people wish to live in convenient urban locations. Quiet natural environments, advanced healthcare resources, social attention, and political influence also cannot be maximized for everyone at the same time.

Therefore, even in a fully automated society, some economic problems will remain. However, the main focus will shift from the “problem of insufficient ordinary commodities” to “how to allocate fundamentally scarce resources.” As production capacity increases, the value of true scarcity only becomes clearer.

In that case, the roles of markets and prices will still exist. Prices are not merely figures that allow for corporate earnings; they convey information about which resources are scarce and to what extent, how much demand there is for those resources, and what supply constraints there are. That perspective connects to a classic argument made by Hayek (1945), who argued that prices function as a mechanism through which dispersed information can be aggregated.

However, if AI becomes deeply integrated into the market, the concept of price itself may change. At present, prices serve as one-dimensional signals representing the levels of various factors, such as scarcity, quality, demand, supply, environmental impact, and future risks, expressed in terms of a single metric, that is, monetary value. If AI agents become capable of processing large volumes of information on behalf of consumers and companies, it is possible that multi-dimensional market signals that convey information concerning all those various factors, including quality, environmental impact, congestion, delivery time, reliability and social impact may come into use. Narita (2025) also discussed the possibility that the roles of money and prices may change, with more diverse evaluation standards becoming involved in economic coordination.

For People to Enjoy Affluence

In a fully automated society, how people participate in the market and society will become more important than ever. If the premise that people earn income through labor becomes obsolete, it will be necessary to develop a mechanism whereby purchasing power is distributed to everyone. In this context, universal basic income (UBI) may be reframed not only as relief for the unemployed, but as a form of fundamental purchasing power used by people to express their preferences. Managi [馬奈木 俊介] (2025) also pointed out that governance over the equitable distribution of the benefits of AI is essential.

Moreover, UBI may not be limited to simple monetary payments. In the future, UBI may take the form of a system combining other benefits as well, including energy use quotas, rights of access to basic healthcare services and education, and rights to refuse or control the use of personal data. In a fully automated society, UBI would therefore be a matter not only of how much to provide, but also of what kinds of access to guarantee and over what time horizon.

Another important issue is whether it is appropriate to treat people merely as consumers. In a fully automated society, the need for people to work for a living may diminish. However, even without such a necessity, humans will likely still possess the desire to create or to be creative. It is human nature to try new things and to try to surprise or impress other people. The spirit of fun and curiosity, a desire for self-expression, an inquisitive mind, and an appetite for challenges are deeply and fundamentally connected to human nature. Therefore, when designing a future UBI system, it will be important to treat people not merely as consumers but as agents who can participate in creation and exploration.

Additionally, the question of who owns and controls AI systems, robots, foundation models, and computing infrastructure is also a major issue. Even if a certain level of income is distributed to everyone, there may remain a power gap between those who control AI systems and robots and those who merely have access to them, in place of the income gap that currently exists in society.

All of the above-mentioned points for debate are relevant to the study of economics. How scarce resources should be allocated, how to guarantee people’s range of choices, and how to design ownership and controlling rights are problems central to economics. A fully automated society is not a near-future prediction. However, this extreme thought experiment serves as a useful guide for considering economic systems in the age of AI. Economics in the age of AI is not about discarding the intellectual legacy of economics, but about inheriting it and extending it toward a new society.

References

June 12, 2026

World-Watching: Minutes of the Monetary Policy Committee — Copom

272nd Meeting – July 29-30, 2025

[from the Central Bank of Brazil, 5 August, 2025]

  1. Update of the economic outlook and the Copom’s scenario1
    1. The global environment is more adverse and uncertain due to the economic policy and economic outlook in the United States, mainly regarding its trade and fiscal policies and their effects.
    2. Therefore, the behavior and the volatility of different asset classes have been impacted, altering global financial conditions. This scenario requires particular caution from emerging market economies amid heightened geopolitical tensions.
    3. Regarding the domestic scenario, the set of indicators on economic activity has shown some moderation in growth, as expected, but the labor market is still showing strength.
    4. In recent releases, headline inflation and measures of underlying inflation remained above the inflation target. Inflation expectations for 2025 and 2026 collected by the Focus survey remained above the inflation target and stand at 5.1% and 4.4%, respectively.
  2. Scenarios and risk analysis
    1. The inflation outlook remains challenging in several dimensions. Copom assessed the international scenario, economic activity, aggregate demand, inflation expectations, and current inflation. Copom then discussed inflation projections and expectations before deliberating on the current decision and future communication.
    2. The global environment is more adverse and uncertain. If, on the one hand, the approval of certain trade agreements, along with recent inflation and economic activity data from the U.S., could suggest a reduction in global uncertainty, on the other hand, the U.S. fiscal policy—and, particularly for Brazil, the U.S. trade policy—make the outlook more uncertain and adverse. The increase of trade tariffs by the U.S. to Brazil has significant sectoral impacts and still uncertain aggregate effects that depend on the unfolding of the next steps in the negotiations and the perception of risk inherent to this process. The Committee is closely monitoring the potential impacts on the real economy and financial assets. The prevailing assessment within the Committee is the increased global outlook uncertainty, and, therefore, Copom should maintain a cautious stance. As usual, the Committee will focus on the transmission mechanisms from the external environment to the domestic inflation dynamics and their impact on the outlook.
    3. The domestic economic activity outlook has indicated a certain moderation in growth, while also presenting mixed data across sectors and indicators.
    4. Overall, some moderation in growth is observed, supporting the scenario outlined by the Committee. This moderation, necessary for the widening of the output gap and the convergence of inflation to the target, is aligned with a contractionary monetary policy. Monthly sectoral surveys and more timely consumption data support a gradual slowdown in growth.
    5. At turning points in the economic cycle, it is natural to observe mixed signals from economic indicators—some leading, others lagging—as well as from comparisons between markets, such as the credit and labor markets.
    6. The credit market, which is more sensitive to financial conditions, has shown clearer moderation. A decline in non-earmarked credit granting and an increase in interest and delinquency rates have been observed. Moreover, regarding household credit, there has been an increase in the household debt–service ratio and a deepening of the negative credit flow—that is, households repaying more debt than taking on. It was emphasized during the discussion that some recent measures, such as private payroll-deducted loans, have had less impact than many market participants expected. Given the implementation agenda in this credit line, as well as the effects of introducing and removing taxes on other credit modalities, the Committee believes it should closely monitor upcoming credit data releases.
    7. In contrast to the credit market, the labor market remains dynamic. Both from the perspective of income—with real gains consistently above productivity—and employment—with a significant decrease in the unemployment rate to historically low levels—the labor market has greatly supported consumption and income.
    8. Thus, the Committee assesses that the signals from demand and economic activity so far suggest that the scenario is unfolding as expected and is consistent with the current monetary policy. The Committee reiterates that the aggregate demand slowdown is an essential element of supply–demand rebalancing in the economy and convergence of inflation to the target.
    9. Fiscal policy has a short-term impact, mainly through stimulating aggregate demand, and a more structural dimension, which has the potential to affect perceptions of debt sustainability and influence the term premium in the yield curve. A fiscal policy that acts counter-cyclically and contributes to reducing the risk premium favors the convergence of inflation to the target. Copom reinforced its view that the slowdown in structural reform efforts and fiscal discipline, the increase in earmarked credit, and uncertainties over the public debt stabilization have the potential to raise the economy’s neutral interest rate, with deleterious impacts on the power of monetary policy and, consequently, on the cost of disinflation in terms of activity. The Committee remained firmly convinced that policies must be predictable, credible, and countercyclical. In particular, the Committee’s discussion once again highlighted the need for harmonious fiscal and monetary policy.
    10. Inflation expectations, as measured by different instruments and obtained from various groups of agents, remained above the inflation target at all horizons, maintaining the adverse inflation outlook. For shorter-term horizons, following the release of the most recent data, there has been a decline in inflation expectations. For longer-term horizons, conversely, there has been no significant change in inflation expectations between Copom meetings, even though measures of breakeven inflation extracted from financial assets have declined. The Committee reaffirmed and renewed its commitment to re-anchoring expectations and to conducting a monetary policy that supports such a movement.
    11. De-anchored inflation expectations is a factor of discomfort shared by all Committee members and must be tamed. Copom highlighted that environments with de-anchored expectations increase the disinflation cost in terms of activity. The scenario of inflation convergence to the target becomes more challenging with de-anchored expectations for longer horizons. When discussing this topic, the main conclusion obtained and shared by all members of Copom was that, in an environment of de-anchored expectations—as currently is the case—greater monetary restriction is required for a longer period than would be otherwise appropriate.
    12. The inflation scenario has continued to show downside surprises in recent periods compared with analysts’ forecasts, but inflation has remained above the target Industrial goods inflation, which has already been showing weaker wholesale price pressures, continued to ease in the more recent period. Food prices also displayed slightly weaker-than-expected dynamics. Finally, services inflation, which has greater inertia, remains above the level required to meet the inflation target, in a context of a positive output gap. Beyond the changes in items, or even short-term oscillations, the core inflation measures have remained above the value consistent with the target achievement for months, corroborating the interpretation that inflation is pressured by demand and requires a contractionary monetary policy for a very prolonged period.
    13. Copom then addressed the projections. In the reference scenario, the interest rate path is extracted from the Focus survey, and the exchange rate starts at USD/BRL 5.552 and evolves according to the purchasing power parity (PPP). The Committee assumes that oil prices follow approximately the futures market curve for the following six months and then start increasing 2% per year onwards. Moreover, the energy tariff flag is assumed to be “green” in December of the years 2025 and 2026.
    14. In the reference scenario, four-quarter inflation projections for 2025 and for 2026 are 4.9% and 3.6%, respectively (Table 1). For the relevant horizon for monetary policy—2027 Q1—the inflation projection based on the reference scenario extracted from the Focus survey remained at 3.4%, above the inflation target.
    15. Regarding the balance of risks, it was assessed that the scenario of greater uncertainty continues to present higher-than-usual upside and downside inflation risks to the inflation outlook. Copom assessed that, among the upside risks for the inflation outlook and inflation expectations, it should be emphasized (i) a more prolonged period of de-anchoring of inflation expectations; (ii) a stronger-than-expected resilience of services inflation due to a more positive output gap; and (iii) a conjunction of internal and external economic policies with a stronger-than-expected inflationary impact, for example, through a persistently more depreciated currency. Among the downside risks, it should be noted (i) a greater-than-projected deceleration of domestic economic activity, impacting the inflation scenario; (ii) a steeper global slowdown stemming from the trade shock and the scenario of heightened uncertainty; and (iii) a reduction in commodity prices with disinflationary effects.
    16. Prospectively, the Committee will continue monitoring the pace of economic activity, which is a fundamental driver of inflation, particularly services inflation; the exchange rate pass-through to inflation, after a process of increased exchange rate volatility; and inflation expectations, which remain de-anchored and are drivers of future inflation behavior. It was emphasized that inflationary vectors remain adverse, such as the economic activity resilience and labor market pressures, de-anchored inflation expectations, and high inflation projections. This scenario prescribes a significantly contractionary monetary policy for a very prolonged period to ensure the convergence of inflation to the target.
  3. Discussion of the conduct of monetary policy
    1. Copom then discussed the conduct of monetary policy, considering the set of projections evaluated, as well as the balance of risks for prospective inflation.
    2. Following a swift and firm interest rate hike cycle, the Committee anticipates, as its monetary policy strategy, continuity of the interruption of the rate hiking cycle to observe the effects of the cycle already implemented. It was emphasized that, once the appropriate interest rate is determined, it should remain at a significantly contractionary level for a very prolonged period due to de-anchored expectations. The Committee emphasizes that it will remain vigilant, that future monetary policy steps can be adjusted and that it will not hesitate to proceed with the rate hiking cycle if appropriate.
  4. Monetary policy decision
    1. The Committee has been closely monitoring with particular attention the announcements regarding the imposition by the U.S. of trade tariffs on Brazil, reinforcing its cautious stance in a scenario of heightened uncertainty. Moreover, it continues to monitor how the developments on the fiscal side impact monetary policy and financial assets. The current scenario continues to be marked by de-anchored inflation expectations, high inflation projections, resilience on economic activity, and labor market pressures. Ensuring the convergence of inflation to the target in an environment with de-anchored expectations requires a significantly contractionary monetary policy for a very prolonged period.
    2. Copom decided to maintain the Selic rate at 15.00% p.a., and judges that this decision is consistent with the strategy for inflation convergence to a level around its target throughout the relevant horizon for monetary policy. Without compromising its fundamental objective of ensuring price stability, this decision also implies smoothing economic fluctuations and fostering full employment.
    3. The current scenario, marked by heightened uncertainty, requires a cautious stance in monetary policy. If the expected scenario materializes, the Committee foresees a continuation of the interruption of the rate hiking cycle to examine its yet-to-be-seen cumulative impacts, and then evaluate whether the current interest rate level, assuming it stable for a very prolonged period, will be enough to ensure the convergence of inflation to the target. The Committee emphasizes that it will remain vigilant, that future monetary policy steps can be adjusted and that it will not hesitate to resume the rate hiking cycle if appropriate.
    4. The following members of the Committee voted for this decision: Gabriel Muricca Galípolo (Governor), Ailton de Aquino Santos, Diogo Abry Guillen, Gilneu Francisco Astolfi Vivan, Izabela Moreira Correa, Nilton José Schneider David, Paulo Picchetti, Renato Dias de Brito Gomes, and Rodrigo Alves Teixeira.
Table 1

Inflation projections in the reference scenario
Year-over-year IPCA change (%)

Price Index202520262027 Q1
IPCA4.93.63.4
IPCA market prices5.13.53.3
IPCA administered prices4.44.03.9
Footnotes

1 Unless explicitly stated otherwise, this update considers changes since the June Copom meeting (271st meeting).

2 It corresponds to the rounded value of the average exchange rate observed over the ten working days ending on the last day of the week prior to the Copom meeting, according to the procedure adopted since the 258th meeting.

Meeting information
Date: July 29-30 2025
Place: BCB Headquarters’ meeting rooms on the 8th floor (7/29 and 7/30 on the morning) and 20th floor (7/30 on the afternoon) – Brasilia – DF – Brazil
Starting and ending times:
July 29: 10:07 AM – 11:37 AM; 2:17 PM – 5:51 PM
July 30: 10:10 AM – 11:13 AM; 2:37PM – 6:34 PM
In attendance:
Members of the Copom
Gabriel Muricca Galípolo – Governor
Ailton de Aquino Santos
Diogo Abry Guillen
Gilneu Francisco Astolfi Vivan
Izabela Moreira Correa
Nilton José Schneider David
Paulo Picchetti
Renato Dias de Brito Gomes
Rodrigo Alves Teixeira
Department Heads in charge of technical presentations (attending on July 29 and on the morning of July 30)
André de Oliveira AmanteOpen Market Operations Department
Euler Pereira Gonçalves de MelloResearch Department (also attending on the afternoon of 7/30)
Fábio Martins Trajano de ArrudaDepartment of Banking Operations and Payments System
Luís Guilherme Siciliano PontesInternational Reserves Department
Marcelo Antonio Thomaz de AragãoDepartment of International Affairs
Ricardo SabbadiniDepartment of Economics
Other participants (attending on July 29 and on the morning of July 30)
Alexandre de CarvalhoOffice of Economic Advisor
André Maurício Trindade da RochaHead of the Financial System Monitoring Department
Angelo Jose Mont Alverne DuarteHead of Office of the Deputy Governor for Licensing and Resolution (attending on the mornings of 7/29 and 7/30)
Arnaldo José Giongo GalvãoPress Office Advisor
Cristiano de Oliveira Lopes CozerGeneral Counsel
Edson Broxado de França TeixeiraHead of Office of the Deputy Governor for Supervision
Eduardo José Araújo LimaHead of Office of the Deputy Governor for Economic Policy
Fernando Alberto G. Sampaio C. RochaHead of the Department of Statistics
Isabela Ribeiro Damaso MaiaHead of the Sustainability and International Portfolio Investors Unit (attending on the mornings of 7/29 and 7/30)
Julio Cesar Costa PintoHead of Office of the Governor
Laura Soledad Cutruffo CompariniDeputy Head of the Department of Economics
Leonardo Martins NogueiraHead of Office of the Deputy Governor for Monetary Policy
Marcos Ribeiro de CastroDeputy Head of the Research Department
Mardilson Fernandes QueirozHead of the Financial System Regulation Department
Olavo Lins Romano PereiraDeputy Head of the Department of International Affairs
Renata Modesto BarretoDeputy Head of the Department of Banking Operations and Payments System
Ricardo da Costa MartinelliDeputy Head of the International Reserves Department
Ricardo Eyer HarrisHead of Office of the Deputy Governor for Regulation
Ricardo Franco MouraHead of the Prudential and Foreign Exchange Regulation Department
Rogerio Antonio LuccaExecutive Secretary
Simone Miranda BurelloAdvisor in the Office of the Deputy Governor for Monetary Policy

The members of Copom analyzed the recent performance and prospects for the Brazilian and international economies, under the monetary policy framework, whose objective is to comply with the inflation targets established by the National Monetary Council. This document represents Copom’s best effort to provide an English version of its policy meeting minutes. In case of inconsistency, the Portuguese version prevails.

Education and Famine Analysis

The great historian Élie Halévy’s (died in 1937) History of the English People in the Nineteenth Century, a multi-volume classic, gives us a sense of nineteenth century famine dynamics for the 1840s, which combines failed harvests and failed incomes and failed speculations together:

“It was a ‘dearth’ (i.e., scarcity)—a crisis belonging to the old order—the last ‘dearth,’ in fact, Europe had known up to the present day (i.e., before 1937). The unsatisfactory harvest of 1845 was followed by the disastrous autumn of 1846. The potato disease was worse than it had been the year before. The cereal harvest, moderately good in 1845, was a failure not only in the United Kingdom, but in France and throughout Western Europe. In 1845, Great Britain could still purchase corn even in Ireland, while the Irish poor were starving to death. Nothing of the kind was possible at the end of 1846.

“Britain could not obtain wheat from France or Germany. In short, it was no longer Ireland alone, but the whole of Western Europe that had to be saved from famine.

“The United Kingdom, France, and Germany must import Russian and American wheat, the only sources available to supply the deficit.

“In consequence the price of wheat rose from 50 shillings and 2d. on August 22 to 65 shillings and 7d. on November 18. The price of wheat rose once more. It exceeded 78 shillings in March.

“In Germany and France, where another ‘jacquerie’ seemed to have begun, hunger caused an outbreak of rioting. The same happened in Scotland and the south of England…but England suffered in common with Ireland and Continental Europe, and a drain on English gold began, to pay for the Russian and American wheat.

“Later there was a fall of 50% in four months. The corn factors (i.e., corn dealers) who for months had been gambling on a rise had no time to retrace their steps and were ruined at a single blow.” (“Commerical Failures in 1847,” Eclectic Review, December 1847)

(Élie Halévy, “Victorian Years (1841-1895),” Halévy’s History of the English People in the Nineteenth Century, Volume 4, pages 191-193, Ernest Benn Ltd., 1970)

Note that in British usage, “corn” refers to all feed grains (primarily wheat), not corn (in the American sense) or maize. For example, see the Corn Laws.

We sense from Halévy’s description of the “food insecurity” of the nineteenth century in Europe, why the Revolutions of 1848 were to a large extent severe food riots and how food poverty and speculation interacted with risk and uncertainty prevailing.

This should be read and pondered in connection with Prof. Amartya Sen’s classic from 1981, Poverty and Famines, which highlights the famine of income and buying power, as opposed to famines based on outright crop failures. Pearl Buck’s classic novel, The Good Earth (1931), fits this topic set, as it analyzes in human terms the pattern of Chinese famines. It is interesting to note, parenthetically, that the movie of The Good Earth could not feature Chinese actors in lead roles due to racial craziness at the time. Stepping back, we see a world of food insecurity aggravated by the spectre of racism further poisoning social relations worldwide.

Halévy states: “It was a ‘dearth’ (i.e., scarcity)—a crisis belonging to the old order—the last ‘dearth,’ in fact, Europe had known up to the present day…”.

It would be instructive to ponder whether this really was “a crisis belonging to the old order” given the catastrophes and food crises that could come with climate change from 2019 on out. Will we have “global ‘dearths’”?