Skip to content
Meta Intelligence

Meta Intelligence

Towards a Composite Understanding of Education

  • About
  • Contact

Tag: bank account

Japan-Watching: Yen Repatriation: The Tide Is Turning

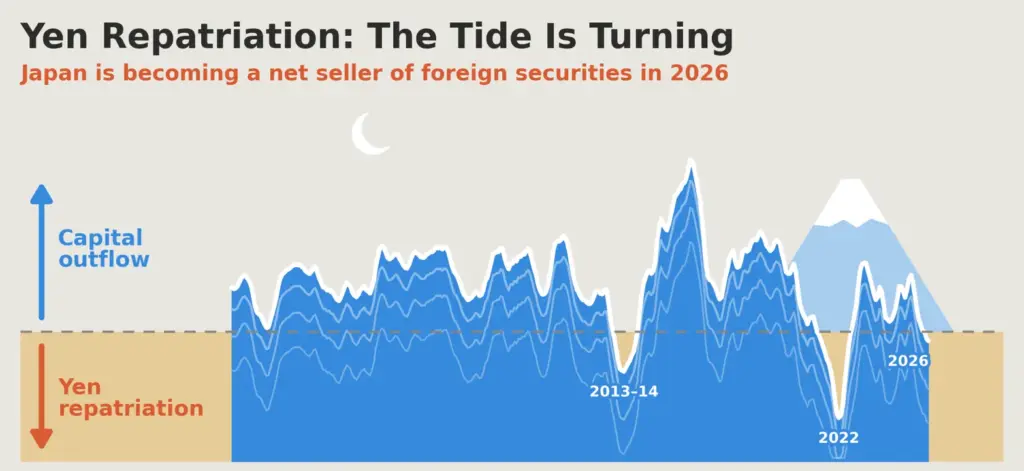
From 2014 to 2025, Japan bought foreign securities worth about 2% of GDP a year. In 2026 the tide is turning. Banks are selling foreign bonds and capital flow has turned to a small net inflow.

[by OKUBO Takuji]
Key takeaways

  • Japan has been an exporter of capital since the 1980s, purchasing 2–3% of GDP worth of foreign assets every year, interrupted by episodes of yen repatriation from time to time. 2026–27 may be turning into such an episode.
  • Banks are selling foreign bonds and buying JGBs. Now that yen yields are higher, their JGB purchases leave less room for duration risk in foreign bonds.
  • Households keep buying foreign stocks, but pension funds are selling against them, offsetting the net purchase of foreign equities.
  • Pension funds are likely to put more money into yen. On my replication of GPIF’s allocation rule, its domestic-bond weight should be much higher than today’s 25%, and foreign bonds are the likely asset class to give way.
  • The weekly survey to 10 October shows foreign-bond selling continuing. In my view, yen repatriation in 2026–27 is a question of how large, not whether.

Japan’s outward flow has turned into a net sale

Japan has been a large provider of capital to the rest of the world since the 1980s. The latest wave began in 2014. From 2014 to 2025, residents bought ¥13.6trn a year on average, about 2.3% of GDP.

Chart 1 shows the flow as a rolling twelve-month sum. The one large exception was 2022, when bond yields rose sharply abroad and Japanese investors sold their holdings, realizing losses on their foreign bonds. They went right back into purchasing foreign securities in 2023 when yield curves in major foreign bond markets stabilized, while domestic bond yields remained close to zero. How Japanese investors behave now that yen yields are respectable is the big question.
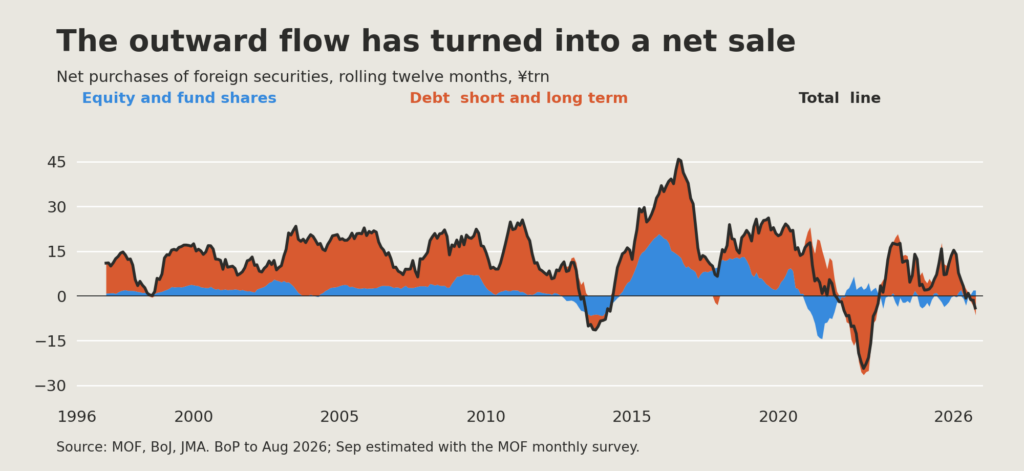
Chart 1: Rolling twelve-month flows, stacked separately above and below zero. Short- and long-term debt combined; black line is the net total. BoP through August 2026; September estimated from the MOF monthly survey. Source: MOF, BoJ, JMA.

The flow is turning again in 2026. By August 2026 the rolling total was a small net sale of ¥1.5trn (see chart 1 above). September’s balance of payments statistics are not out yet, but based on the International Transactions in Securities Survey for September, I estimate that the rolling total would be a net sale of ¥4.5trn. September itself was a small net sale; most of the drop comes from September 2025’s ¥2.8trn of buying leaving the window.

Foreign bonds and foreign equity have different investors

In the rest of the report, I discuss recent developments in Japan’s capital flows. I have organized the discussion by asset class because the investor bases differ. Banks, the FX reserves managed by the government, pensions and insurers hold foreign bonds. In foreign equity, households are now the key investors, alongside pensions and other traditional investors. GPIF and other pensions sit in both markets, so I discuss them in a part of their own.

Part 1 covers foreign bonds, where repatriation would show first. Part 2 covers foreign equity, where households keep buying while pensions sell against them. In Part 3, GPIF is the key mover in both markets. In Part 4, I discuss the most recent developments, using the weekly survey, which runs to 10 October, and what to watch. The focus of this report is return-seeking portfolio investment, so analysis of the Japanese government’s FX reserves is covered in Japan Cashes In Its National Carry Trade (31 July) and Japan Inc.’s real investment is covered in Japan Inc. Now Sells No Yen to Invest Abroad (10 October).

Japan holds 147% of GDP worth of securities abroad

Before moving to discuss recent developments, let me give you a brief historical perspective on Japan’s outward investment. Japan has been a creditor nation since the 1980s. In 1985–89, Japan invested 3–5% of GDP, as Japan was awash with bubble money. Since then, Japan has typically invested 2–3% of GDP a year in foreign securities, with some episodes of repatriation from time to time. At end-2025, Japan held ¥982trn in foreign portfolio securities and official reserve assets: ¥401trn of equity and fund shares, ¥368trn of portfolio debt and ¥214trn of reserves (chart 2). Reserves are mostly US Treasuries plus some deposits and gold. The ¥401trn in equity and fund shares actually includes some bond funds that are categorized inside “equity and fund shares” in official statistics, so we will make some adjustments when we discuss investor behavior by asset class in later parts.
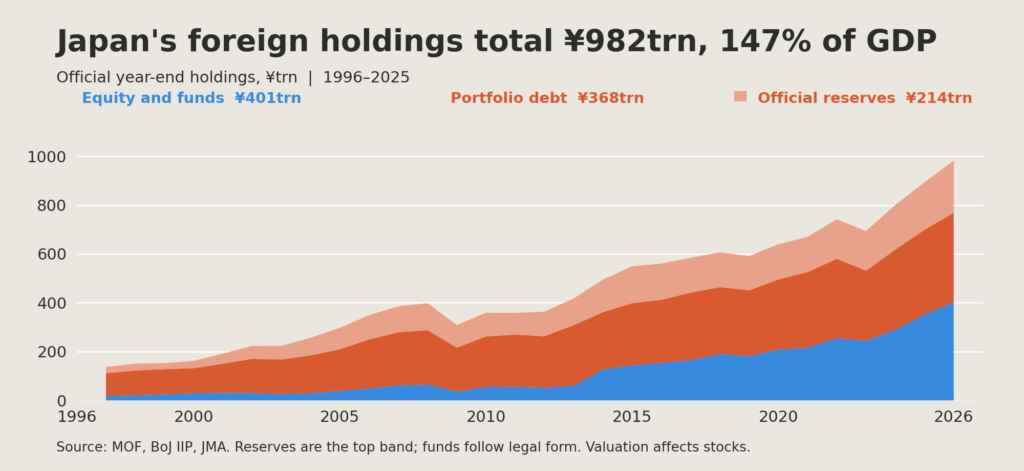
Chart 2: Official year-end holdings, 1996–2025. Equity is the bottom band, portfolio debt the middle band and official reserves the top band. Debt and reserves use related colors. Current BPM6-rearranged IIP; funds classified by legal form. Source: MOF, BoJ, JMA.

Part 1. Selling foreign bonds in 2026

Banks, reserves, pensions and insurers own the bonds

Of the ¥214trn the Japanese government holds as reserves, ¥157trn is debt securities and the rest is gold, deposits and other claims. Add this ¥157trn to the ¥368trn of private debt securities and an estimated ¥47trn of bond funds that are categorized as “equity and fund shares” in the balance of payments statistics, and you get ¥573trn of debt securities held by Japan at end-2025. By my estimate, banks held 32% of it, official FX reserves 27%, public and corporate pensions 19% and insurers 14% (chart 3).
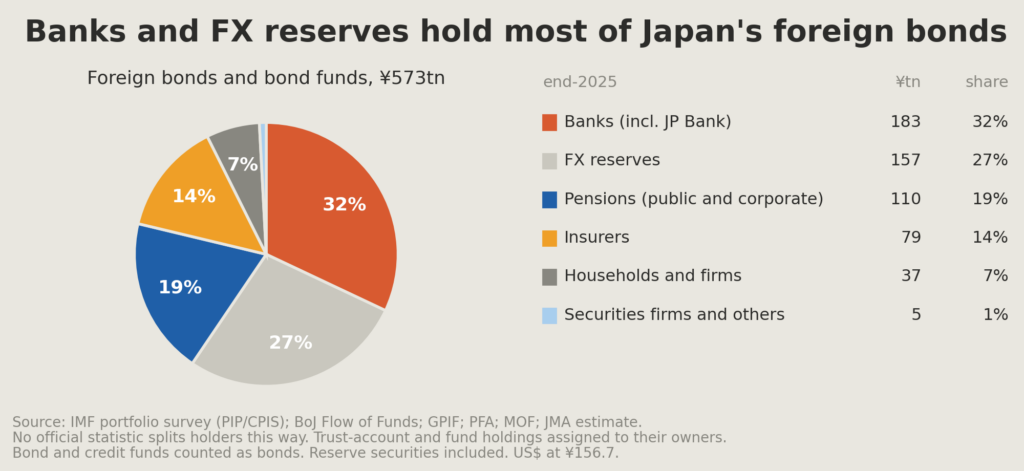
Chart 3: End-2025, JMA estimates. Bonds and bond funds, reserve securities included; trust-account and fund holdings are assigned to their owners. Source: IMF, GPIF, BoJ, MOF, PFA, JMA.

Banks are selling while pensions keep buying

Chart 4 shows movements in foreign long-term bond flows by investors since 2014. We see pension funds as the consistent buyer, with an elevated purchase in 2020 when GPIF raised its foreign-bond asset allocation target from 15% to 25% (see the Japanese Macro Advisors GPIF report for details). On the other hand, life insurers have been consistent net sellers in recent years. Banks seem to be opportunistic swing players. This year’s foreign-bond sale so far is a bank story.
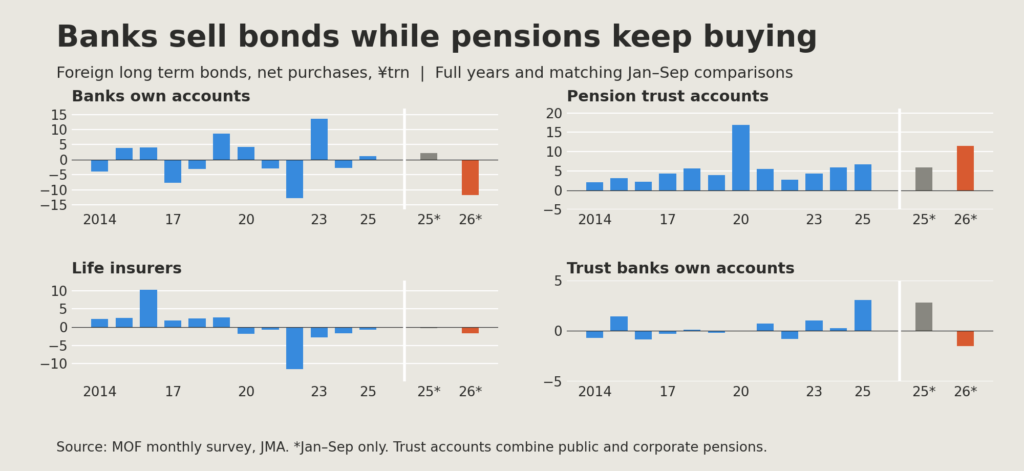
Chart 4: Foreign long-term bonds by investor. Full calendar years 2014–2025; the two separate bars at right compare January–September 2025 and 2026. MOF monthly survey throughout. Source: MOF, JMA.

The bank balance sheets show who is selling. City banks are the dominant players: their foreign securities reached about ¥53trn in late 2024, moved sideways with some swings in 2025, and then fell in 2026. Regional banks’ foreign holdings are small and little changed (chart 5).
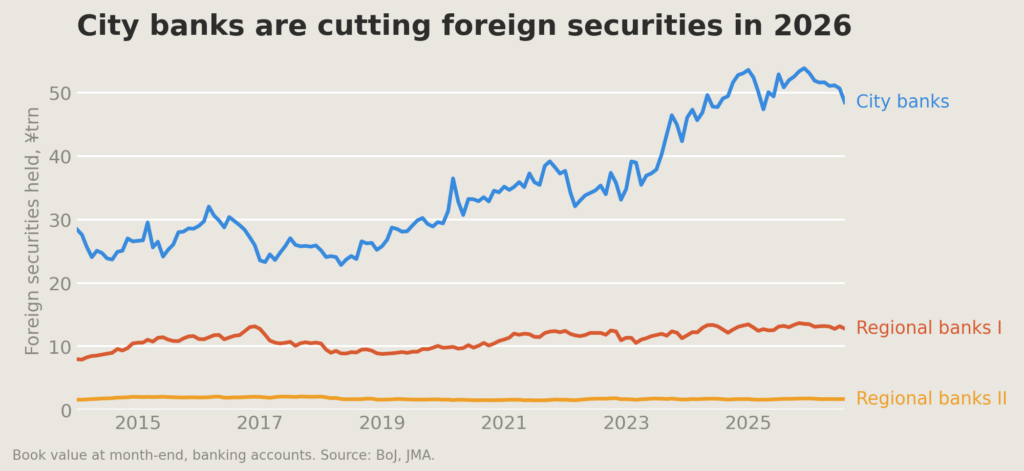
Chart 5: Foreign securities held by city banks and regional banks, month-end book value, banking accounts, through August 2026. Source: BoJ, JMA.

2026 is different from 2022: Yen rates are at 30-year highs

City banks went through a similar repatriation episode in 2022 (see chart 5), but went right back to buying foreign bonds in 2023 as soon as the overseas yield curve stabilized. 2026 offers a different environment. Both city banks and regional banks are buying JGBs, although in different parts of the yield curve. City banks are stepping up their purchases of 10-year bonds on a rolling 12-month basis (chart 6). They were selling the 2–5-year and super-long sectors in early 2026, but their rolling 12-month figures have just come back to neutral. Regional and co-operative institutions are showing strong appetite for the 2–5-year and 10-year sectors. Banks buying at home does not necessarily mean selling bonds abroad, but their JGB purchases do leave less room for duration risk in foreign bonds.
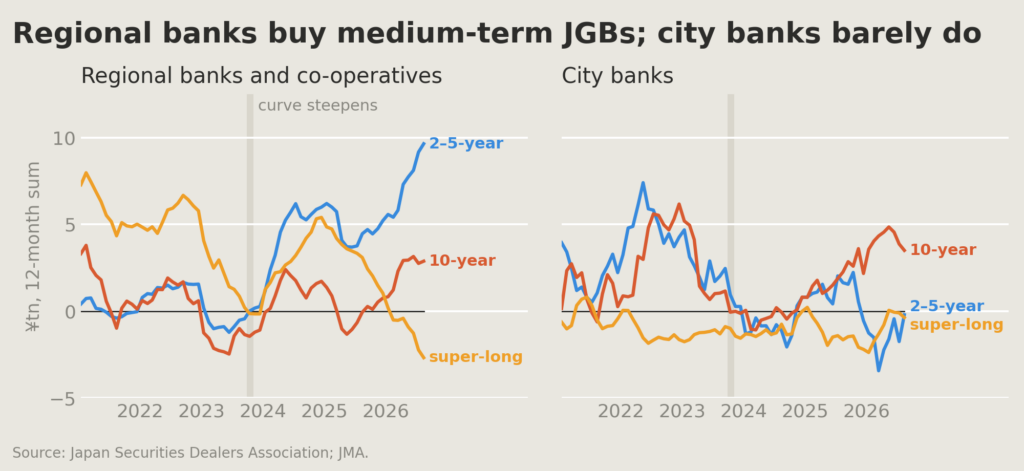
Chart 6: Net secondary-market OTC purchases, twelve months through August. Regional/co-operative group includes regional banks, shinkin and agricultural institutions; auctions and bills excluded. Source: JSDA, JMA.

Part 2. Pension funds are selling foreign equity, offsetting households’ buying

Pension funds and households are the top two owners of foreign equity (chart 7). As you can see in chart 8, households have been showing a strong appetite for foreign equity investment trusts since 2024, and they are still buying. NISA accounts, low-cost funds and retirement savings are behind it, and I expect it to continue. Mrs Watanabe No More (21 September) tells that story in full.
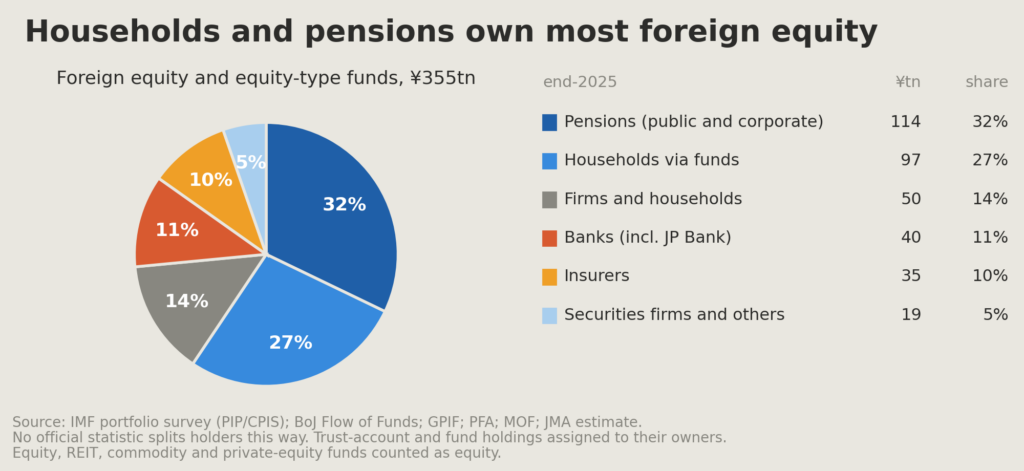
Chart 7: End-2025, JMA estimates. Equity and equity-type funds; trust-account and fund holdings are assigned to their owners. Source: IMF, GPIF, BoJ, MOF, PFA, JMA.
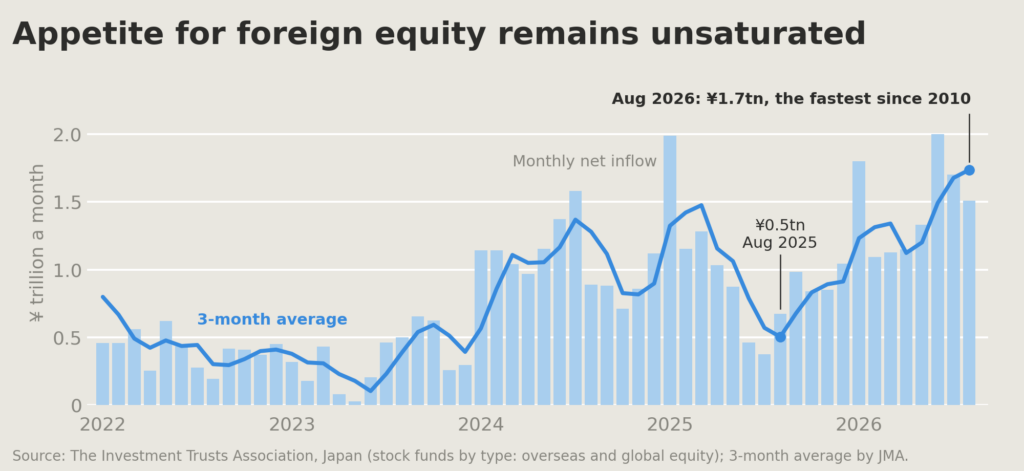
Chart 8: Monthly net purchase of overseas- and global-equity investment funds. Source: ITA, JMA.

The strong appetite of households for foreign equity has been offset by selling by pension funds though. Over the twelve months to August, households bought ¥11.9trn of foreign equity through investment trusts, but pension funds through their trust accounts sold ¥11.5trn (chart 9).
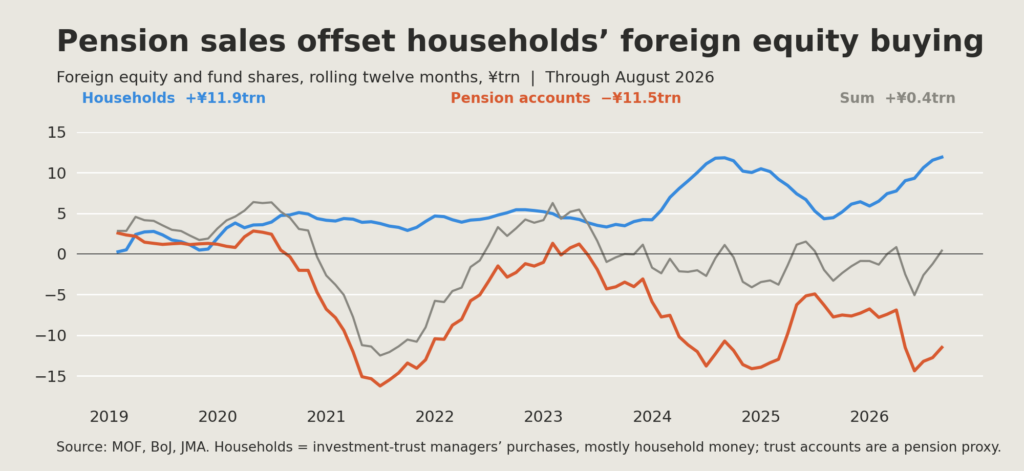
Chart 9: BoP rolling twelve-month flows through August. Households are investment-trust managers’ purchases. Trust accounts are a pension proxy. Source: MOF, BoJ, JMA.

Why do pensions sell what households buy? Pension funds typically manage their assets to target weights. When foreign equities outperform, they sell some and buy other assets to restore the balance.

Part 3. Pension funds to put more money in yen

GPIF likely to raise its asset allocation into yen bonds

As you can see in the two pie charts (charts 3 and 7), GPIF and other pension funds are key players in Japan’s investments in foreign bonds and equity. GPIF, with ¥320trn of assets under management, is the big whale, and changes in its asset allocation have played a significant role in defining Japan’s cross-border capital flows in recent years.

For details on my views on GPIF, I refer readers to the “GPIF the Whale” report. Here is the gist. GPIF reduced its domestic-bond allocation target from 60% to 35% in 2014 and to 25% in 2020, partly to protect the fund from a JGB crash it saw coming (chart 10). The crash has already happened, in slow motion over the last two years. When GPIF last reviewed the asset allocation in early 2025, maintaining the target unchanged at 25% made sense. At the time, JGB yields had more room to “normalize”, and they did. Please see my report The Long Climb in JGB Yields Is Nearly Over (20 July) for why I think the normalization is largely over.

On my simplified replication of GPIF’s allocation rule, a zero expected real return on JGBs points to a domestic-bond weight of about 50%, against 25% today. A move to 50% means about ¥80trn of assets shifting toward yen bonds, and foreign bonds are the likely asset class to give way. For more details, please see Yen Repatriation Starts with the Whale (10 September). It is a tricky shift, as GPIF is a classic whale in financial jargon, and there is a legitimate concern that other investors could front-run it. But GPIF cannot ignore the asset-allocation arithmetic. GPIF’s July–September results, due in early November, are the first place a shift could show, but even if it doesn’t, it is just a matter of time in my view, as GPIF would be doing Japanese pensioners a disservice if it did not change the allocation.
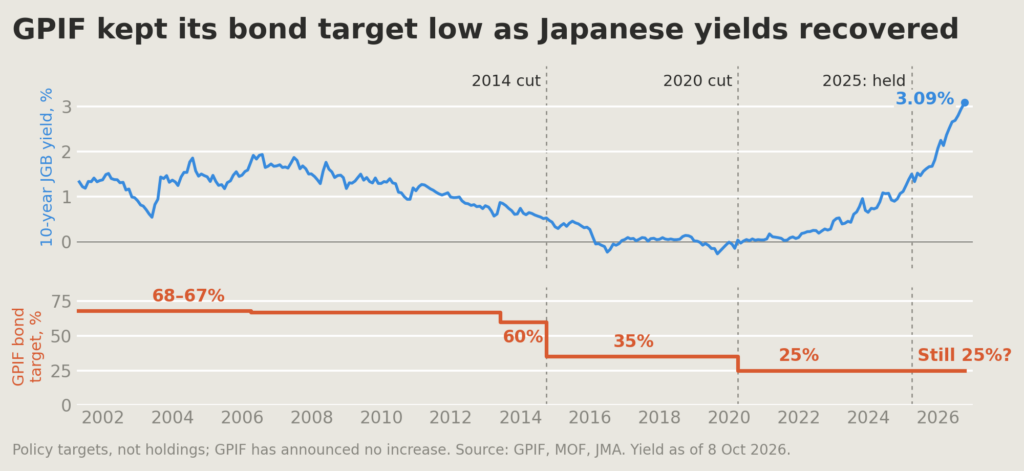
Chart 10: GPIF policy targets for domestic bonds and 10-year JGB yield, through 8 October 2026. Source: GPIF, MOF, JMA.

Part 4. Recent development and what to watch

Weekly data shows bond selling continuing into October

The balance of payments is the key statistic for monitoring cross-border capital flows, but as of mid-October it runs only to August. The Ministry of Finance’s weekly survey of large investors is a good leading indicator and runs to 10 October. In the four weeks to 10 October, Japanese investors sold a net ¥3.3trn of foreign long-term bonds. Chart 11 shows the 52-week and 13-week averages.
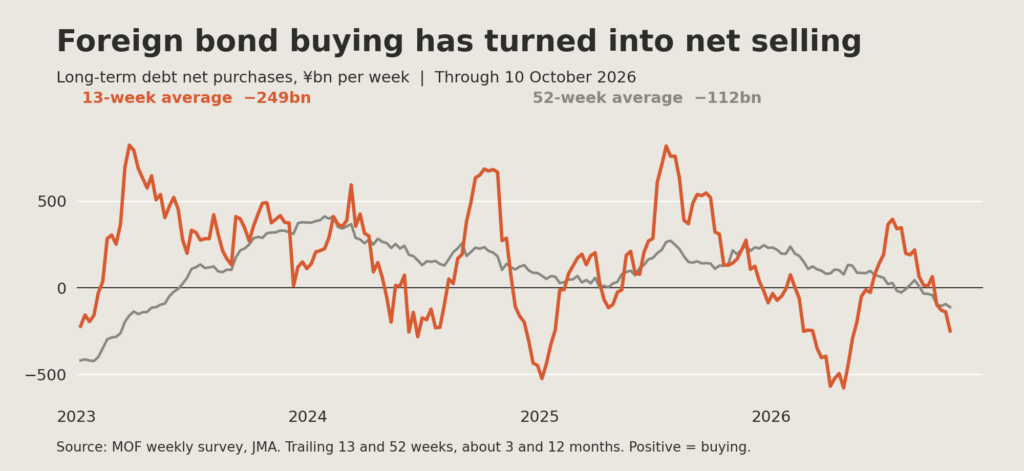
Chart 11: MOF weekly survey of designated major investors. 13- and 52-week trailing averages, approximately three and twelve months, through 10 October. Both lines show average net purchases per week, not cumulative totals. Source: MOF, JMA.

Equity flows have no sustained direction

The same weekly survey includes equity flows. They have some ups and downs, but the 52-week average is hugging the zero line, and I do not see any particular trend upward or downward (chart 12). The equity data add no repatriation signal to the bond evidence.
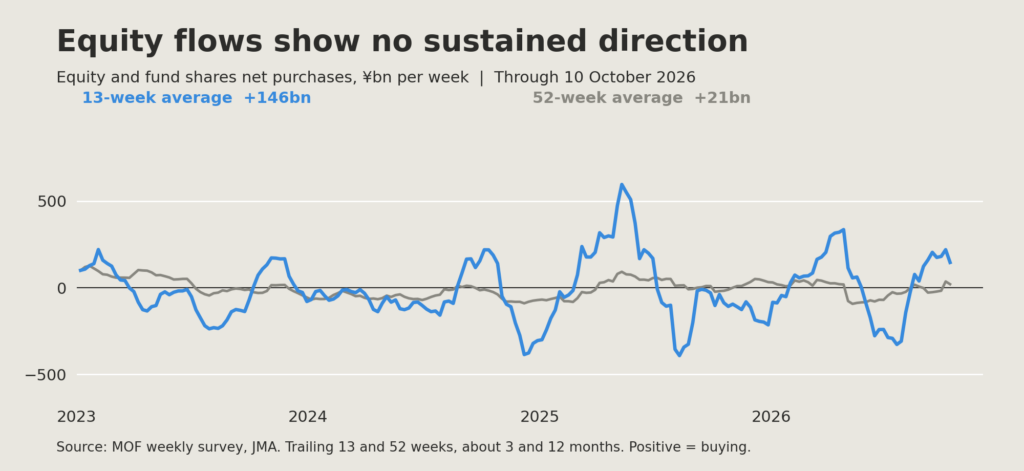
Chart 12: Same weekly survey, smoothing windows, dates and vertical scale as Chart 11; foreign equity and fund shares. The 13-week line shows recent swings; the 52-week line shows the smaller underlying net flow. Source: MOF, JMA.

What to watch

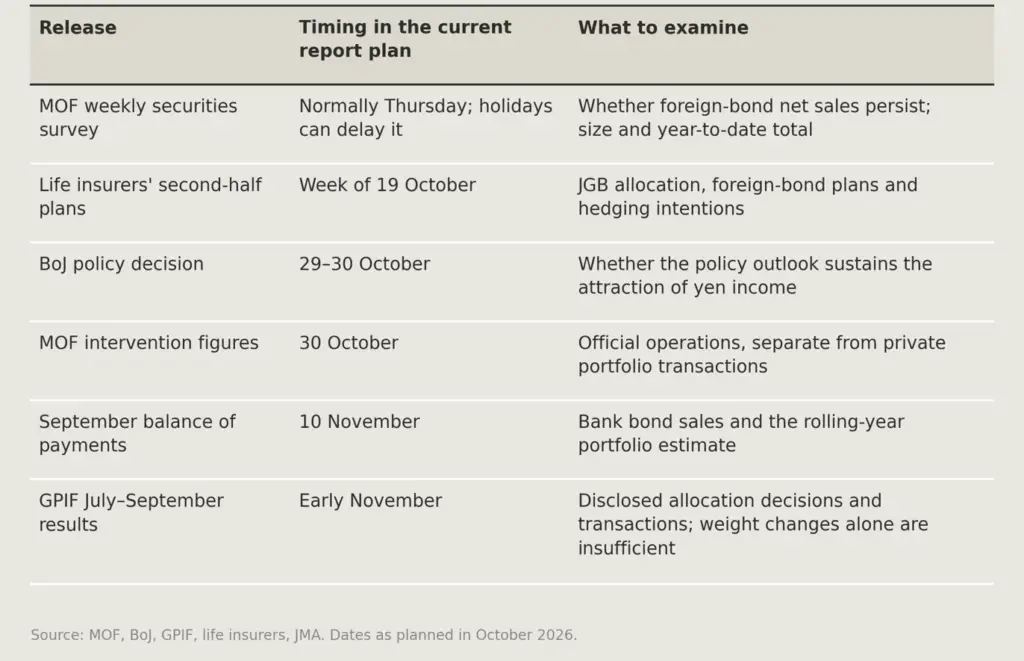
The weekly survey is the first test of whether bond sales persist. The September balance of payments, due in early November, will test the estimate in the opening. The other releases are in the table below.
Conclusion

The capital-flow tide is turning

As this report showed, Japan has been a broadly consistent provider of capital to the rest of the world, and Japan will continue to play that role for many years to come. However, the tide turns from time to time, and 2026 seems to be such a year. Net portfolio flow has narrowed from a sizable outflow in 2024–25 to a small net sale in the latest months, even while households continued to show strong appetite for foreign equity. Banks seem to be increasing their appetite for yen bonds, with good reason. JGB yields have risen to a 30-year high. Some may claim the rise has to do with higher fiscal premia, but my yield-curve analysis in Japan’s Fiscal Vigilantes Are Misreading the Curve (16 July) shows otherwise.

In my view, this shift weakens one of the forces behind the weak yen. Higher yen yields give investors a reason to keep shifting toward domestic bonds. I see a moderate chance that the turn in foreign bonds develops into a larger net repatriation, with GPIF’s asset allocation decision as a potential key mover. If global financial markets were to suffer a setback, whether in the euro bond market or the US stock market, it would further strengthen the case for yen repatriation. In my view, Japan’s capital flows are likely to show yen repatriation in 2026–27; the question is how large, rather than whether it will happen.

Author David ClarkPosted on October 20, 2026October 25, 2026Categories Economics, Essays, World WatchingTags 1980s, 1996, 2014, 2022, 2024, 2025, 2026, 2027, asset, balance of payments, balance sheet, bank, bank account, Bank of Japan [日本銀行], bond (finance), bond fund, book value, capital (economics), custodial account, debt, deposit account, duration (finance), economic bubble, equity (finance), finance, financial market, Government Pension Investment Fund, Gross Domestic Product, household, International Monetary Fund, investment, investment fund, investment trust, Japan [日本], Japanese yen (¥), life insurance, Ministry of Finance (Japan) [財務省], money, national debt of Japan, Nippon individual savings account [少額投資非課税制度], over-the-counter (finance), pension, pension fund, pensioner, portfolio investment, regional bank, secondary market, security (finance), shinkin bank [信用金庫], statistics, stock, stock market, United States, United States Treasury security, yield curve

Stablecoins and Financial Stability

The United States has introduced a new stablecoin regulatory framework, but concerns over the cryptocurrency’s place in the global economy remain.

[from the Federal Reserve Bank of Richmond’s Econ Focus, Fourth Quarter 2025, by Matthew Wells]

Signed into law in July 2025, the Guiding and Establishing National Innovation for U.S. Stablecoins (GENIUS) Act was a huge step forward for the cryptocurrency industry. The bipartisan legislation marked the federal government’s first effort at creating a regulatory framework for cryptocurrencies and signaled that crypto had finally achieved a status and size worthy of the government’s attention.

Stablecoins are digital assets used primarily as currency to buy and sell other cryptocurrencies, such as bitcoin, on blockchains, which are decentralized electronic ledgers. Traditionally, they are viewed as “private money” that has been pegged one-to-one to a state-issued currency, typically the U.S. dollar, although others have been pegged to the euro, the Japanese yen, and the Swiss franc.

While few people use stablecoins to pay for conventional goods and services, the technology is expanding rapidly. The SWIFT payment system is transitioning to the blockchain, allowing banks to settle transactions with stablecoins, and large companies such as PayPal have developed their own stablecoins. Walmart, Amazon, and several large financial institutions are also exploring their potential.

The GENIUS Act gives banking regulators, including the Federal Reserve, oversight authority over the entities that issue stablecoins. However, the law leaves it to those regulators to decide what rules to create and how to implement them. Further, increases in stablecoin demand may impact other sectors of the economy, such as the Treasury market and the global demand for dollars. All these carry potential implications for the stability of stablecoins, as well as the Fed’s efforts to maintain a safe and secure financial system.

Stablecoin Fundamentals

Customers wanting stablecoins pay money through their bank accounts, credit or debit cards, or other payment systems to an entity issuing them. With those stablecoins in hand, users can make purchases or investments wherever they are accepted. When users want to “cash in,” they take whatever stablecoins they have, which could have increased or decreased in number, back to an issuer, where they collect dollars back at a one-to-one rate.

Two of the most popular stablecoins in the crypto space are Tether and USD Coin. Unlike dollars, which are fiat currency (that is, their value is derived from the government’s declaration of their value), they and other stablecoins are backed or collateralized by a range of assets (or reserves), especially cash or U.S. Treasurys. In theory, these reserves can be easily liquidated to pay any customer seeking to redeem stablecoins for dollars.

The GENIUS Act addresses these dollar-pegged and reserve–collateralized stablecoins specifically, but there are other types of stablecoins that fall outside of the act’s definition. Crypto–collateralized stablecoins, for example, are still pegged to a currency but are backed by other digital assets such as Ethereum, making them less stable because of the greater volatility of their reserves. Another example includes algorithmic stablecoins, which attempt to maintain a consistent dollar-pegged value through automated adjustments in value relative to other digital currencies.

Stablecoins are used primarily as an immediate and secure medium of exchange for blockchain-based transactions, particularly the buying and selling of other cryptocurrencies. Unlike traditional payment systems, which can take days to fully settle transactions, stablecoin transactions are settled at any time of day on the blockchain almost instantaneously through “smart contracts,” where the terms of the transaction are written into the code.

Beyond their speed on the blockchain, another benefit of stablecoins is their global reach. They can be used anywhere in the world, including areas where dollars are difficult to acquire. Coupled with the ease with which a user can move stablecoins in and out of crypto markets, their use can reduce the costs and frictions associated with remittances or other international transactions. For individuals in developing countries with persistently high inflation, stablecoins may also be a way to save money that is insulated from swings in the domestic currency.

In a February 2025 speech [archived PDF], Fed Gov. Christopher Waller similarly noted that for some users, stablecoins might also serve as a store of value. Relative to the other, more volatile crypto assets, stablecoins are low risk, “which allows traders to move out of risky positions into safe ones where the safe asset price is known and stable,” he argued. Most stablecoin transactions — more than 80 percent — occur outside of the United States.

To date, these benefits of speed and availability have mostly been enjoyed by individuals active in the cryptocurrency marketplace rather than the average consumer. According to the Fed’s most recent Diary of Consumer Payment Choice [archived PDF], only 3 percent of respondents said they used cryptocurrency as a form of payment in the last month. However, the annual transaction value of stablecoins exceeded $27 trillion in 2024, surpassing that of Visa and Mastercard combined. Further, stablecoins’ current market capitalization is about $267 billion, and Citigroup projects it will grow to between $1.9 trillion and $4 trillion by 2030. Treasury Secretary Scott Bessent made a similar claim in November, suggesting it could reach $3 trillion in the coming years. Motivated by that growth, and its potential implications for the economy, Congress passed the GENIUS Act.

A New Regulatory Framework

The GENIUS Act grants banks, nonbanks, and even nonfinancial institutions with approval from state or federal regulators the ability to issue stablecoins to the public. Under the act, the Office of the Comptroller of the Currency regulates federally qualified issuers with over $10 billion in stablecoins in circulation. If the issuer is a subsidiary of an insured depository institution, such as a bank, it is regulated by the appropriate federal banking agency. All issuers with less than $10 billion in circulation would be regulated at the state level. Regulators would be responsible for conducting annual audit and ensuring compliance with existing anti-money laundering and sanctions requirements.

Crucially, issuers would be required to hold at least one dollar’s worth of reserves for every stablecoin issued. Those reserves mostly come in the form of cash, insured and uninsured deposits, short-term Treasurys, repo agreements, and central bank reserve deposits. However, these issuers would be exempt from the regulatory capital requirements that currently apply to banks, and this holds true even if the issuers are banks engaged in regular banking activities.

Stablecoins are not defined as securities or commodities under the legislation, meaning they are not federally insured and do not have the same protections as traditional bank deposits. In other words, there is no government-backed guarantee a user would be able to get cash back when they want to trade back in their stablecoins. Issuers, as of now, also do not have access to the Fed’s lending facilities.

Proponents of stablecoins argue that government insurance and access to the Fed are not necessary because the assets designated as collateral by the GENIUS Act are highly liquid, and issuers are required to hold as many dollars in reserve as they have stablecoins in circulation. While this would seemingly guarantee stablecoin holders could redeem their coins for cash whenever they choose without any difficulty, not all policymakers or observers agree it would be that easy.

In an October 2025 speech [archived PDF], Fed Gov. Michael Barr argued that “Because stablecoins are not backed by deposit insurance and stablecoin issuers do not have access to central bank liquidity, the quality and liquidity of their reserve assets is critical to their long-run viability.”

He identified several points of vulnerability in those assets. In addition to the potential for some consumers to mistakenly assume all stablecoins — not just those covered by the GENIUS Act — carry the same level of stability, he pointed out that other dollar-pegged assets have not always been able to maintain that one-to-one value. Money market mutual funds, which are listed as one class of asset that can be used as collateral, “broke the buck” in 2008 following Lehman Brothers’ bankruptcy and experienced strains again in March 2020 at the outbreak of the COVID-19 pandemic.

Uninsured deposits, another acceptable reserve asset, were also a risk factor that precipitated the March 2023 banking stress associated with the failure of Silicon Valley Bank and others. The legislation also allows for any medium of exchange authorized by a foreign government to be used as collateral via repo agreements, which until recently in the case of El Salvador included the highly volatile bitcoin.

In an October 2025 speech, Fed Gov. Michael Barr argued that “Because stablecoins are not backed by deposit insurance and stablecoin issuers do not have access to central bank liquidity, the quality and liquidity of their reserve assets is critical to their long-run viability.”

The GENIUS Act prohibits issuers from paying out interest to individuals holding their stablecoins. If stablecoins paid interest, they would have to be treated — and regulated — like securities rather than simply forms of payment. The legislation does, however, allow stablecoin exchanges, known as Virtual Asset Service Providers, to offer “rewards” to users who choose to buy and sell cryptocurrencies or conduct other transactions on their platforms. This creates a potential loophole, as these exchanges, if authorized by regulators, can also be part of the same entity issuing a stablecoin. The platform/issuer can then use the dollars traded for the stablecoins to purchase other assets, likely Treasurys to back the stablecoins, and then pay out rewards to customers with the proceeds from those investments.

Barr noted this area of concern, suggesting issuers “have a high incentive to maximize the return on their reserve assets by extending the risk spectrum as far out as possible. Stretching the boundaries of permissible reserve assets can increase profits in good times but risks a crack in confidence during inevitable bouts of market stress.” To hedge against this possibility, stablecoin issuers are required to publish monthly reports on the composition of their reserve assets, a move intended to give stablecoin holders increased confidence in the issuer’s liquidity.

Parallels to the Free Banking Era

Barr’s argument implies that stablecoins are only as stable as the assets backing them. The United States first established a banking system with a national currency backed by Treasury bonds during the Civil War. Prior to that, in the free banking era from 1836 to 1863, states conducted banking supervision and regulation, and banks issued their own currencies. (See “When Banking Was ‘Free,’” [archived PDF] Econ Focus, First Quarter 2018.) Those paper notes had to be collateralized through state and federal government bonds, and capital and reserve requirements were inconsistent across states.

This meant the country’s economy operated with competing, private currencies. It was difficult for currencies in one part of the country to be redeemed in other parts, and it was often done at a discount; for example, the farther away from the bank issuing the note, the steeper the redemption discount. It wasn’t unusual for citizens to question the collateral backing the various banks’ notes, leading to regular bank runs and failures.

One can draw parallels between the free banking period and today’s stablecoin landscape. First, as of early June, there were 233 stablecoins available on the crypto market. Numerous digital service platforms market themselves as spaces where private companies can create, manage, and distribute their own stablecoins. Bank of America, JPMorgan Chase, Citigroup, and Wells Fargo are considering the idea of a jointly issued stablecoin, as well as their own individual ones.

As was the problem with free banking, some economists question whether consumers will always maintain confidence that they can redeem stablecoins for cash on demand at the promised one-to-one rate. The large banks may be able to issue coins that no one will doubt, but the stablecoin marketplace includes platforms and issuers that are not banks at all, as well as international operators outside the jurisdiction of U.S. financial regulators.

“Smaller companies planning to issue stablecoins under the GENIUS Act to be regulated by one of the states may face market resistance,” says Michael Bordo, an economist at Rutgers University. “Unless there is perfect information about the backing and complete confidence in it, holders may want to discount the stablecoins or avoid them completely, as was the case under free banking in the United States.”

Yale University economist Gary Gorton expresses similar concerns, particularly due to the difficulty in regulating a transnational market. “Let’s suppose that one of the exchanges out there collapses because of fraud. Now everybody’s a little suspicious of these exchanges, and many aren’t even based in the United States,” he says. “That’s the kind of thing that would cause everybody to run.”

Should one stablecoin issuer experience a run where customers doubt its ability to pay back dollars on demand, it is possible others would too, especially if they are all backed by similar assets. This could lead to a crisis that extends beyond the stablecoin space and impacts the wider financial system. In a recent paper co-authored with Jeffery Zhang of the University of Michigan Law School, Gorton argued this outcome is consistent with the nature of short-term debt. Stablecoins are a form of that debt, and because of the laws of supply and demand, their values should fluctuate as the values of the assets backing them fluctuate.

“If one issuer gets in trouble and its stablecoin holders all run on it and ask for cash, it can sell Treasurys and give them the cash,” says Gorton. “But in a systemic event, 500 issuers are under siege and they all sell their Treasurys, and the price of Treasurys goes way down.”

Gorton and Zhang argued such a failure is in keeping with the pattern of systemic crises over the past 200 years, and the solution is not to outlaw stablecoins but to provide a safer alternative where “no one should have an incentive to produce information about the backing for the money (i.e., the banks’ assets); and everyone should know that no one has an incentive to produce that information.” In other words, a stablecoin that is truly stable is one that is accepted at par, anywhere and at any time, no questions asked. Gorton says that a digital currency issued by a central bank would meet these criteria.

Should one stablecoin issuer experience a run where customers doubt its ability to pay back dollars on demand, it is possible others would too, especially if they are all backed by similar assets. This could lead to a crisis that extends beyond the stablecoin space and impacts the wider financial system.

The Road Ahead

Skeptics and supporters alike agree that stablecoin adoption is likely to increase in the coming years. An important question, however, is whether it will attract new users looking for a new form of payment. Certainly, stablecoins offer the advantage of instant transactions, and merchants might have incentive to adopt them to replace credit cards, which currently assess transaction fees between 1.5 percent and 3.5 percent for each purchase. (See “Should Credit Card Fees Be Regulated?” [archived PDF]) However, it may be possible to achieve the benefits of quicker settlements and lower fees with existing payment rails, such as FedNow, raising the possibility that internal U.S. demand may be limited.

In a recent speech [archived PDF], Fed Gov. Stephen Miran acknowledged that stablecoins’ future growth may lie outside the United States. “Because GENIUS Act payment stablecoins do not offer yield and are not backed by federal deposit insurance, I see little prospect of funds broadly fleeing the domestic banking system,” he said. “The real opportunity in stablecoins is to satiate untapped foreign appetite for dollar assets from savers in jurisdictions where dollar access is limited.”

This increased global demand for stablecoins could precipitate increased demand for U.S. Treasurys. Stefan Jacewitz, an economist at the Kansas City Fed, suggested in a recent report that there is still a way to go for any increased adoption of stablecoins to make a meaningful difference in the economy. Circle, the largest U.S.-based stablecoin issuer, currently holds 43 percent of its assets in Treasurys. If all other issuers held that same percentage in Treasurys, it would amount to about $125 billion, which is less than 2 percent of the $6 trillion in outstanding Treasurys.

However, if the projections of increased adoption materialize, Jacewitz acknowledged the possibility that “it could lead to a substantial redistribution of funds” and potentially increase demand for Treasurys such that the increase in stablecoin issuers’ Treasury holdings could outpace the decrease in bank holdings. A 1 percent decrease in bank Treasury holdings — and an accompanying 1 percent decrease in bank lending — translates to a $325 billion reduction in loans into the economy, Jacewitz estimated.

The American Bankers Association and other banking organizations point to this potential for deposits to leave the banking system in calling for regulators to limit the ability of stablecoin issuers and platforms to pay out rewards. The crypto industry disagrees, arguing that banks fear competition, and banks could incentivize their depositors to stay by raising their deposit rate, something they did when they first competed with money market mutual funds.

While there is widespread agreement on the potential for stablecoins to serve an important function for cross-border transactions, concerns about their soundness and stability remain, and they are not just theoretical. Circle held $3.3 billion of its approximately $40 billion in reserves at Silicon Valley Bank when it collapsed in 2023, and its inability to access those reserves triggered a fall in the value of its USD Coin from the one-to-one ratio to below 87 cents on the dollar. In that case, the federal government stepped in and made whole all of Silicon Valley Bank’s depositors, including Circle, which restored its dollar peg.

Bordo argues that in the wake of the free banking era, it still took years of costly bank failures to get to the point where policymakers acted upon the realization that stability in the banking system required much more government intervention, supervision, and regulation than had existed. He notes, “There are always new entities that are going to figure out a way to be outside the regulatory net,” and stablecoins will not be any different.

As with any new financial innovation, the Fed will continue to study stablecoins to ensure that their benefits can be enjoyed by those who want to use them while maintaining overall financial and banking stability.

Readings

Gorton, Gary, and Jeffery Zhang. “Why Financial Crises Recur.” [archived PDF] University of Michigan Law and Economics Research Paper No. 24-069, June 25, 2025.

Jacewitz, Stefan. “Stablecoins Could Increase Treasury Demand, but Only by Reducing Demand for Other Assets.” [archived PDF] Economic Bulletin, Federal Reserve Bank of Kansas City, Aug. 8, 2025.

Spira, Jack, and David Wessel. “What Are Stablecoins, and How Are They Regulated?” [archived PDF] Brookings Commentary, Oct. 24, 2025.

“Stablecoins 2030: Web3 to Wall Street.” [archived PDF] Citi Institute, September 2025.

Download this article [archived PDF].

Related Webinar

PaymentsJournal is offering a webinar entitled “Stablecoins and the Reinvention of Remittance” on Tuesday, May 12, 2026 1:00-2:00 PM EDT.

RSVP for their webinar.

Author David ClarkPosted on May 7, 2026May 8, 2026Categories Economics, Essays, World WatchingTags 2023 United States banking crisis, accounting liquidity, Amazon (company), American Bankers Association, American Civil War, anti-money laundering, asset, audit, bank, bank account, Bank of America, bank reserves, bank run, banknote, bankruptcy of Lehman Brothers, bipartisanship, bitcoin, blockchain, capital (economics), cash, central bank, Christopher Waller, Circle Internet Group, Citigroup, collateral (finance), commodity, company, cost, COVID-19 pandemic, credit card, cryptocurrency, cryptocurrency exchange, currency, customer, debit card, debt, decentralized application, demand, deposit (finance), deposit insurance, developing country, digital asset, digital currency, economic sector, economist, economy, El Salvador, Ethereum, euro (€), Federal Deposit Insurance Corporation, federal government of the United States, Federal Reserve, Federal Reserve Bank of Kansas City, Federal Reserve Bank of Richmond, Federal Reserve Board of Governors, FedNow, fiat money, finance, financial institution, financial system, financial transaction, free banking, Gary Gorton, GENIUS Act, goods, government, government bond, inflation, insurance, interest, investment, Japanese yen (¥), JPMorgan Chase, jurisdiction, ledger, legislation, liquidation, loan, market (economics), Mastercard, Michael Barr (U.S. official), Michael D. Bordo, money, money market fund, non-bank financial institution, Office of the Comptroller of the Currency, payment, payment rail, payment system, PayPal, price, private currency, regulation, regulatory agency, regulatory compliance, remittance, repurchase agreement, Scott Bessent, security (finance), service (economics), smart contract, stablecoin, Stephen Miran, subsidiary, supply (economics), SWIFT, technology, Tether (cryptocurrency), United States, United States Congress, United States Department of the Treasury, United States dollar, United States Secretary of the Treasury, United States Treasury security, University of Michigan Law School, USDC (cryptocurrency), Visa Inc., Walmart, Yale University

Poly-Awareness, Checks & Commercial History

In an era moving towards electronic payment systems and replacing physical currency, it can be educational to look back at checks and how we arrived here. As Winston Churchill observed, “The longer you can look back, the farther you can look forward.”

In looking at history, it is just as important to study commercial practices as well as government leaders and military conquests.

…In the ten years following 1850, the world production of gold was ten times greater than in the ten preceding years. As is well known, the French had always preferred metal currency, and welcomed the gold with a special enthusiasm; the state struck an impressive quantity of coins, striking five hundred million in 1845, for the world’s gold found its way more readily to France where it fetched the highest price. The circulation of gold increased in other European countries also, and the banks of issue, in particular, filed their vaults. In this gold rush the English were more cautious after their long acquaintance with problems of values, and the upheaval in the gold market brought hardly any changes in the prices of the metal there. It is true England also minted new coins, but took advantage of it chiefly to establish her banking system more firmly. The influx of gold, which was exclusively Australian, had at first little effect on the prices of goods, but it developed credit with a paper currency. The minting of this money increased England’s metallic circulation by almost fifty percent, but the use of the banknote and especially of the cheque increased by a far higher proportion. The use of the cheque became so widespread in England that shopkeepers and farmers adopted it as the only possible way of doing business although it was almost unknown on the continent. Cheques were often used for amounts of less than two pounds. Even if he had an income of only fifty pounds a year, the Englishman immediately opened a bank account. In 1885, payments in metal currency represented only one per cent of the London Bank payments and six per cent of those in Manchester.

The Act of 1826 granted complete freedom of issue, except in an area of twenty-six miles around London, where the privilege of the Bank was absolute. There was a good deal of argument about the exact meaning of this privilege; for example the question arose as to whether provincial banks could open an office in London, the main centre of business, without losing their rights of issue.

When it was ruled that they could not, many banks nevertheless settled in London and forfeited their privilege of printing. Only the Scottish banks put up a firmer resistance to this extension of the privileges of the Bank of England. On the other hand, the right of issue was losing much of its significance, since the remarkable development of payment by cheque meant that there was less resort to the note. Settlements between the great deposit banks were made neither in metal nor in notes, but were transacted in the accounts of a clearing house, which dealt with transactions amounting to several hundreds of thousands of pounds every year.

The London and Westminster Bank, one of the most important of the English private deposit banks, soon became a model for every bank in Europe, for it had a reserve capital of less than three million pounds, and held approximately twenty-two million in deposits. Such influential private banks, established as joint stock companies, had to resort to the Bank of England only rarely, so the latter did not need to be unduly anxious about its insignificant gold reserves which were barely one-third of those held by the Banque de France. The privilege of issuing paper money, a relic of the royal right of minting money, was therefore bypassed to all intents and purposes by the gradual improvement of English banking procedure. At the same time the Bank of England enjoyed a monopoly of issue which it was in process of acquiring without the intervention of the state, since the development of banking led all the provincial banks to settle in London, near the clearing house. It was a masterpiece of liberalism to coordinate the free activity of the English economy in the capital without any pressure from the political power. In this way financial centralization was achieved purely by private initiative once the need for it had become apparent.

French banking evolved on very different lines. In order to meet the credit crisis, the provisional government had recommended the establishment of departmental banks and of trade credit societies when it was reforming the Banque de France. Most of these establishments, whose capital was to be provided partly by the state and the departments, were stillborn, while others lingered on for a month or two before wasting away. On the other hand, the Comptoir d’Escompte de la Seine became a private concern, and flourished under the name of the Comptoir National d’Escompte de Paris. The Banque du Département du Nord, which became the Crédit du Nord, was equally fortunate, as were several trade banks, particularly that of the Entrepreneurs de Travaux Publics. The unusual feature about the composition of the Comptoir National d’Escompte was that the Council of State had allowed it to set up as a joint stock company. Within a few years the Crédit Mobilier, the Crédit Industriel et Commercial, the Société Générale, the Société des Dépôtes et Comptes Courants, and other companies were established to benefit from this new way of accumulating capital.

Not all these new banks were as prudent as their English counterparts by any means and this point is worth dwelling on. After 1848 the Banque de France had the monopoly of issuing notes for the whole of France, because the local issuing banks created by Napoleon I and Louis-Philippe had been absorbed by the Banque de France, whose notes were the only ones in circulation. It was the state which had made this decision and had settled the problem of monetary unity by authoritarian measures. A few bankers, under the Second Empire, protested against the right of monopoly exercised by the Banque de France, which had been imposed on the whole of the country by the state. Very little use was made of payment by cheque, and compensation was meagre. The wide circulation of metal currency was a sign of a restricted paper currency, but this meant that credit was scarce and was based entirely on the Banque de France. The latter, taking no risks, consequently piled up in its coffers considerable reserves of precious metals, proud of the fact that it could now maintain a steady discount rate more easily than England. It also gained great satisfaction from being the gold-controller of Europe. Whenever a sudden drastic rise in the English bank rate sent businessmen, and even the Bank of England itself, as we have seen, hastening to Paris in search of precious metals, it was to the Banque de France that they turned. Although it was attacked by those who accused it of stifling credit, on the other hand it was defended by those who found its caution reassuring. It was a difference of opinion which further enlivened the quarrel between the Pereires and the Rothschilds.

As we know, Jewish bankers played a vital part in the building of the railways. Pereire, a railway enthusiast, and Rothschild, the largest holder of free capital in France, had at first been prepared to undertake the great task in complete agreement. Rothschild, content with holding the Nord and the English connections, was one of the directors whose word carried most weight in the Banque de France, while the Pereire brothers, their heads still full of Saint-Simonist projects, were interested in vast plans covering Austria, Spain and the Mediterranean. They financed the great development of the economy of the south although even so they were obliged to open a credit institution, the well-known Crédit Mobilier. But because they could not use it for the issue of paper notes, and had tied up the funds entrusted to them too quickly, the Pereires embarked on a struggle to deprive the Bank of its privilege of issue. They believed that the mere right of minting money would enable them to possess the wide credit necessary for the bold financial policy on which they were launching out. It so happened that when Savoy was annexed to France, the Banque de Chambéry brought its banknotes and its privileges within French frontiers. The Pereires and their friends seized the shares of this bank and tried to turn its notes into rivals of those of the central bank. The Banque de France then asserted its rights, Chambéry lost its rights of issue, and soon afterwards the Crédit Mobilier went into liquidation.

This incident occasioned a great quarrel between theorists for or against privilege; it was above all a demonstration of the solidity of the rights the Bank had acquired, while no-one doubted the right of the state to confirm its privileges any longer. This situation was all the more paradoxical since the state was in the hands of Napoleon III who was a firm supporter of the Pereires and the Crédit Mobilier. The underlying cause of this paradox lay in French scepticism about cheques, for the development of bank money lagged more than half a century behind England. It was to be chiefly the work of Henri Germain, founder of the Crédit Lyonnais. His patron of 1863 was mainly anxious to attract large deposits by guaranteeing them against theft and fire so that he insisted on the effective help the Bank could give industrialists and merchants by insuring their cash service itself. By making wise use of these deposits and by a cautious policy, the Crédit Lyonnais was able to open branches in Paris and Marseilles, so that it was soon as powerful as the Crédit Industriel et Commercial and then outstripped it. It even surpassed the Comptoir d’Escompte, and soon the Crédit Lyonnais became the leading French deposit bank. From 1860 it was the major bank to introduce cheques.

But there is little reason for surprise in the difficulties encountered by the cheque between 1860 and 1870.

The Banque de France was regarded as the most reliable of all issuing authorities, and French specie reserves as the most powerful stock of gold in the world; between notes and gold as the two methods of payment, there was very little room for the cheque. It is difficult to believe that France’s reserves could not have kept the deposit banks generously supplied, perhaps as much as, and even more than, the English reserves. But it kept a good part of its cash-balance in gold, which held up the full development of French credit institutions until the closing years of the nineteenth century.

In England there was security and in France hesitation, but in Germany there was an irresistible wave of enthusiasm which led to the rapid growth of credit institutions from 1840. There were a great many note-issuing banks in the Germany of the confederation, because each prince had his own currency. Hamburg had one of the soundest banks of issue, whose marc banco was esteemed throughout Europe and served as a standard for the whole of Germany. Nuremberg still had its old seventeenth-century bank and its florin, while a large number of private establishments were also manufacturing notes with a restricted circulation. In this scheme of things the Bank of Prussia held a pre-eminent position which was strengthened by the place Prussia had assumed in the Zollverein, but it still could not contest the superiority of Hamburg. In short, the legal position of the German banks was similar to that of the English, in that there was plurality of issue.

Bank money, and banknotes, increased in competition with each other, and the future of the four great and famous banks which were to dominate the destiny of capitalist Germany after 1880 had already begun to take shape.

The Dresner Bank was connected with the progress of the iron industry in the Rhineland, and particularly of Essen and Krupps. The Deutsche Bank operated in the countries of central Europe. The Darmstädter Bank and the Disconto Gesellschaft carved out a place for themselves; indeed bills on the latter increased from six to forty million marks between 1855 and 1862.

Charles Morazé, The Triumph of the Middle Classes: A Political and Social History of Europe in the Nineteenth Century, Anchor Books, 1968, pages 291-297.

Notice that in the discussion above, events are never monocausal. They are always part of a swirling tornado of change. If you become accustomed to this, the way the world works and the way the world changes will become more accessible to you.

For example, “The use of the cheque became so widespread in England that shopkeepers and farmers adopted it as the only possible way of doing business although it was almost unknown on the continent. Cheques were often used for amounts of less than two pounds.”

Also notice, “…soon the Crédit Lyonnais became the leading French deposit bank. From 1860 it was the major bank to introduce cheques.”

This is an example of poly-awareness, the core of meta-intelligence.

[Max Weber, in his book General Economic History, points out that the words “cheque” and “exchequer” derive from the same root.]

Author Richard MelsonPosted on April 9, 2026April 23, 2026Categories EssaysTags 17th century, 1840, 1845, 1848, 1850, 1855, 1860, 1862, 1863, 1870, 1880, 1885, 19th century, Australia, Austria, authoritarianism, bank, bank account, Bank of France, Bank of Prussia, bank reserves, banking in the United Kingdom, banknote, bullion coin, business, business magnate, capitalism, central bank, Central Europe, centralisation, cheque, clearing house (finance), coin, commerce, company, Comptoir national d’escompte de Paris, conquest, Conseil d’État, credit, credit crunch, Crédit Industriel et Commercial, Crédit Lyonnais, Crédit Mobilier, currency, Darmstädter Bank, deposit (finance), Deutsche Bank, Deutsche Mark, Disconto-Gesellschaft, Doubleday (publisher), economy, economy of England, England, English people, Essen, Europe, exchequer, finance, financial capital, financial transaction, florin, France, French people, General Economic History, German Confederation, Germany, gold, gold as an investment, gold reserve, goods, government, Hamburg, Hamburg mark, Henri Germain, History, history of the steel industry (1850–1970), income, insurance, Isaac Pereire, James Mayer de Rothschild, Jews, joint-stock company, Krupp steelworks, liberalism, liquidation, London, Louis Philippe I, Manchester, Marseilles, Max Weber, Mediterranean Sea, merchant, metal, military, mint (facility), mobile payment, money, monopoly, Napoleon, Napoleon III, Nuremberg, paper money, Paris, payment, payment system, Pereire brothers, Pound sterling, power (social and political), precious metal, price, private bank, provisional government, Prussia, rail transport, Rhineland, Rothschild family, Saint-Simonianism, Savoy, Second French Empire, settlement (finance), skepticism, Société des Dépôtes et Comptes Courants, Spain, state (polity), The Triumph of the Middle Classes, trade credit, Westminster Bank, Zollverein
November 2026
M T W T F S S
 1
2345678
9101112131415
16171819202122
23242526272829
30  
« Oct    

Categories

  • Essays (393)
    • Cinema (9)
    • Literature (2)
    • Mathematics (2)
    • Music (2)
    • Podcast (2)
    • Poetry (3)
    • Press Release (28)
    • Video (1)
    • World Watching (176)
      • Cinema (1)
      • Economics (122)
      • Education (2)
      • Government (2)
      • Mathematics (2)
      • Politics (1)
      • Science (31)
        • Biology (2)
        • Environment (5)
        • Medicine (5)
        • Philosophy (1)
        • Technology (4)
      • Webinar (5)
      • Zoom Meeting (4)

Tags

  • 19th century
  • 20th century
  • bank
  • China
  • climate change
  • consumer
  • COVID-19 pandemic
  • demand
  • Donald Trump
  • economics
  • economy
  • education
  • employment
  • Europe
  • Federal Reserve
  • finance
  • France
  • Germany
  • Gross Domestic Product
  • Harvard University
  • History
  • India
  • inflation
  • investment
  • Japan [日本]
  • loan
  • London
  • manufacturing
  • market (economics)
  • mathematics
  • monetary policy
  • philosophy
  • physics
  • politics
  • Russia
  • science
  • tariff
  • technology
  • trade
  • United Kingdom
  • United States
  • university
  • Western world
  • World War I
  • World War II
  • About
  • Contact
Meta Intelligence Proudly powered by WordPress