Japan-Watching: Yen Repatriation Starts with the Whale

GPIF, one of the largest national pension funds in the world, is likely to rebalance its assets from non-yen bonds to yen bonds, signaling a big turn in Japan’s cross-border capital flows.

[from Japan Macro Advisors, 10 September, 2026]

Key takeaways

  • In 2013, GPIF’s investment committee, chaired by UEDA Kazuo [植田和男], now the BoJ governor, saw a fair chance of a JGB crash within five to ten years. Its CEO priced the crash as the 10-year rising from 0.5% to 3%. Subsequently, GPIF cut its target weight for domestic bonds from 60% to 25% as an emergency measure against abnormally low yields.
  • The 10-year is now at 3%. On my replication of GPIF’s own allocation rule, a real return on JGBs near zero points to a 50% weight in domestic bonds, against 25% today. I expect GPIF to raise the weight, if it has not already started in the September quarter.
  • How GPIF decides its asset allocation and communicates it publicly is a very delicate and political issue. But regardless of how it communicates it, a change in asset allocation is inevitable. In my view, it signifies a big turn in Japan’s cross-border capital flows.

Japan has one of the Largest Pension Funds in the World

Japan has the second largest public pension fund in the world. Norway’s is the biggest, although it is not strictly a pension fund. Canada’s pension funds, when all eight of its variants are added together, come a close third.

Japan set up its first national pension fund in 1961 and it has since gone through various reforms and reorganization over the last 65 years. Its current form is called the Government Pension Investment Fund (GPIF). As explained in a later section, GPIF has a few siblings, and when we add them together, Japan’s public pension funds can be said to be the largest in the world.

Chart 1
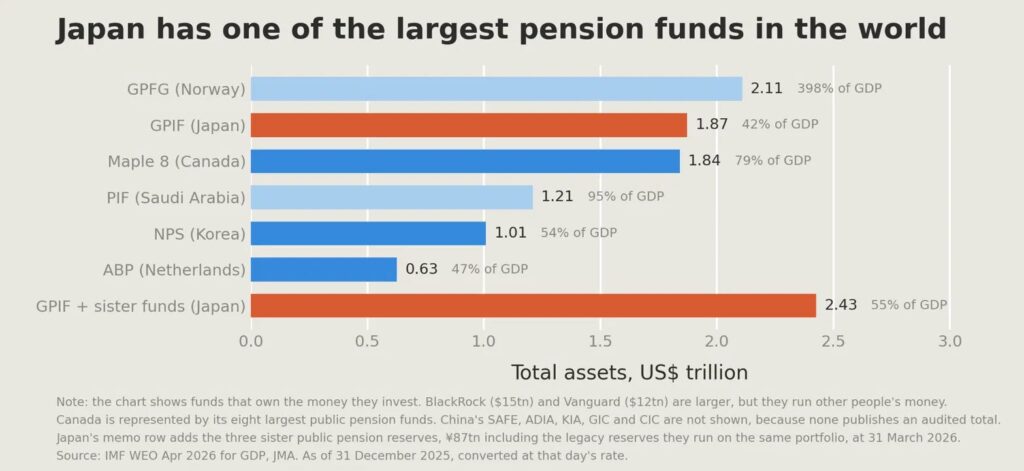
GPIF used to invest most of its asset into JGBs

GPIF used to invest the majority of its fund as loans to the national government and into Japanese government bonds (JGBs). At the end of FY2012, 62% of its assets consisted of domestic bonds. However, in 2014 it went through a radical asset reallocation and the target weight for domestic bonds was reduced from 60% to 35%, and then further down to 25% in 2020. Its current target allocation is a clean four-way 25% split into domestic bonds, domestic equity, foreign equity and foreign bonds.

As one of the largest pension funds in the world, its asset allocations attract market attention and there is speculation that it is about to raise its allocation into domestic bonds. In my view, there is indeed a very high chance that GPIF will be raising its allocation into domestic bonds, if it has not already started to do so in the current quarter ending in September 2026.

Chart 2
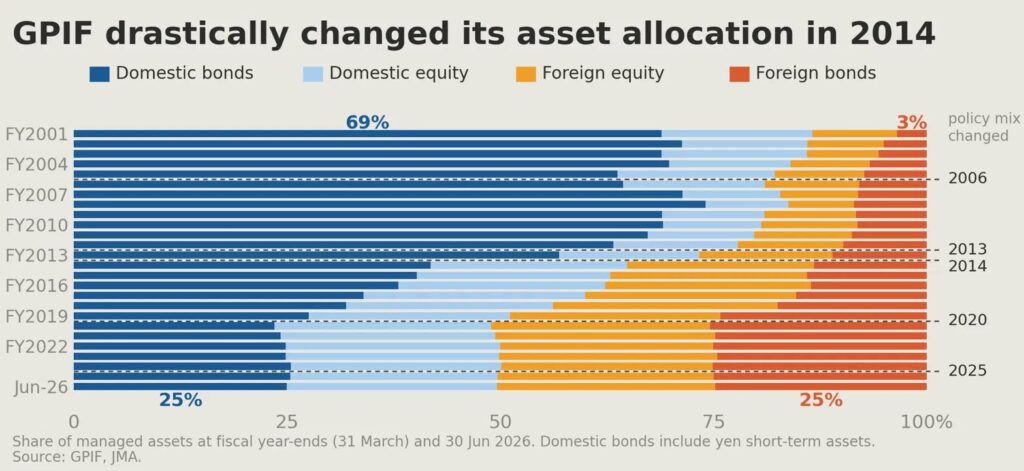
UEDA in 2013 Saw a Bond Crash Coming

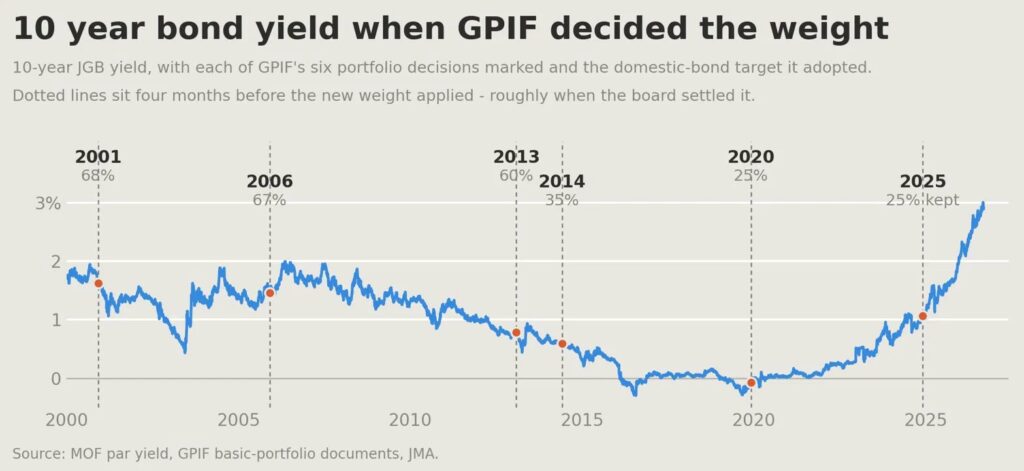
To understand why GPIF is highly likely to raise its allocation into domestic bonds, we need to go back in history to 2013. Why 2013? Of course, it is the year the Bank of Japan (BoJ) started its massive quantitative easing. The 10-year JGB yield started 2013 at 0.8% and it fell to 0.3% by the end of 2015 before briefly hitting a negative rate of -0.3% in 2016. If you were the chairperson of the GPIF investment committee, you would have been concerned about the wisdom of continuing to invest in JGBs at such a policy-driven low rate. The actual chairperson was UEDA Kazuo [植田和男], the current BoJ governor. In the minutes for October 2013, UEDA said, “I think there is a fair chance that bonds will crash at some point in the next five to ten years [unofficial translation].”

The minutes were released only seven years later; otherwise the use of the word “crash” would have been controversial.

GPIF CEO Priced the Crash at 3% in 2014. We Are There Now

If you read through the GPIF minutes between 2013 and 2014, you would see that GPIF officials were increasingly conscious of the precariousness of investing in JGBs. Long story short, as this process was highly political and a sensitive subject, they decided to radically lower the target allocation weight for JGBs to 35% in 2014, presented it as the result of a philosophical change in the way GPIF is managed and how the concept of “risk” should be considered. Investment in JGBs was no longer considered low risk in real terms. The asset allocation for domestic bonds was further lowered to 25% in 2020. The following is what MITANI Takahiro [三谷隆博], the GPIF CEO at the time and an ex-BoJ senior official, said in the October 2014 GPIF minutes.

“Yields are just under 0.5% now, so a move to near 3% would mean a loss of about ¥25 trillion. (…). So I think the clearest way to explain it is that reducing the weight on JGBs to some degree is simply unavoidable [unofficial translation]”

The 2014 cut in the weight was partly an emergency escape

As I wrote earlier, the radical asset reallocation in 2014 was part a shift in the concept of risk from “nominal” to “real”, so that JGB is no longer risk free assets. But the change was also at least partly an emergency measure to escape the abnormally low-yield environment. Then the next natural question is, now that the JGB yields are no longer abnormally low, what should happen to its asset allocation? Pensions are paid in yen, so long-duration Japanese government bonds are a natural match, while GPIF should also be holding some non-yen assets and equities to diversify its assets and protect the overall balance sheet from inflation. In the next section, I will show you a simplified replication of how GPIF decides its asset allocation and what GPIF’s asset allocation could be now that JGB yields are normal.
How GPIF decides its weights

Put simply, GPIF’s target weights are the output of an optimizer with a few rules. Find the portfolio that, at the required real return, has the smallest average shortfall below wage growth in the years when it falls short, and round it to the nearest 5%.

When GPIF last decided to keep the current 25% weight for domestic bonds in 2025, JGBs were assumed to produce a nominal return of 0.5% against wage growth of 1.3%, so a real return of minus 0.8%. Exhibit 1 shows a simplified matrix of weights depending on expected nominal return on bonds and wage growth. The red box shows the assumption behind the 2025 weights decision mentioned above. If we use a higher wage growth assumption of 2.3%, an expected nominal return of 1.8% on bonds gives a weight of 35%. GPIF’s bond portfolio has an average maturity around 10 years, and the 10-year bond is yielding 3% now. A lot of thought and estimation is needed to form a view on the expected real return on domestic bonds, but in my view, it is clear that the minus 0.8% used in their last review is too low given where bond yields are.
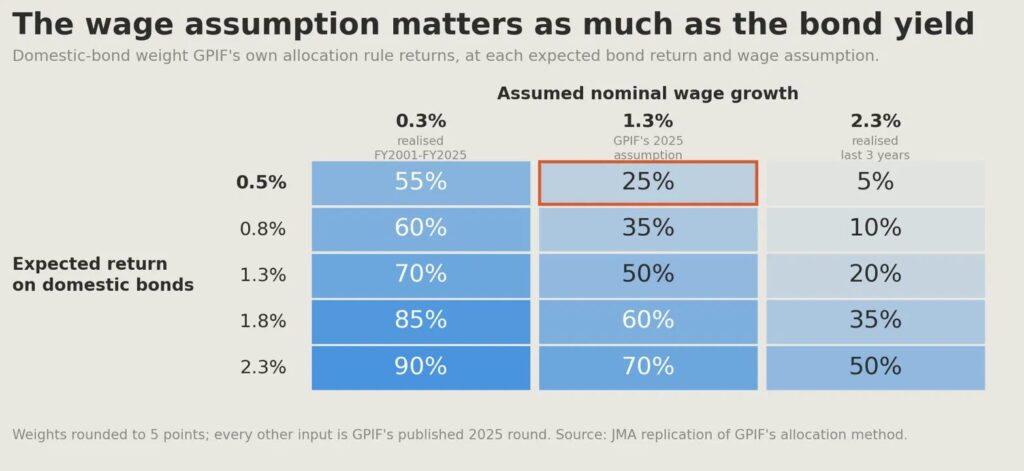
Why GPIF kept the weight in 2025 and why circumstances changed

In late 2024 when the GPIF was reviewing the weight as part of its five-year plan, the BoJ was already in the process of exiting from QE and raising its policy rate. However, the JGB market was still in the process of adjustment and bond yields had a lot of room to rise. For example, the 10-year yield was 0.89% at the end of September 2024, rose to 2% by the end of 2025 and now, in September 2026, stands at 3%. You can understand why GPIF decided to keep its weight on domestic bonds unchanged as it would have incurred capital losses on bond purchases in 2025. But in my view, as I wrote in the report “The Long Climb in JGB Yields Is Nearly Over” [archived PDF], long bond yields are getting closer to a stability point. If the GPIF board shares my view, it is a good time to think about raising its target weight into domestic yen bonds.

The Whale Problem and the Washington Problem

How high should the new weight be for domestic bonds? The reality of determining appropriate weights and how to announce it is a lot harder than the simplified model I explained above. Other than forming a reasonable view on the expected real return on asset classes, there are a few factors that complicate the process.

Firstly, GPIF needs to think about how such an announcement would affect the market. GPIF is what financial market professionals call a whale, a massive investor whose investment decisions sway market prices. There is also a related argument that given the dominance of GPIF in the domestic market, GPIF should be increasing its asset weight abroad to reduce its impact on domestic asset markets.

Secondly, changing asset allocation weights carries political considerations. If GPIF decides to raise the target weight for domestic bonds, foreign bonds are the likely asset class whose weight will go down. More than 50% of its foreign bonds are in US dollars. With all the news circulating in the market now, Scott Bessent will not like a public announcement that one of the largest pension funds in the world is reducing its purchase of US treasuries. There are domestic political considerations as well, as the Takaichi government contemplates how best to fund its deficits.

These are the issues GPIF officials must be debating. How GPIF decides its asset allocation in the near future will be a revealing case study for those who want to study how policy-making works in Japan. Those who are interested in this topic should read the transcripts of an interesting government committee in 2014 that focused on how GPIF could shield itself from political meddling. Guess who chaired the committee? UEDA Kazuo [植田和男].

Whatever the near-term decision GPIF makes regarding its target weight, I think it is fairly clear that GPIF should be increasing its investment into domestic bonds. The following table shows how much GPIF could buy in net terms, depending on the eventual rise in the target weight.

How much GPIF buys: ¥32tn at 35%, ¥80tn at 50%

Domestic Bond TargetGPIF BuysWith the Sister Funds
30%¥16tn¥20tn
35%¥32tn¥20tn
40%¥48tn¥20tn
50%¥80tn¥20tn

Additional domestic-bond holdings from re-weighting the fund at 30 June 2026 (managed assets ·317.8tn). Foreign bonds sold first.
Source: GPIF, JMA.

Three things in this table matter for the market. GPIF is allowed to deviate its asset allocation by six points either side of 25% without any announcement, so 39% target is already possible without any public announcement. In 2014 GPIF moved inside its band first and announced the new portfolio afterwards, and I would expect the same sequence this time. Second, these are static figures, which do not account for the growth of the fund over time.

The sister funds move with the whale

As mentioned earlier, GPIF has a few siblings. The Pension Fund Association for Local Government Officials (¥35.5tn), the Federation of National Public Service Personnel Mutual Aid Associations, known as KKR (¥11.5tn), and the Promotion and Mutual Aid Corporation for Private Schools of Japan (¥4.9tn) manage the pension reserves of local government employees, national government employees and private-school teachers. These sisters run their funds on the same 25/25/25/25 model, and with the legacy reserves they also run, they hold a further ¥87tn on top of GPIF’s.

Conclusion

GPIF cut its domestic bond weight from 60% to 35% in 2014, and later to 25%, to safeguard its assets from the manipulated low JGB yields at the time and the eventual crash they foresaw. That crash, as GPIF’s CEO MITANI defined it in 2014, has now happened with the 10-year yield rising to 3%. In my view, JGB yields have largely normalized and there is no emergency reason to avoid domestic bonds. It is only natural that GPIF would raise its allocation into domestic bonds, although how GPIF communicates this publicly is a touchy issue they need to figure out. When GPIF raises its domestic bond allocation, foreign bonds are the likely asset class to take the hit. GPIF publishes quarterly results and the next publication for the end-September 2026 quarter, expected in early November 2026, will be closely watched. Judging from market movements in the last few weeks, the market has started to sense that what I described in this article is already happening and Japanese money is starting to come back to the yen. While it should be characterized as rebalancing, rather than a repatriation, it seems we are observing a big turn in Japanese cross-border capital flows.

“De-Globalization?”

The classic study of the “swirl of processes and events” that ended previous globalization episodes is the theme of Princeton Professor Harold James’ 2002 book, The End of Globalization: Lessons from the Great Depression.

“Globalization” is here. Signified by an increasingly close economic interconnection that has led to profound political and social change worldwide, the process seems irreversible. In this book, however, Harold James provides a sobering historical perspective, exploring the circumstances in which the globally integrated world of an earlier era broke down under the pressure of unexpected events.

James examines one of the great historical nightmares of the twentieth century: the collapse of globalism in the Great Depression. Analyzing this collapse in terms of three main components of global economics—capital flows, trade and international migration—James argues that it was not simply a consequence of the strains of World War I, but resulted from the interplay of resentments against all these elements of mobility, as well as from the policies and institutions designed to assuage the threats of globalism.

Could it happen again? There are significant parallels today: highly integrated systems are inherently vulnerable to collapse, and world financial markets are vulnerable and unstable.

While James does not foresee another Great Depression, his book provides a cautionary tale in which institutions meant to save the world from the consequences of globalization—think WTO and IMF, in our own time—ended by destroying both prosperity and peace.

Legitimate fears about “globalization reversal” have been well put by Zakaria:

Davos, Switzerland —

President Trump’s speech here at the World Economic Forum went over relatively well. That’s partly because Davos is a conclave of business executives, and they like Trump’s pro-business message. But mostly, the president’s reception was a testament to the fact that he and what he represents are no longer unusual or exceptional. Look around the world and you will see: Trump and Trumpism have become normalized.

Davos was once the place where countries clamored to demonstrate their commitment to opening up their economies and societies. After all, these forces were producing global growth and lifting hundreds of millions out of poverty. Every year, a different nation would become the star of the forum, usually with a celebrated finance minister who was seen as the architect of a boom. The United States was the most energetic promoter of these twin ideas of economic openness and political freedom.

Today, Davos feels very different. Despite the fact that, throughout the world, growth remains solid and countries are moving ahead, the tenor of the times has changed. Where globalization was once the main topic, today it is the populist backlash to it. Where once there was a firm conviction about the way of the future, today there is uncertainty and unease.

This is not simply atmospherics and rhetoric. Ruchir Sharma of Morgan Stanley Investment Management points out that since 2008, we have entered a phase of “deglobalization.” Global trade, which rose almost uninterruptedly since the 1970s, has stagnated, while capital flows have fallen. Net migration flows from poor countries to rich ones have also dropped. In 2018, net migration to the United States hit its lowest point in a decade.

The shift in approach can best be seen in the case of India. In 2018, Prime Minister Narendra Modi came to Davos to decry the fact that “many countries are becoming inward focused and globalization is shrinking.” Since then, his government has increased tariffs on hundreds of items and taken steps to shield India’s farmers, shopkeepers, digital companies and many others from the dangers of international competition. The Office of the U.S. Trade Representative recently called out India for having the highest tariffs of any major economy in the world.

Indian officials used to aggressively court foreign investment, which was much needed to spur growth. Last week, with India’s economy slowing badly, Jeff Bezos announced a $1 billion investment in the country. (Bezos owns The Post.) But the minister of commerce and industry scoffed at the move, saying Amazon wasn’t “doing a great favor to India” and besides was probably engaging in anti-competitive, “predatory” practices. Often, protectionist policies help favored local producers. Malaysian Prime Minister Mahathir Mohamad recently criticized some of Modi’s policies toward Muslims. The Indian government effectively cut off imports of Malaysian palm oil. In a familiar pattern, one of the chief beneficiaries was a local billionaire long associated with Modi.

The Economist notes that Europe, once one of the chief motors for openness in economics and politics, is also rediscovering state intervention to prop up domestic industries. And if you think the Internet is exempt from these tendencies, think again. The European Center for International Political Economy tracks the number of protectionist measures put in place to “localize” the digital economy in 64 countries. It has been surging for years, especially since 2008.

It’s important not to exaggerate the backlash to globalization.

As a 2019 report by DHL demonstrates, globalization is still strong and, by some measures, continues to expand. People still want to trade, travel and transact across the world. But in government policy, where economic logic once trumped politics, today it is often the reverse. Economist Nouriel Roubini argues that the cumulative result of all these measures — protecting local industries, subsidizing national champions, restricting immigration — is to sap growth. “It means slower growth, fewer jobs, less efficient economies,” he told me recently. We’ve seen it happen many times in the past, not least in India, which suffered decades of stagnation as a result of protectionist policies, and we will see the impact in years to come.

Nevertheless, today, nationalism and protectionism prevail.

This phase of deglobalization is being steered from the top. The world’s leading nations are, as always, the agenda-setters. The example of China, which has shielded some of its markets and still grown rapidly, has made a deep impression on much of the world. Probably deeper still is the example of the planet’s greatest champion of liberty and openness, the United States, which now has a president who calls for managed trade, more limited immigration and protectionist measures. At Davos, Trump invited every nation to follow his example. More and more are complying.

“The world is de-globalizing. Trump set the example.” The Washington Post, Fareed Zakaria

Students should sense that while history does not repeat itself, it sometimes rhymes and this is a major danger. It also might imply that coping with climate change will be all the harder because American-led unilateralism everywhere would mean world policy paralysis.

Economics-Watching: Does Monetary Policy Affect Non-Mining Business Investment in Australia?

[from the Reserve Bank of Australia, by Gulnara Nolan, Jonathan Hambur and Philip Vermeulen]

Summary

Business investment is a key driver of economic growth. When investment is strong, workers have access to more capital and equipment, making them more productive and able to contribute to stronger productivity growth. Business investment is also thought to be an important driver of economic cycles and stimulating business investment is one of the key mechanisms through which monetary policy is thought to work.

However, non-mining business investment in Australia was fairly weak over much of the 2010s, despite declines in interest rates and moderate economic growth. While several explanations have been put forward, one potential explanation is that monetary policy is not very effective at stimulating business investment or has become less effective over time.

This study examines the effect of monetary policy changes on non-mining business investment using a variety of national and firm-level investment data, exploring both the aggregate effect of monetary policy and the channels through which monetary policy affects investment.

Abstract

We provide new evidence on the effect of monetary policy on investment in Australia using firm-level data. We find that contractionary monetary policy makes firms less likely to invest and lowers the amount they invest if they do so. The effects are similar for young and old firms, indicating that the decline in the number of young firms in Australia over time is unlikely to have weakened the effect of monetary policy. The effects are also broadly similar for smaller and larger firms. This suggests that evidence that some, particularly large, firms have sticky hurdle rates does not mean that they do not respond to monetary policy. It also suggests that overseas findings that expansionary monetary policy lessens competition by supporting the largest firms likely do not apply to Australia. We find evidence that financially constrained firms, and sectors that are more dependent on external finance, are more responsive to monetary policy, highlighting the important role of cash flow and financing constraints in the transmission of monetary policy. Finally, we find evidence that monetary policy affects firms’ actual and expected investment contemporaneously, suggesting that expectations are reactive and will tend to lag over the cycle.

Read the full paper [archived PDF].

Economics-Watching: Putting Out the NBFIRE: Lessons from the UK’s Liability-Driven Investment (LDI) Crisis

[from the International Monetary Fund Working Paper 2023/210]

by Ruo Chen & Esti Kemp

Liability-Driven Investment (LDI) funds were at the center of the severe stress that emerged in the UK gilt market in the aftermath of the September 2022 UK “mini-budget.” The episode, which came on the heels of the “Dash for Cash” and “Archegos” stress episodes in the previous two years, highlights underlying vulnerabilities in the large and diverse non-bank financial institution (NBFI) sector. This paper seeks a deeper understanding of the factors that amplified the gilt market turmoil which ultimately led the Bank of England (BoE) to undertake temporary gilt purchases on financial stability grounds in late September/early October 2022 to restore orderly market conditions and enable LDI funds to build their capital positions. With the gilt market stress and the BoE’s purchases now fully unwound, this paper identifies the key reasons for the success of the BoE’s intervention. Then, drawing also on findings of the 2022 UK Financial Sector Assessment Program (FSAP), the paper discusses key gaps and policy issues related to the monitoring of financial stability risks in the broader NBFI sector for both individual jurisdictions and international standard-setting bodies.

[read the working paper (archived PDF)]

World-Watching: Small Business and Food Waste: Not a Small Problem

[from APEC News]

by Aaron Sydor

Faced with a possible food crisis, economies must work together and take action on food waste … starting at the front line with MSMEs.

Conflict, supply disruption, rising prices, and shortages are all impacting food supplies globally. Just as we are nearing some form of recovery from the pandemic, we are now facing another global challenge in the form of a food crisis – and it’s likely to get worse.

The United Nations World Food Programme (WFP) tells us that 349 million people face acute food insecurity this year — an increase from 287 million people in 2021. It is a tragedy that when the world is “hungrier than ever,” as the WFP calls it, so much food goes to waste. One-third of food production, or 1.3 billion tons per year, goes to waste globally, according to the UN Food and Agriculture Organization. It is inconceivable, then, that we don’t make the most of the food that we have.

This is a regional problem that cannot be solved by individual economies acting on their own. It must be looked at with a wider lens, such as through bodies, like APEC, that promote regional economic cooperation. APEC members acknowledge that all areas of the agri-food value chain are interdependent and that there is a need for a whole-system approach.

Among the forum’s efforts to reduce food waste is the Food Security Roadmap Towards 2030 which aims to establish an open, fair, transparent, productive, sustainable and resilient APEC food system. This corresponds to the UN and other multilateral goals by taking action through the following avenues: digital transformation; productivity and international trade; sustainability; public-private partnerships; and inclusivity, especially in the inclusion of micro, small and medium enterprises (MSMEs) along the agri-food value chain.

For more on this topic, download “Enhancing Green MSMEs’ Competitiveness for a Sustainable and Inclusive Asia-Pacific: Food Sector Waste Reduction in Food Supply Chain.” [Archived PDF]

In my capacity as the Chair of APEC’s Small and Medium Enterprises Working Group, I’d like to stress the importance of the latter: inclusivity and small business. MSMEs account for over 97 percent of all business in APEC economies and employ over half of the workforce. Any strategy for reducing food wastage will have to involve the wholesale participation of the region’s smaller businesses.

This is easier written than done. For one thing, fit-for-purpose data is scarce. No APEC economy has food waste data that is specific to MSMEs. And while all have policies and measures to address the problem of food waste, there are no large-scale direct MSME–food waste reduction targets, policies or plans. Few have tried to reduce MSME food waste in the retail food and food service industries. Supermarkets, food storage facilities or warehouses in many APEC economies aren’t required to donate excesses.

Most entrepreneurs aren’t even aware of the problem, or underestimate its true cost. Those who do understand have limited options or capital, and are unable to find cost-effective solutions to create value out of food waste, and face problems with logistics and transportation. On top of this, there are few to no regulatory frameworks to guide them. From a technology perspective, a majority of APEC economies utilize modern technologies, including mobile applications, to reduce or manage MSME food waste/surplus food, but these modern technologies are used only by large companies in big cities.

Amid these challenges are an abundance of opportunities to help MSMEs reduce food waste. Training, policies and guidelines can aid them in improving profits by reducing costs and increasing the value added of food. They can reduce their carbon footprint, which enhances consumer demand, and divert waste to new products or bioenergy.

A November study by the APEC Small and Medium Enterprises Working Group presents case studies, identifies the best available data on food waste for MSMEs, and identifies several best practices for economies in dealing with food waste through MSME policy.

In one section, the study’s authors analyze a case study of a successful MSME, and identify four key factors contributing to its successful reduction of food waste: 1) creating a network of people — e.g., a community surrounding a farm; 2) using innovation and technology to facilitate farming and save time; 3) producing knowledge and providing it through several channels — e.g., a learning and training center, friendly guide books; and 4) considering the environment at every step of the process.

The paper, called “Enhancing Green MSMEs’ Competitiveness for a Sustainable and Inclusive Asia-Pacific: Food Sector Waste Reduction in Food Supply Chain,” [Archived PDF] is extensive and easily doubles as a handbook for anyone interested in MSME food waste, or the problem of food waste in general. It is a great example of what can be achieved when economies combine knowledge and resources in the pursuit of keeping the region inclusive, prosperous, and fed.

Aaron Sydor is the Chair of the APEC Small and Medium Enterprises Working Group.

Globalization and Its Nuances

The PBS TV program History Detectives had an episode entitled “Atocha Spanish Silver” where the wreck of the Spanish ship Atocha was described like this:

“In 1985, one of the greatest treasure discoveries was made off the Florida Keys, when the wreck of the Spanish ship Atocha was found. On board were some forty tons of silver and gold, which in 1622 had been heading from the New World to the Spanish treasury as the means to fund the Thirty Years’ War.”

Is this an obvious case of globalization? What about Marco Polo? Rome–Han dynasty China trade in silks? Silk Road and Samarkand? Colombus? Magellan? Vasco da Gama?

All of these cases constitute a kind of harmless kind of “pop globalization” based on exotic voyages and travels.

Consider another such example, perhaps more academic:

“About the middle of the sixteenth century Antwerp reached its apogee. For the first time in history there existed both a European and a world market; the economies of different parts of Europe had become interdependent and were linked through the Antwerp market, not only with each other but also with the economies of large parts of the rest of the world. Perhaps no other city has ever again played such a dominant role as did Antwerp in the second quarter of the sixteenth century.”

(Europe in the Sixteenth Century, Koenigsberger and Mosse, Holt Rinehart Publishers, 1968, page 50)

Debt repudiations in several places in the 1550s are described like this:

“This caused the first big international bank crash, for the Antwerp bankers now could not meet their own obligations.”

(Europe in the Sixteenth Century, Koenigsberger and Mosse, Holt Rinehart Publishers, 1968, page 51)

This sounds like some kind of identifiably global period.

Actually, modern historians define globalization as “price convergence” (i.e., wheat has now a unified “world price,” implying a world market). This rigorous definition is confirmed by and also shows up in the data in the 1820s and may or may not be prefigured by all the Marco Polo and Atocha silver stories, mentioned above.

These episodes in history are not there yet.

One sees wheat prices and other commodity prices converging in the 1820s and thereafter based on railroads, steamships and telegrams.

The classic in this kind of analysis is:

Globalization and History: The Evolution of a Nineteenth-Century Atlantic Economy, by Kevin O’Rourke and Jeffrey Williamson.

Kevin O’Rourke and Jeffrey Williamson present a coherent picture of In Globalization and History, Kevin O’Rourke and Jeffrey Williamson present a coherent picture of trade, migration, and international capital flows in the Atlantic economy in the century prior to 1914—the first great globalization boom, which anticipated the experience of the last fifty years. The authors estimate the extent of globalization and its impact on the participating countries, and discuss the political reactions that it provoked. The book’s originality lies in its application of the tools of open-economy economics to this critical historical period—differentiating it from most previous work, which has been based on closed-economy or single-sector models. The authors also keep a close eye on globalization debates of the 1990s, using history to inform the present and vice versa. The book brings together research conducted by the authors over the past decade—work that has profoundly influenced how economic history is now written and that has found audiences in economics and history, as well as in the popular press.

(book summary)

In everyday language, we associate the word globalization with some ever-increasing Marco Polo phenomena. While that’s not entirely wrong, globalization in the more technical sense begins to show up in the data only from the 1820s. At this point, we begin to see the convergence of worldwide wheat prices, for example. This makes the world, for the first time, a global “store” with unified prices. Here is the technical beginning of globalization. The years 1870-1914 are subsequently the first real era of modern globalization and represent a kind of “take-off” from the first stirrings of the 1820s. World Wars I & II might be seen as globalization backlash.

At this moment in world history, whether Putin’s invasion of Ukraine will constitute a new wave of deglobalization remains to be seen.

Countries and Deep Patternings: China

China’s High-Level Equilibrium Trap as a Concept

The Pattern of the Chinese Past
Mark Elvin
Paperback: 348 pages
Publisher: Stanford University Press; 1st edition (June 1, 1973)

The 1973 classic work in Sinology, Mark Elvin’s The Pattern of the Chinese Past gives the student an “exemplum” in the kind of scholarship that might be called “pattern-seeking.” Without such attempts, all of history becomes formless and shapeless and an endless parade of “routs and rallies,” and “crimes and follies and misfortunes” (in Edward Gibbon’s catchphrase).

Professor Elvin renders Chinese history through an economic perspective instead of using the common dynastic classification by attempting to answer three questions:

  1. What contributed to the continuity of the Chinese empire?
  2. Why was the Chinese economy the most advanced in the world from the Song dynasty (960-1279) up until the latter half of the Qing dynasty (mid-1800s)?
  3. Why did China fail to maintain her technological advantage after the mid-fourteenth century while advancing economically?

In the first section of the book, the author elucidates the staying power of the Chinese empire was due to the following factors. The economics of defense in relation to the size of empire and the power of its neighbors never became an extreme burden that it rendered the state impotent for any consecutively long period of time. It was always able to reformulate itself after a short disunity or rule by a foreign power of the whole, which only happened twice within a two thousand year period (Mongol and Manchu rule). Two other factors that contributed to the continuity of the Chinese state include a relatively isolated existence from the rest of the Eurasian landmass and the important placed on cultural unity, beginning with the first emperor’s destruction of local records in order to quell local loyalties (pp. 21-22). Both of these factors had been built up over time through a revolution in communication and transportation.

The second section of the book analyses the causes of the economic revolution that occurred between the 8th and 12th centuries and the technological growth that accompanied it. The transformation of agriculture, especially in the south, was the major impetus that fueled the economic growth of this period. This revolution in agriculture had four aspects.

  1. The preparation of soil became more effective as a result of improved or new tools and the extensive use of manure and lime as fertilizer.
  2. Seed improvements allowed for double cropping.
  3. Improvements in hydraulic techniques and irrigation networks.
  4. Specialization in crops other than basic food grains (p.118).

Improvements in transportation and communications were almost as important as agriculture in growing the economy. Water transport saw big gains and led to the golden age of geographic studies and cartography, with envoys traveling as far away as Africa. Money and credit matured during this time helping to expand the economy. Paper money made its first appearance in 1024. Improvements in science, medicine, and technology also occurred during this period. However, despite all these advancements, “this period was the climax and also the end of many preceding centuries of scientific and technical progress” (p. 179). Although the Chinese economy continued to advance from the 14th century on, albeit on a smaller scale, it was not accompanied by improvements in technology.

The last section deals with this phenomenon, describing the distinctive characteristics of this late traditional period (1300-1800), and then proceeding to point out why technological advancements did not keep pace with the growth in the economy. This period sees a rise of small market towns in the sixteenth century and a decline in contact with the non-Chinese world around the middle of the fifteenth century. Also, by the eighteenth century serfdom disappeared, aiding population growth, which had reached 400 million by the mid-1800s. Elvin interestingly points out that the highly sophisticated metaphysics that evaded Chinese intellectual thought during the Ming and Qing dynasties negated any deep scientific inquiry (p. 233). In the attempt to explain the lack of technological advancement, Elvin disputes a number of conventional explanations. Contrary to popular belief, there was enough capital during this period to finance simple technological advances, also there was minimal political obstacles to economic growth.

In short, Elvin believes “that in late traditional China economic forces developed in such a way as to make profitable invention more and more difficult. With falling surplus in agriculture, and so falling per capita income and per capita demand, with cheapening labor but increasingly expensive resources and capital, with farming and transport technologies so good that no simple improvements could be made, rational strategy for peasants and merchants alike tended in the direction not so much of labor-saving machinery as of economizing on resources and fixed capital. Huge but nearly static markets created no bottlenecks in the production system that might have prompted creativity” (p. 314). This condition is what he terms as a “high-level equilibrium trap.” The term “trap” to describe the condition of late imperial China’s technological advancement in relation to the economy is similar to Escape from Predicament, Thomas Metzger’s analysis of the “predicament” that confronted Chinese intellectual thought from the Song through to the end of the Qing dynasty. Both explanations have at their core the idea of late imperial China not being able to generate real sustainable progress internally, stating that it was the Chinese response to the Western threat in the mid to late 1800s that finally brought the needed change.

Movies As Parallel Universities: The Promised Land

The Promised Land is a Polish film masterpiece based on Nobel laureate Reymont’s 1899 novel. The novel describes the industrialization of the Polish city of Łódź in the nineteenth century and reminds one a little of Upton Sinclair’s The Jungle of 1906 but with the emphasis not on dangers and miseries for labor but on the “mad dance” of the capitalist industrial free-for-all:

“The Promised Land (Polish: Ziemia obiecana) is a 1975 Polish drama film directed by Andrzej Wajda, based on the novel by Władysław Reymont. Set in the industrial city of Łódź, The Promised Land tells the story of a Pole, a German, and a Jew struggling to build a factory in the raw world of 19th century capitalism.”

(Wikipedia)

Wajda presents a shocking image of the city, with its dirty and dangerous factories and ostentatiously opulent residences devoid of taste and culture. The film follows in the tradition of Charles Dickens, Émile Zola and Maxim Gorky, as well as German expressionists such as Dix, Meidner and Grosz, who gave testimony of social protest. Think also of the English poet, William Blake’s metaphor describing industrial England as a world of “dark Satanic mills.”

Reymont, the author of the original novel, was in his heart a ruralist and intensely disliked the modern industrial world, which he saw as maniacal and destructive.

In the 2015 poll conducted by the Polish Museum of Cinematography in Łódź, The Promised Land was ranked first on the list of the greatest Polish films of all time.

Plot

“Karol Borowiecki (Daniel Olbrychski), a young Polish nobleman, is the managing engineer at the Bucholz textile factory. He is ruthless in his career pursuits, and unconcerned with the long tradition of his financially declined family. He plans to set up his own factory with the help of his friends Max Baum (Andrzej Seweryn), a German and heir to an old handloom factory, and Moritz Welt (Wojciech Pszoniak), an independent Jewish businessman. Borowiecki’s affair with Lucy Zucker (Kalina Jędrusik), the wife of another textile magnate, gives him advance notice of a change in cotton tariffs and helps Welt to make a killing on the Hamburg futures market. However, more money has to be found so all three characters cast aside their pride to raise the necessary capital.

On the day of the factory opening, Borowiecki has to deny his affair with Zucker’s wife to a jealous husband who, himself a Jew, makes him swear on a sacred Catholic object. Borowiecki then accompanies Lucy on her exile to Berlin. However, Zucker sends an associate to spy on his wife; he confirms the affair and informs Zucker, who takes his revenge on Borowiecki by burning down his brand new, uninsured factory. Borowiecki and his friends lose all that they had worked for.

The film fast forwards a few years. Borowiecki recovered financially by marrying Mada Müller, a rich heiress, and he owns his own factory. His factory is threatened by a workers’ strike. Borowiecki is forced to decide whether or not to open fire on the striking and demonstrating workers, who throw a rock into the room where Borowiecki and others are gathered. He is reminded by an associate that it is never too late to change his ways. Borowiecki, who has never shown human compassion toward his subordinates, authorizes the police to open fire nevertheless.”

(Wikipedia)

Notice the sentence above:

Borowiecki’s affair with Lucy Zucker (Kalina Jędrusik), the wife of another textile magnate, gives him advance notice of a change in cotton tariffs and helps Welt to make a killing on the Hamburg futures market.

Textiles and hence cotton prices and tariffs are, as elsewhere, “the name of the game” in Łódź industry.

There is a concrete basis in reality for this 19th century version of our derivatives trading contributing to 2008 and the Great Recession:

In a discussion of futures markets, we read:

“Already in 1880 merchants were buying an idea rather than a palpable commodity, as we saw happen in the grains futures market. In that year, sixty-one million bags (coffee, in this example) were bought and sold on the Hamburg futures market, when the entire world harvest was less than seven million bags!

It was this sort of speculation that caused the German government to shut down the futures market for a while.”

(Global Markets Transformed: 1870-1945, Steven Topik & Allen Wells, Harvard University Press, 2012, page 234)

The danger with such speculative excesses is that the economy, national or global, becomes a “betting parlor” (bets on bets on bets in an infinite regress, as in the lead-up to 2008) and governments have been paralyzed and passive in the face of such “casino capitalism” (to use Susan Strange’s vocabulary) because laissez-faire neoliberal ideology has a profound hold in the West, especially in Anglo-America.

Professor Milton Friedman (died in 2006) argued in interviews going back to the 1960s and before, that speculators fulfill a valuable economic function since they “keep the system efficient.”

The current semi-dismantling and neutralizing of the Dodd-Frank financial reforms and guidelines has to do not only with lobbying but also with the hold of various strands of such “laissez-faire” ideology and market fundamentalism.

Keynes’s classic essay, “The End of Laissez-Faire” tends to yield to the countervailing force of this market fundamentalism/“laissez-faire religion.”