Henry Huiyao Wang: A New Compact for China and Europe

CCG President outlines opportunities for China and Europe to deepen cooperation in trade, investment, climate action, and global governance.

[from the Center for China & Globalization, 7 November 2026]

Henry Huiyao Wang [王辉耀], Founder and President of the Center for China & Globalization (CCG), has published an article titled “A New Compact for China and Europe” in the Autumn 2026 issue (No. 36) of Horizons, a journal published by the Center for International Relations and Sustainable Development (CIRSD).
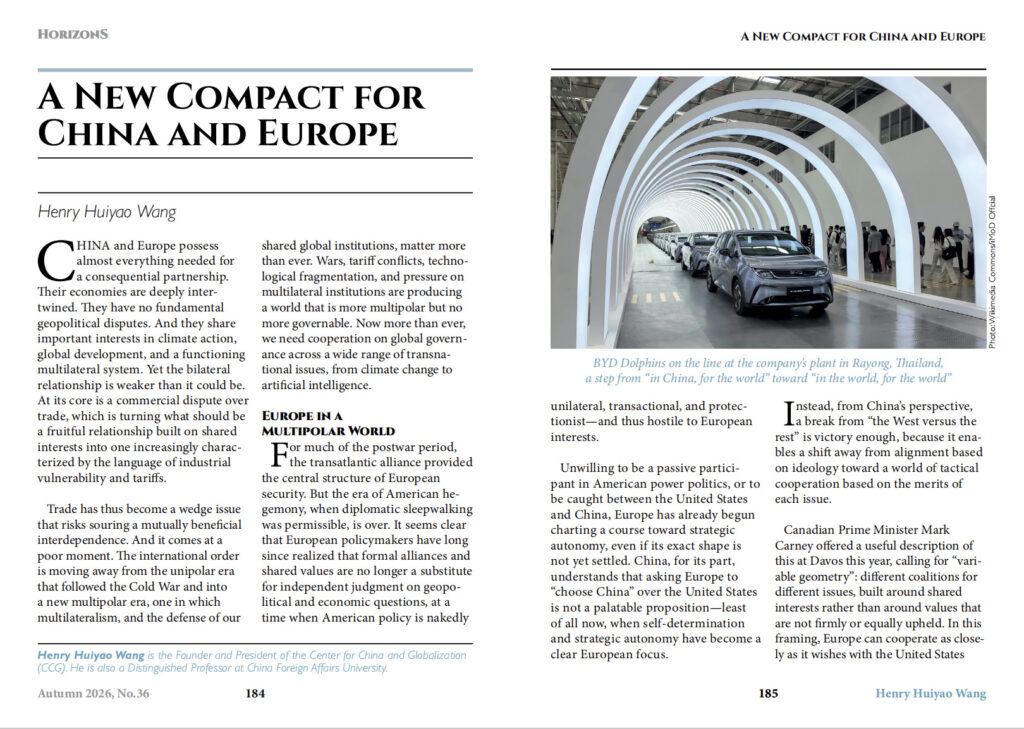
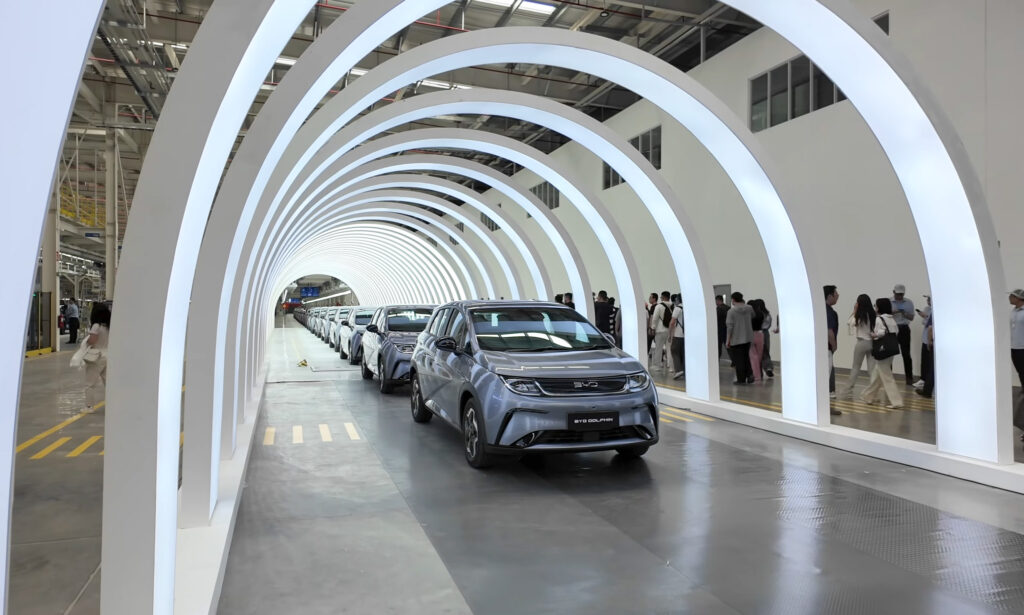
BYD Dolphins on the line at the company’s plant in Rayong, Thailand, a step from “in China, for the world” toward “in the world, for the world”
Wikimedia Commons/iMoD Official

China and Europe possess almost everything needed for a consequential partnership. Their economies are deeply intertwined. They have no fundamental geopolitical disputes. And they share important interests in climate action, global development, and a functioning multilateral system. Yet the bilateral relationship is weaker than it could be. At its core is a commercial dispute over trade, which is turning what should be a fruitful relationship built on shared interests into one increasingly characterized by the language of industrial vulnerability and tariffs.

Trade has thus become a wedge issue that risks souring a mutually beneficial interdependence. And it comes at a poor moment. The international order is moving away from the unipolar era that followed the Cold War and into a new multipolar era, one in which multilateralism, and the defense of our shared global institutions, matter more than ever. Wars, tariff conflicts, technological fragmentation, and pressure on multilateral institutions are producing a world that is more multipolar but no more governable. Now more than ever, we need cooperation on global governance across a wide range of transnational issues, from climate change to artificial intelligence.

Europe in a Multipolar World

For much of the postwar period, the transatlantic alliance provided the central structure of European security. But the era of American hegemony, when diplomatic sleepwalking was permissible, is over. It seems clear that European policymakers have long since realized that formal alliances and shared values are no longer a substitute for independent judgment on geopolitical and economic questions, at a time when American policy is nakedly unilateral, transactional, and protectionist—and thus hostile to European interests.

Unwilling to be a passive participant in American power politics, or to be caught between the United States and China, Europe has already begun charting a course toward strategic autonomy, even if its exact shape is not yet settled. China, for its part, understands that asking Europe to “choose China” over the United States is not a palatable proposition—least of all now, when self-determination and strategic autonomy have become a clear European focus.

Instead, from China’s perspective, a break from “the West versus the rest” is victory enough, because it enables a shift away from alignment based on ideology toward a world of tactical cooperation based on the merits of each issue.

Canadian Prime Minister Mark Carney offered a useful description of this at Davos this year, calling for “variable geometry”: different coalitions for different issues, built around shared interests rather than around values that are not firmly or equally upheld. In this framing, Europe can cooperate as closely as it wishes with the United States on defense, while still finding common cause with China on climate and trade reform, or with India on development. Such flexibility is increasingly the default in our plural world.

A cohesive Europe able to act independently is preferable to a divided continent whose China policy is increasingly shaped elsewhere. But that also means that policymakers in China must address European fears if they are to benefit from engagement and cooperation on shared interests.

The Changing Bargain

The core anxiety facing Europe, and the one undermining a merits-based relationship, is that the old, unspoken economic bargain—European technology and premium manufacturing in exchange for Chinese consumer goods and lower-cost production—is giving way to a more competitive relationship.

China now possesses broad industrial ecosystems, world-class infrastructure, skilled engineering talent, and the capacity for fast commercialization at scale. It no longer competes on wages alone. In electric vehicles, batteries, solar energy, machinery, telecommunications equipment, and, increasingly, advanced digital applications, Chinese firms can combine cost, speed, and technological capability.

But let us not get carried away with catastrophizing. The shared economic foundation between China and the EU remains immense. In 2025, two-way trade in goods and services exceeded €880 billion. Europe imported more than €570 billion in goods from China and exported about €200 billion, producing a large bilateral goods deficit. Yet this figure should be interpreted carefully. The European Union still recorded an overall goods surplus of approximately €128 billion in 2025, as well as a substantial current-account surplus. Nor are all imports finished products: Eurostat data shows that 57 percent of all extra-EU goods imports in 2025 were intermediate products, meaning that much of what Europe imports feeds into value-added production chains from which Europe itself benefits. Europe’s difficulty is that, while its industry remains broadly profitable, certain critical sectors are already under pressure, and the trend seems unlikely to reverse suddenly in favor of European manufacturing.

Europe is not facing this crisis in a vacuum, either. It is compounded by high energy costs, aging populations, fragmented capital markets, and chronic underinvestment. The result is a genuine fear of deindustrialization, with the attendant loss of skilled employment, supplier networks, technological capacity, and social cohesion. This worry is especially potent in the major European economies with large export-oriented manufacturing sectors, such as Germany, France, Italy, and Spain, and it makes the debate over “overcapacity” deeply politically charged.

While the imbalance is a product of industrial excellence, it can also be attributed to weak domestic demand in China. Household consumption there remains around 40 percent of GDP, while families save heavily out of concern over housing, education, health care, and retirement. The 2025 consumption action plan addressed wages, pensions, health care, childcare, paid leave, and benefits for migrant and flexible workers, and China’s first five-year plan devoted specifically to consumption subsequently set a goal of approximately 60 trillion yuan in retail sales by 2030. But it is far too early to call the effort complete. Although per capita disposable income rose by 5 percent and consumption expenditure by 4.4 percent in 2025, the first half of 2026 was weaker, and overall consumption still lags behind where it should be. Stronger pensions, health care, unemployment insurance, childcare, and portable benefits for migrant workers will help reduce precautionary saving, and greater access for foreign goods and services would ensure that stronger Chinese demand creates opportunities for European producers. That transformation, however, is not yet complete.

Europe, for its part, should recognize that competitive success is not in itself an unfair subsidy. The International Energy Agency estimates that producing a battery-electric vehicle costs more than 30 percent less in China than in advanced economies, with only about one-third of the gap attributable to the battery; a similar cost gap exists for conventional vehicles. China’s earlier industrial policies undoubtedly helped establish this ecosystem, but important forms of direct support, including national EV purchase subsidies, have already been phased out.

Rhodium Group estimates that BYD enjoys a cost advantage of approximately $4,700 per vehicle over Tesla’s operations in China, of which grants account for only about $292, while vertical integration and lower research, administrative, and supplier costs explain at least three-quarters of the difference. BYD produces roughly 70 percent of its components in-house, including its batteries. Europe should investigate market-distorting support and is right to insist on transparency, but it should not define the ecosystem, technology, and efficiencies China has built as unfair.

Nor is China’s automobile sector insulated from competition. The number of Chinese electric-vehicle makers was reported at 487 in 2018; by 2025, consolidation had reduced the market to approximately 129 brands produced by about 50 manufacturers, and only 10 to 15 are expected to be profitable by 2030. China exported approximately 5.86 million of the more than 31 million vehicles it sold in 2024, meaning that the large majority were still absorbed at home. By comparison, Volkswagen delivered 9.03 million vehicles worldwide but only 1.12 million in Germany, while Toyota and Lexus sold 10.16 million worldwide and 1.44 million in Japan. Airbus, likewise, sells approximately 68 percent of its aircraft outside Europe. Producing for global markets is accepted as normal when established European or Japanese companies do it; it should not automatically become illegitimate when Chinese firms do the same.

China’s textile industry offers a further precedent. Even as wages rose and some production moved to Vietnam, Bangladesh, and elsewhere, China retained 37 percent of global textile exports and 34 percent of clothing exports in 2017, because supplier clusters, infrastructure, skills, and continual upgrading proved more durable than low labor costs alone.

Beyond economic competition, clearer rules are urgently needed on the securitization of critical industries. The dispute over Nexperia—the Chinese-owned semiconductor company placed under Dutch government control in 2025—rattled supply chains and deepened concern in China about investing abroad. Either the company should not have been sold in the first place, or a clearer regulatory environment might have avoided a quasi-nationalization that rapidly internationalized a corporate dispute, and that still hangs over the mutual investment relationship today.

Likewise, proposals for a European instrument modeled on the United States’ Section 301 powers may offer political reassurance, but Section 301 is a blunt unilateral instrument designed to authorize retaliation. Europe would be better served by an explicitly transitional mechanism. Where an import surge threatens to destabilize domestic markets, temporary safeguards can provide time for adjustment, but they should be evidence-based, reviewable, and subject to firm sunset clauses. Their purpose should be to facilitate adaptation and negotiation, not to turn emergency protection into a permanent wall.

An Industrial Compact for Shared Competitiveness

When I visited Jean Monnet’s house outside Paris this summer, I was reminded of the method that helped build modern Europe: begin with concrete achievements that create the basis for solidarity. That method matters especially now, when trade has become a wedge issue and trust and trade cannot be separated.

We must therefore build a new industrial compact: one that aligns Chinese industrial capacity with Europe’s need for investment, innovation, and employment, and that enables China and Europe to stand together in support of a world of free, fair, and open trade.

First, China should follow through on its ongoing shift from an export– and investment-heavy model toward consumption-led growth. Alongside the social measures described above, this requires reducing the barriers faced by private and foreign businesses, improving market access in services and public procurement, and applying regulation more transparently. European companies should be able to compete in China with confidence that they will receive equal treatment and can protect their intellectual property.

Second, Europe needs to draw a sharper distinction between trade in products that present a genuine security risk and investment that strengthens European productive capacity. Concerns about supply-chain resilience and security in defined strategic sectors are unavoidable, given increasing regionalization. But a presumption against Chinese investment would deprive Europe of capital, technology, competition, and jobs precisely when it needs them most. Instead, Europe could openly welcome investment that meets its requirements on governance, data protection, labor standards, and environmental performance, while increasing the local economic contribution such production provides.

This openness should be anchored by a renewed Comprehensive Agreement on Investment. The agreement reached in principle in 2020 was never implemented and the relationship has changed too much for it simply to be revived unchanged. China and Europe should instead negotiate a new CAI covering market access, national treatment, subsidy transparency, technology transfer, public procurement, and enforceable dispute resolution. It should give European companies more predictable access to China, while establishing clear and consistent conditions for Chinese market access and investment in Europe, with an eye to creating employment and supplier networks there.

China has already demonstrated the value it places on market access by extending tariff-free treatment to goods from 53 African countries, and it could move explicitly to align its standards more closely with Europe’s. Europe, for its part, should reconsider its technology and investment restrictions—especially those implemented specifically to protect U.S. interests, such as the restrictions preventing China from purchasing advanced semiconductor equipment from ASML. Working examples of Chinese investment in Europe already exist. Chinese companies are investing in battery and vehicle production in Hungary, Slovakia, Spain, and Serbia, while European manufacturers—including Volkswagen, BMW, and Mercedes-Benz—continue to deepen their research, production, and partnership networks in China. These investments should not be viewed as isolated commercial transactions. They can become the architecture of a more balanced relationship.

Third, localization must mean more than final assembly. Joint ventures and investment agreements can encourage local supplier development, worker training, research partnerships, and the sharing of production know-how, while respecting intellectual-property rights. Chinese industry was once buoyed by European know-how through joint ventures; in return, European industry can now benefit from Chinese advances. The goal should be a competitive ecosystem in which both Chinese and European firms have a stake.

Fourth, any trade measures should be targeted and temporary. If an import surge threatens serious injury, safeguards can buy time for adaptation. But they should have clear evidentiary thresholds, sunset clauses, and review procedures. Protection without a productivity strategy merely postpones decline and risks marginalization, rather than allowing a dynamic industrial sector to emerge. At the same time, Europe can and should complete its own agenda: lowering energy costs, deepening the single market, mobilizing investment, scaling up innovative companies, and improving infrastructure.

Here, China can become Europe’s “fitness partner.” The phrase may sound counterintuitive at a moment of industrial anxiety, but the underlying idea is important. Healthy competition from China can push European companies and governments to confront long-delayed reforms, reduce costs, and innovate faster. Shelter from competitive pressure does not create health; competition, by contrast, can serve as a yardstick for rebuilding strength. China, meanwhile, gains more from a prosperous and capable Europe than from a weakened market increasingly hostile to Chinese commerce.

Finally, the compact should look beyond the bilateral market. Chinese and European joint ventures could look abroad, toward the product and development needs of the Global South. Joint production for Global South markets could be a starting point, moving in time toward joint financing of development and infrastructure to accelerate green industrialization in Africa, Asia, Latin America, and the Middle East.

This would represent the next stage of globalization: not simply Chinese companies “in China, for the world,” but “in the world, for the world.” It would spread productive capacity more widely, answer concerns about concentrated supply chains, and make development a shared undertaking rather than an arena for geopolitical competition.

From Commercial Trust to Strategic Cooperation

An industrial compact cannot by itself remove all political differences. But it would serve as a springboard, and a trust-building exercise, for deeper commitments and further work on shared interests.

Climate cooperation is the most obvious bridge. China’s manufacturing scale has lowered the global cost of solar panels, batteries, and electric vehicles, in a very real way underwriting the transition away from fossil fuels. At the same time, Europe is suffering under the weight of an energy crisis born of Russia’s invasion of Ukraine and, more recently, of upheavals in the Middle East around the Strait of Hormuz and the Bab al-Mandeb. A natural alignment would be for China and Europe to build a green partnership that helps wean the world off volatile fossil fuels and address the climate crisis. The exact shape of such measures is not yet defined, but using joint ventures, cooperation, and technology exchange to tap Chinese expertise and cost advantages could benefit both sides while buoying the global green transition. A tariff spiral in clean technology, by contrast, would make the energy transition slower and more expensive for everyone.

More broadly, China and Europe share an interest in conflict resolution. China has always been clear that sovereignty and territorial integrity apply universally, that nuclear escalation is unacceptable, and that a negotiated settlement must provide credible security for all parties. But it can do more to ease the concerns of a Europe that feels threatened by a Russia now in its fifth year of fighting in Ukraine. Working together, Europe and China could help provide an off-ramp, each using its leverage to bring the negotiating positions closer together. A truly durable settlement, acceptable to both sides, may eventually require security guarantees involving both European and non-European countries, and China could contribute through reconstruction, nuclear safety, and peacekeeping. The Middle East is another region where common interests are greater than current policy coordination suggests. Continued conflict and volatility around the straits have not only given fresh impetus to the transition away from fossil fuels but also created a new area of shared interest. Together, Europe and China could support a peace architecture with wider international participation.

Artificial intelligence governance is another opportunity. China and Europe approach data, platforms, and regulation differently, but both reject a future in which a handful of private companies set global rules without public accountability. They can work together on safety testing, scientific exchange, interoperable standards, and the application of AI to health, climate, and development. Agreement will be difficult, but building a shared environment for rule-making would help hedge against fragmentation in this rapidly developing field.

Finally, China and the EU have both long advocated restoring the World Trade Organization. A revitalized WTO already contains tools to address subsidies and demonstrable injury. Boeing and Airbus were both found, in WTO disputes, to have benefited from improper support, and those cases were handled through multilateral proceedings rather than through an open-ended campaign against either side’s wider industrial success. The WTO’s dispute-settlement system must now be restored, its rules on subsidies and state enterprises updated, and its development functions strengthened. The United States weakened that system by blocking appointments to the Appellate Body after adverse rulings; but China and Europe are both major beneficiaries of an open trading system, and both can press for reform.

None of this will be sustainable without renewed contact between societies. Direct flights, student exchanges, tourism, university partnerships, city-to-city links, and think-tank dialogue all have their roles to play, for they are the infrastructure of mutual understanding.

China–Europe relations will not always be perfectly aligned, and they will likely continue to contain elements of cooperation, competition, and disagreement. But together, we can put to rest the prospect of weaponized interdependence and move instead toward win-win interdependence.

Europe does not need to become less European in order to cooperate with China, nor does China need to adopt European political mores for cooperation to succeed. Both are now free to cooperate selectively and on the merits of each issue. And a world in which China and Europe cannot find areas of deep mutual interest—despite their deep economic ties and their shared stake in multilateralism—is a world that is measurably poorer for it.
Economics-Watching: Drewry Container Shipping Financial Insight, August 2025

[from Drewry Shipping Consultants, 22 August 2025]

Container shipping companies have reported mixed 2Q25 results. Read the article [archived PDF] for key takeaways from 2Q25 results and other key developments shaping the container shipping sector.

About Drewry Maritime Financial Research

Drewry Maritime Financial Research (DMFR), is the marketing name of Drewry Financial Research Services Ltd. DMFR, is an independent equity research service focused on the maritime industry. DMFR’s parent organisation, Drewry Shipping Consultants Holdings Limited was established more than 50 years ago and is now widely regarded as one of the leading independent sources of global industry analysis and insight. This in-depth industry knowledge is fully applied in our analysis of quoted maritime companies.

Economics-Watching: Why Businesses Say Tariffs Have a Delayed Effect on Inflation

[from the Federal Reserve Bank of Richmond, 8 August, 2025]

by R. Andrew Bauer, Renee Haltom and Matthew Martin

Regional Matters

Ever since new tariffs were enacted in early 2025, a key policy question has been what is the extent to which businesses will pass tariff costs through to prices, and when? The effects of a tariff are rarely straightforward, given, among other things, competitive dynamics and the challenges of implementation, but the historically large and changing nature of these tariffs have created additional levels of uncertainty over the effects.

In uncertain times, anecdotal evidence from businesses can be especially insightful. We are learning how businesses are reacting to tariffs through the Richmond Fed’s business surveys as well as through hundreds of one-on-one conversations with Fifth District businesses since the start of 2025.

These conversations showcase that navigating tariffs is a complex and sometimes protracted process for firms, particularly when there is uncertainty. Firms describe several reasons they may not have experienced the full impact of proposed tariffs yet (even when goods and countries they deal with are subject to them), as well as reasons that even when they have incurred tariff-related cost increases, there can be a delayed impact on pricing decisions.

Reasons Firms May Not Have Incurred Tariffs Yet

Business contacts describe several strategies or circumstances that can delay or reduce the tariffs on inputs or other imported items. These include the following:

As our monthly business surveys have found, many firms report deploying more than one strategy to delay tariffs. Notably, many of these delays are only temporary.

Reasons Tariffs May Have a Delayed Impact on Prices

Even when firms have incurred tariffs, they give several reasons why tariffs may not be immediately reflected in the prices they charge for their products. These include the following:

  • Waiting for tariff policy to clarify. Higher prices could reduce demand for goods and services and/or lead firms to lose market share, so many firms said they are hesitant to increase prices until they’re sure tariffs will remain in place. For example, a large national retailer said if tariffs are finalized at a sufficiently low level, they’ll absorb what they’ve incurred to date, but if high tariffs stick, they’ll have to raise prices. A steel fabricator for industrial equipment described being reluctant to raise prices on the 10 percent cost increases they’d seen thus far but would have to raise prices should the increases reach 12 to 13 percent. A grocery store chain was reluctant to raise prices and instead might reduce margins, which had recovered in recent years, to maintain their customer base. Some firms explicitly noted a strategy to both raise prices over time and pursue efficiency gains to cut costs and completely restore margins within a year or two.
  • Elasticity testing. Firms reported testing across goods whether consumers will accept price increases. A furniture manufacturer said he’s seen competitors pass along just 5 percentage points of the tariffs at a time so it isn’t such a huge shock to customers, though in that sector, “We all end in the same place which is the customer bearing most of it.” A national retailer said most firms are doing a version of stair-stepping tariffs through, e.g., raising prices a small amount once or twice to see if consumer demand holds, and if so, trying again two months later. This retailer said prices were going up very marginally in early summer, would increase more in July and August, and would be up by 3 to 5 percent by the end of Q4 and into 2026. Another national retailer said they would start testing the extent to which demand falls with price increases, e.g., when the first items that were subject to tariffs—in this case back to school items—hit shelves in late July.
  • Blind margin. Some firms reported attempting to pass through cost in less noticeable ways. While any price increase to consumers will be captured in measures of aggregate inflation, the fact that price increases may occur on non-tariffed goods might make it difficult to directly relate price increases to tariffs. An outdoor goods retailer said, “Unless it’s a branded item where everyone knows the price, if something goes for $18, it can also go for $19.” A national retailer plans to print new shelf labels with updated pricing, which will be less noticeable for consumers compared to multiple new price stickers layered on top. This takes time (akin to a textbook “menu cost” in economics), so it will not be reflected in prices until July and August. A grocery store said their goal was to increase average prices across the store but focus on less visible prices.
  • Selling out of preexisting inventory: Many firms noted they still have production inventory from before tariffs were announced, so they do not need to raise prices as long as they still sell these lower cost goods. A national retailer noted they have at least 25 weeks of inventory on hand for most imported products. A firm that produces grocery items said they will decide how much to raise prices as they get closer to selling tariff-affected products. Similarly, retailers order seasonal items quarters in advance. Many were receiving items for fall and winter when the new tariffs were going into effect in the spring. They paid the tariff then, but we won’t see the price increase until those items hit the shelves in the fall or winter. One retailer speculated that seasonal décor items will look the most like a one-time increase.
  • Pre-established prices. Many firms face infrequent pricing due to factors like annual contracts or pre-sales. For example, a dealer of farm equipment gets half its sales through incentivized pre-sales to lock in demand and smooth around crop cycles. They noted that while it would be difficult to retroactively ask those customers to pay for part of the tariff, they will pass tariffs directly through on spare parts. A steel fabricator for industrial equipment has a contract for steel through Q3, so they haven’t been impacted yet by price increases. However, they will face new costs once that contract expires.

In general, compared to small firms, large firms have more ability to negotiate with vendors, temporarily absorb costs, burn cash, wait for strategic opportunity, and test things out. This matters because large firms often lead pricing behavior among firms, so these strategic choices may influence the response of inflation to tariffs more generally. Even within firm size, one often hears that negotiations on price vary considerably by relationship and item.

Conclusion

A key question surrounding tariffs is whether any effects on inflation will resemble a short-lived price increase—as in the simplest textbook model of tariffs—or a more sustained increase to inflation that may warrant tighter Fed monetary policy. When asked in May what will determine the answer, Fed Chair Jerome Powell cited three factors [archived PDF]: 1) the size of the tariff effects; 2) how long it takes to work their way through to prices; and 3) whether inflation expectations remain anchored. The insights shared above suggest the process from proposed tariffs to the prices set by firms is far from instantaneous or clear-cut, particularly when tariff policy is changing.

Sensing from businesses suggests that the impact of tariffs on their price-setting [archived PDF] has been lagged, but it is starting to play out. Nonetheless, it remains highly uncertain how tariffs will impact consumer inflation. The discussion above makes clear that firms are nimble and innovative in the face of challenge, and they are concerned about losing customers in the current environment, particularly consumer-facing firms. We will continue to learn from our business contacts and share their insights.


Views expressed are those of the author(s) and do not necessarily reflect those of the Federal Reserve Bank of Richmond or the Federal Reserve System.

China to Sustain Top-Down, Debt-Fueled Investment in Major Projects and Security Capacities, Ex-Official Says

Dong Yu, now at Tsinghua, says via state media that Beijing-decreed, central govt bond-backed construction will continue into the next five years.

[from the Center for China & Globalization’s Pekingology]

by Zichen Wang, 10 August, 2025

The key concept in today’s newsletter is 国家重大战略实施和重点领域安全能力建设, in abbreviation in Chinese as 两重 liǎng zhòng.

In English, it is translated officially as the implementation of major national strategies and building up security capacity in key areas, hereinafter referred to as “Two Major Undertakings.”

The concept first appeared in official policy documents in the Chinese Premier’s Report on the Work of the Government [archived PDF] in March 2024.

To systematically address funding shortages facing some major projects for building a great country and advancing national rejuvenation, it is proposed that, starting this year and over each of the next several years, ultra-long special treasury bonds be issued. These bonds will be used to implement major national strategies and build up security capacity in key areas. One trillion yuan of such bonds will be issued in 2024.

By the end of the year, the yuan tag, despite being approved by the national legislature, had changed by 300 billion. The People’s Daily newspaper reported in December 2024.

As of now, the 700 billion yuan in ultra-long-term special treasury bonds allocated for the “two major undertakings” has been distributed in three batches to specific projects.

In 2025, the following year, the Report on the Work of the Government [archived PDF] says,

A total of 1.3 trillion yuan of ultra-long special treasury bonds will be issued, 300 billion yuan more than last year.

735 billion yuan will be earmarked in the central government budget for investment. We will put ultra-long special treasury bonds to good use, increase ultra-long-term loans and other types of financing support, and strengthen top-down organization and coordination to ensure greater support for the implementation of major national strategies and security capacity building in key areas.

A simultaneous Finance Ministry budget plan [archived PDF] rounds up the overall central government spending for the Two Major Undertakings to 800 billion yuan in 2025.

In yuan terms, the much-touted new government subsidies to households pale in comparison with the two major undertakings.

Also from the 2025 Report on the Work of the Government [archived PDF]:

Ultra-long special treasury bonds totaling 300 billion yuan will be issued to support consumer goods trade-in programs. This represents an increase of 150 billion yuan over the previous year.

This week, China announced this week that the phased free preschool education policy will cover all children in their final year of kindergartens, saving families 20 billion yuan. Childcare subsidies unveiled in July amount to 90 billion yuan. 

As Joe Biden repeated over the years,

Don’t tell me what you value. Show me your budget, and I’ll tell you what you value.

The National Development and Reform Commission said last month:

In 2025, a total of 800 billion yuan has been allocated for the “two major undertakings,” supporting 1,459 projects in key areas such as ecological restoration in the Yangtze River Basin, major transportation infrastructure along the Yangtze River, the New Western Land–Sea Corridor, high-standard farmland, major water conservancy projects, urban underground pipeline networks, the “Three-North” shelterbelt program, and the renovation of hospital wards.

Now that the 2025 money has been spent by July and China is drawing up its next Five-Year Plan for 2026-2030, will there be more such projects in the future?

In a column for the state-run China News Service this week, Dong Yu, previously Deputy Director-General of the Second Economic Bureau of the Office of the Central Financial and Economic Affairs Commission and, before that, an official at China’s National Development and Reform Commission (NDRC), pointedly said,

In the next step, during the formulation and implementation of the 15th Five-Year Plan, the “two major undertakings” will continue to occupy an important place, be organically incorporated into the new five-year plan, and form close alignment and sustained momentum with major national strategies, major plans, major projects, and key initiatives…

…Such a major strategy will be pursued with persistence—it will not remain rhetorical, nor will it be reversed abruptly.

He did not cite a source of information in his article.

Continuing with his lecturing style, Dong, now Executive Vice Director of China Institute for Development Planning, Tsinghua University, rebuked some unspecified market analysis that had observed the investments just were a one-time boost shot.

Some market institutions once analyzed that when China’s economy was facing short-term difficulties and challenges, the launch of the “two major undertakings” was mainly aimed at expanding investment in the short term to stabilize growth. Such a view clearly lacks a professional understanding of the decision-making intentions and logic, fails to properly grasp the relationship between the short term and the medium-to-long term, as well as between objectives and means, and inverts the proper order of priorities—a misconception that needs to be pointed out and corrected.

Dong also highlighted what he said was the unusual nature of the “strategic move,” including that central government debts fueled the investments, and they were selected “top-down,” rather than primarily relying on local government proposal or input.

The two undertakings were formally submitted for deliberation at the 2024 National People’s Congress after the central leadership made its decision and arrangements…

The central authorities have shown firm determination in this work, adopting the ultra-long-term special treasury bond—a macro policy tool that has rarely been used. Compared with several past issuances of special treasury bonds, the funding arrangement for the “two major undertakings” spans a longer cycle, has a broader scope of application, and will continue to advance in the next stage. It can be said that the scale and intensity are unprecedented. In 2024, a total of 700 billion yuan in ultra-long-term special treasury bonds was allocated, and in 2025, the figure is 800 billion yuan, all of which have now been fully disbursed.

The organization of the “two major undertakings” construction is top-down, completely different from the past practice in the investment sector where projects were determined through bottom-up applications. The purpose is to facilitate the smoother downward transmission of the needs of major national strategies. Relevant [central] government departments, by identifying shortcomings and weaknesses, specifying key areas, and refining project requirements, have ensured that the project list is no longer a collection of fragmented local items. Instead, projects are planned in an integrated manner by category and sector, with strengthened guidance for key regions, more targeted measures, and clearer standards.

Although an exhaustive list of the 1,459 projects does not appear to be available to the public, the “security capacity” build-up in the two major undertakings should be understood in broad terms, and Dong claims the investments put China on a sounder footing globally now that Donald Trump rules America again.

In recent years, the central authorities have emphasized security awareness and bottom-line thinking in development planning, a shift closely related to changes in the international situation. The closer China’s economy becomes intertwined with the global economy, the more comprehensive its considerations must be regarding issues such as food security, energy security, industrial security, and ecological security. The second “undertaking” in the “two major undertakings”—the strengthening of security capabilities in key areas—is precisely a forward-looking arrangement. The dramatic changes in the international environment since the beginning of 2025 have further underscored and confirmed the necessity of enhancing security capabilities, fully demonstrating that the central authorities’ thinking and deployment have been prescient and ahead of the curve.

Dong’s article via China News Service is fully translated below.

中央这一先手棋很不寻常

This Strategic First Move by the Central Authorities Is Highly Unusual

by Dong Yu, Executive Vice President, Institute for China Development Planning, Tsinghua University

The issuance of ultra-long-term special treasury bonds to support the implementation of major national strategies and the building of security capacities in key areas (hereinafter referred to as the “two major undertakings”) has become one of the hottest topics in China’s economy in recent years. Any observation of China’s present and future economic trajectory must include research and analysis of these two undertakings. More than a year has passed since the initiative was launched, making it both necessary and timely to evaluate its effectiveness, understand its operating mechanisms, and look ahead to its prospects.

The “Two Major Undertakings” Are by No Means Ordinary Policy Measures

In terms of decision-making background and process, as well as policy intensity and scope, the launch and implementation of the two major undertakings stand out from other policies. They represent a top-level design initiative.

Understanding a policy starts with its background. From the sequence of events leading to the proposal, this was a proactive, historic choice. The two undertakings were formally submitted for deliberation at the 2024 National People’s Congress after the central leadership made its decision and arrangements. The timing was significant: the 20th Communist Party of China National Congress had laid out a series of major long- and medium-term strategic initiatives that needed concrete engineering projects to push forward. China was midway through two Five-Year Plans, yet strategic advancement could not wait. The central leadership thus introduced the two major undertakings as a groundbreaking initiative.

Strategically, the undertakings directly address the needs of advancing long-term objectives. From the outset, they have been aimed squarely at the goals of Chinese modernization. By breaking down these goals into specific tasks and identifying the most difficult bottlenecks, the undertakings found their points of focus. Some of these tasks might take decades for other countries to achieve, but China has chosen not to delay—tackling them head-on at the starting stage of the new journey toward modernization. This model is uniquely Chinese and has been proven by history to be a key factor in China’s remarkable development successes.

The undertakings are also highly forward-looking—a “first move” by the central leadership. In recent years, national development planning has placed greater emphasis on security and on guarding the bottom line, in response to changes in the international environment. The closer China’s economy is linked to the global economy, the more comprehensive its considerations must be on food security, energy security, industrial security, and ecological security, and other issues. The second “major” in the initiative—security capacity building in key areas—is an arrangement made in anticipation of future challenges. The sharp changes in the international environment since 2025 have only highlighted and validated the necessity of strengthening security capacities, demonstrating that the central leadership’s thinking and arrangements were ahead of the curve.

The undertakings also have a strong overall and systemic quality, constituting a key move in macroeconomic governance. They focus on areas of outstanding importance to economic and social development and have a high degree of relevance to the overall development landscape. The policy toolkit they employ integrates investment, fiscal, science and technology, education, social, and ecological policies. This comprehensive package embodies the use of systems thinking to drive development and will significantly impact all aspects of the economy and society.

A Manifestation of Central Will

Extraordinary measures are for extraordinary tasks. The strategic objectives of Chinese modernization are long-term undertakings, and the two major undertakings provide the foundational support through systematic design and substantial funding.

The central leadership has committed to this initiative by adopting the rarely used macroeconomic tool of ultra-long-term special treasury bonds. Compared with previous special bond issuances, the funding for the two undertakings spans a longer cycle and serves a wider range of purposes, with plans for continued implementation. In both scale and intensity, this is unprecedented: 700 billion yuan in 2024 and 800 billion yuan in 2025, all of which has already been allocated.

In terms of priorities, it vividly reflects the principle of “concentrating resources to accomplish major undertakings.” The focus areas include urban–rural integration, regional coordination, high-quality population development, food security, energy and resource security, ecological security, and self-reliance and strength in science and technology—all crucial to building a strong nation and achieving national rejuvenation. These require coordinated planning and advancement. In just over a year, the high-level requirements have been translated into batches of concrete projects, reflecting the efficiency of implementation.

Project selection is guided by the principle that only the central government can resolve these issues. Some involve urgent development bottlenecks with significant obstacles that cannot be overcome by conventional means, such as scientific and technological breakthroughs, high-standard farmland construction, and upgrading the quality of higher education. Others are long-desired but previously unachievable projects that lack local willingness or capacity to implement, such as major cross-regional infrastructure, cross-basin wastewater treatment, and urban underground utility upgrades.

The organization of the “two major undertakings” construction is top-down, completely different from the past practice in the investment sector where projects were determined through bottom-up applications. The purpose is to facilitate the smoother downward transmission of the needs of major national strategies. Relevant [central] government departments, by identifying shortcomings and weaknesses, specifying key areas, and refining project requirements, have ensured that the project list is no longer a collection of fragmented local items. Instead, projects are planned in an integrated manner by category and sector, with strengthened guidance for key regions, more targeted measures, and clearer standards.

A Combination of “Hard” and “Soft” Measures

From the start, the undertakings were designed not only to fund “hard” engineering projects but also to include comprehensive arrangements for “soft” institutional and policy measures—an important innovation.

The emphasis on soft measures is pragmatic. Given the high importance and public nature of the projects, long-term mechanisms must be designed to ensure smooth progress during construction and sustainable operation thereafter. This includes drafting specialized plans to provide strategic guidance, introducing targeted policies to improve funding efficiency, and innovating institutional arrangements to safeguard implementation.

The implementation process is thus also a process of improving the investment and financing system, updating project management approaches, and enhancing investment effectiveness. In some sectors, soft-measure experiments have had positive impacts, creating healthy interaction with hard investments.

For example, the healthy operation of urban underground pipelines depends on sound maintenance mechanisms. Some local governments have attracted long-term institutional funds into major pipeline projects through debt or equity investment plans, stabilizing private sector returns via operational rights, government subsidies, and tax incentives. Others have introduced province-wide upstream–downstream gas price linkage, set reasonable water supply return rates based on market profits, and advanced the marketization of gas and water prices—reducing losses for public utilities and encouraging private investment.

Similarly, in the quality undergraduate expansion program, mechanisms play a guiding role: schools effectively implementing expansion plans receive increased support, while those performing poorly see reduced support; universities without expanded undergraduate admission plans are generally excluded from special bond funding. Disciplines and programs are adjusted dynamically to align talent training with economic and societal needs.

Directly Relevant to Everyone

The nature of the undertakings is not determined by project size but by their strategic objectives and significance. As long as they align with major national strategies, they are included—whether as large standalone projects, such as high-speed rail along the Yangtze River, or as “project packages,” such as Yangtze River wastewater treatment composed of multiple treatment facilities. This flexible, problem-oriented approach allows better alignment with public needs.

As projects break ground and enter operation, their benefits to people’s livelihoods will become increasingly evident. Observers should not see the undertakings as distant from daily life; they will bring tangible improvements to everyone’s quality of life.

For example:

  • Urban underground pipelines: Upgrades to gas, water, and heating systems will greatly improve safety and resilience. Renovation of old gas pipelines is nearing completion, reducing accident rates by over 30%. Eliminating hidden risks in unseen places increases residents’ sense of security.
  • Food security: Gradually converting all permanent basic farmland into high-standard farmland will stabilize grain output and enhance food safety. Higher standards mean safer products, so people will eat with greater confidence.
  • Yangtze River protection: Building or upgrading over 60,000 kilometers of sewage pipelines in the Yangtze Economic Belt will greatly improve the river’s ecological environment and resolve long-standing public concerns.
  • Transportation: Creating the shortest Shanghai–Chengdu high-speed rail corridor (approx. 1,900 km) will connect the Yangtze River Delta, the middle Yangtze region, and the Chengdu–Chongqing area more quickly, cutting travel time nearly in half and boosting east–west connectivity.
  • Ecological security: Implementing the “Three-North” shelterbelt project over 130 million mu (93 million hectares), with good survival rates for trees, shrubs, and grasses, will safeguard northern ecological security and create new income opportunities.
  • Higher education: “Double First-Class” universities will see markedly improved conditions, with over 500,000 new standard dorm beds. Quality undergraduate enrollment will rise by 16,000 in 2024 and over 20,000 in 2025, giving more students access to quality education and ensuring basic living needs for those from low-income families.
A Bold Stroke in the History of Development

The two major undertakings are a major decision by the CPC Central Committee and the State Council, aimed at the overall strategy of building a strong country and achieving national rejuvenation. They play an irreplaceable role in advancing Chinese modernization.

They are not short-term measures but focus on medium- to long-term development. Some market institutions once analyzed that when China’s economy was facing short-term difficulties and challenges, the launch of the “two major undertakings” was mainly aimed at expanding investment in the short term to stabilize growth. Such a view clearly lacks a professional understanding of the decision-making intentions and logic, fails to properly grasp the relationship between the short term and the medium-to-long term, as well as between objectives and means, and inverts the proper order of priorities — a misconception that needs to be pointed out and corrected.

Since implementation began, the undertakings have provided important support for economic stability. Although their starting point was not short-term growth, the resulting investment has boosted employment and consumption, helping to expand domestic demand and stabilize growth. In the next step, during the formulation and implementation of the 15th Five-Year Plan, the “two major undertakings” will continue to occupy an important place, be organically incorporated into the new five-year plan, and form close alignment and sustained momentum with major national strategies, major plans, major projects, and key initiatives.

They will also bolster the country’s core competitiveness. As foundational support for Chinese modernization, they will strengthen factor security and resolve long-term bottlenecks, with far-reaching significance for shaping China’s development prospects. In an era of intensifying major-power competition, they will provide stable expectations and significantly enhance China’s capacity to manage international uncertainty. Such a major strategy will be pursued with persistence—it will not remain rhetorical, nor will it be reversed abruptly.

Though implementation has only recently begun, the undertakings’ historic role will continue to grow over time. In the future, looking back, they will surely stand as an important part of the “China story” and leave a bold stroke in the history of the People’s Republic’s development.

World-Watching: Minutes of the Monetary Policy Committee — Copom

272nd Meeting – July 29-30, 2025

[from the Central Bank of Brazil, 5 August, 2025]

  1. Update of the economic outlook and the Copom’s scenario1
    1. The global environment is more adverse and uncertain due to the economic policy and economic outlook in the United States, mainly regarding its trade and fiscal policies and their effects.
    2. Therefore, the behavior and the volatility of different asset classes have been impacted, altering global financial conditions. This scenario requires particular caution from emerging market economies amid heightened geopolitical tensions.
    3. Regarding the domestic scenario, the set of indicators on economic activity has shown some moderation in growth, as expected, but the labor market is still showing strength.
    4. In recent releases, headline inflation and measures of underlying inflation remained above the inflation target. Inflation expectations for 2025 and 2026 collected by the Focus survey remained above the inflation target and stand at 5.1% and 4.4%, respectively.
  2. Scenarios and risk analysis
    1. The inflation outlook remains challenging in several dimensions. Copom assessed the international scenario, economic activity, aggregate demand, inflation expectations, and current inflation. Copom then discussed inflation projections and expectations before deliberating on the current decision and future communication.
    2. The global environment is more adverse and uncertain. If, on the one hand, the approval of certain trade agreements, along with recent inflation and economic activity data from the U.S., could suggest a reduction in global uncertainty, on the other hand, the U.S. fiscal policy—and, particularly for Brazil, the U.S. trade policy—make the outlook more uncertain and adverse. The increase of trade tariffs by the U.S. to Brazil has significant sectoral impacts and still uncertain aggregate effects that depend on the unfolding of the next steps in the negotiations and the perception of risk inherent to this process. The Committee is closely monitoring the potential impacts on the real economy and financial assets. The prevailing assessment within the Committee is the increased global outlook uncertainty, and, therefore, Copom should maintain a cautious stance. As usual, the Committee will focus on the transmission mechanisms from the external environment to the domestic inflation dynamics and their impact on the outlook.
    3. The domestic economic activity outlook has indicated a certain moderation in growth, while also presenting mixed data across sectors and indicators.
    4. Overall, some moderation in growth is observed, supporting the scenario outlined by the Committee. This moderation, necessary for the widening of the output gap and the convergence of inflation to the target, is aligned with a contractionary monetary policy. Monthly sectoral surveys and more timely consumption data support a gradual slowdown in growth.
    5. At turning points in the economic cycle, it is natural to observe mixed signals from economic indicators—some leading, others lagging—as well as from comparisons between markets, such as the credit and labor markets.
    6. The credit market, which is more sensitive to financial conditions, has shown clearer moderation. A decline in non-earmarked credit granting and an increase in interest and delinquency rates have been observed. Moreover, regarding household credit, there has been an increase in the household debt–service ratio and a deepening of the negative credit flow—that is, households repaying more debt than taking on. It was emphasized during the discussion that some recent measures, such as private payroll-deducted loans, have had less impact than many market participants expected. Given the implementation agenda in this credit line, as well as the effects of introducing and removing taxes on other credit modalities, the Committee believes it should closely monitor upcoming credit data releases.
    7. In contrast to the credit market, the labor market remains dynamic. Both from the perspective of income—with real gains consistently above productivity—and employment—with a significant decrease in the unemployment rate to historically low levels—the labor market has greatly supported consumption and income.
    8. Thus, the Committee assesses that the signals from demand and economic activity so far suggest that the scenario is unfolding as expected and is consistent with the current monetary policy. The Committee reiterates that the aggregate demand slowdown is an essential element of supply–demand rebalancing in the economy and convergence of inflation to the target.
    9. Fiscal policy has a short-term impact, mainly through stimulating aggregate demand, and a more structural dimension, which has the potential to affect perceptions of debt sustainability and influence the term premium in the yield curve. A fiscal policy that acts counter-cyclically and contributes to reducing the risk premium favors the convergence of inflation to the target. Copom reinforced its view that the slowdown in structural reform efforts and fiscal discipline, the increase in earmarked credit, and uncertainties over the public debt stabilization have the potential to raise the economy’s neutral interest rate, with deleterious impacts on the power of monetary policy and, consequently, on the cost of disinflation in terms of activity. The Committee remained firmly convinced that policies must be predictable, credible, and countercyclical. In particular, the Committee’s discussion once again highlighted the need for harmonious fiscal and monetary policy.
    10. Inflation expectations, as measured by different instruments and obtained from various groups of agents, remained above the inflation target at all horizons, maintaining the adverse inflation outlook. For shorter-term horizons, following the release of the most recent data, there has been a decline in inflation expectations. For longer-term horizons, conversely, there has been no significant change in inflation expectations between Copom meetings, even though measures of breakeven inflation extracted from financial assets have declined. The Committee reaffirmed and renewed its commitment to re-anchoring expectations and to conducting a monetary policy that supports such a movement.
    11. De-anchored inflation expectations is a factor of discomfort shared by all Committee members and must be tamed. Copom highlighted that environments with de-anchored expectations increase the disinflation cost in terms of activity. The scenario of inflation convergence to the target becomes more challenging with de-anchored expectations for longer horizons. When discussing this topic, the main conclusion obtained and shared by all members of Copom was that, in an environment of de-anchored expectations—as currently is the case—greater monetary restriction is required for a longer period than would be otherwise appropriate.
    12. The inflation scenario has continued to show downside surprises in recent periods compared with analysts’ forecasts, but inflation has remained above the target Industrial goods inflation, which has already been showing weaker wholesale price pressures, continued to ease in the more recent period. Food prices also displayed slightly weaker-than-expected dynamics. Finally, services inflation, which has greater inertia, remains above the level required to meet the inflation target, in a context of a positive output gap. Beyond the changes in items, or even short-term oscillations, the core inflation measures have remained above the value consistent with the target achievement for months, corroborating the interpretation that inflation is pressured by demand and requires a contractionary monetary policy for a very prolonged period.
    13. Copom then addressed the projections. In the reference scenario, the interest rate path is extracted from the Focus survey, and the exchange rate starts at USD/BRL 5.552 and evolves according to the purchasing power parity (PPP). The Committee assumes that oil prices follow approximately the futures market curve for the following six months and then start increasing 2% per year onwards. Moreover, the energy tariff flag is assumed to be “green” in December of the years 2025 and 2026.
    14. In the reference scenario, four-quarter inflation projections for 2025 and for 2026 are 4.9% and 3.6%, respectively (Table 1). For the relevant horizon for monetary policy—2027 Q1—the inflation projection based on the reference scenario extracted from the Focus survey remained at 3.4%, above the inflation target.
    15. Regarding the balance of risks, it was assessed that the scenario of greater uncertainty continues to present higher-than-usual upside and downside inflation risks to the inflation outlook. Copom assessed that, among the upside risks for the inflation outlook and inflation expectations, it should be emphasized (i) a more prolonged period of de-anchoring of inflation expectations; (ii) a stronger-than-expected resilience of services inflation due to a more positive output gap; and (iii) a conjunction of internal and external economic policies with a stronger-than-expected inflationary impact, for example, through a persistently more depreciated currency. Among the downside risks, it should be noted (i) a greater-than-projected deceleration of domestic economic activity, impacting the inflation scenario; (ii) a steeper global slowdown stemming from the trade shock and the scenario of heightened uncertainty; and (iii) a reduction in commodity prices with disinflationary effects.
    16. Prospectively, the Committee will continue monitoring the pace of economic activity, which is a fundamental driver of inflation, particularly services inflation; the exchange rate pass-through to inflation, after a process of increased exchange rate volatility; and inflation expectations, which remain de-anchored and are drivers of future inflation behavior. It was emphasized that inflationary vectors remain adverse, such as the economic activity resilience and labor market pressures, de-anchored inflation expectations, and high inflation projections. This scenario prescribes a significantly contractionary monetary policy for a very prolonged period to ensure the convergence of inflation to the target.
  3. Discussion of the conduct of monetary policy
    1. Copom then discussed the conduct of monetary policy, considering the set of projections evaluated, as well as the balance of risks for prospective inflation.
    2. Following a swift and firm interest rate hike cycle, the Committee anticipates, as its monetary policy strategy, continuity of the interruption of the rate hiking cycle to observe the effects of the cycle already implemented. It was emphasized that, once the appropriate interest rate is determined, it should remain at a significantly contractionary level for a very prolonged period due to de-anchored expectations. The Committee emphasizes that it will remain vigilant, that future monetary policy steps can be adjusted and that it will not hesitate to proceed with the rate hiking cycle if appropriate.
  4. Monetary policy decision
    1. The Committee has been closely monitoring with particular attention the announcements regarding the imposition by the U.S. of trade tariffs on Brazil, reinforcing its cautious stance in a scenario of heightened uncertainty. Moreover, it continues to monitor how the developments on the fiscal side impact monetary policy and financial assets. The current scenario continues to be marked by de-anchored inflation expectations, high inflation projections, resilience on economic activity, and labor market pressures. Ensuring the convergence of inflation to the target in an environment with de-anchored expectations requires a significantly contractionary monetary policy for a very prolonged period.
    2. Copom decided to maintain the Selic rate at 15.00% p.a., and judges that this decision is consistent with the strategy for inflation convergence to a level around its target throughout the relevant horizon for monetary policy. Without compromising its fundamental objective of ensuring price stability, this decision also implies smoothing economic fluctuations and fostering full employment.
    3. The current scenario, marked by heightened uncertainty, requires a cautious stance in monetary policy. If the expected scenario materializes, the Committee foresees a continuation of the interruption of the rate hiking cycle to examine its yet-to-be-seen cumulative impacts, and then evaluate whether the current interest rate level, assuming it stable for a very prolonged period, will be enough to ensure the convergence of inflation to the target. The Committee emphasizes that it will remain vigilant, that future monetary policy steps can be adjusted and that it will not hesitate to resume the rate hiking cycle if appropriate.
    4. The following members of the Committee voted for this decision: Gabriel Muricca Galípolo (Governor), Ailton de Aquino Santos, Diogo Abry Guillen, Gilneu Francisco Astolfi Vivan, Izabela Moreira Correa, Nilton José Schneider David, Paulo Picchetti, Renato Dias de Brito Gomes, and Rodrigo Alves Teixeira.
Table 1

Inflation projections in the reference scenario
Year-over-year IPCA change (%)

Price Index202520262027 Q1
IPCA4.93.63.4
IPCA market prices5.13.53.3
IPCA administered prices4.44.03.9
Footnotes

1 Unless explicitly stated otherwise, this update considers changes since the June Copom meeting (271st meeting).

2 It corresponds to the rounded value of the average exchange rate observed over the ten working days ending on the last day of the week prior to the Copom meeting, according to the procedure adopted since the 258th meeting.

Meeting information
Date: July 29-30 2025
Place: BCB Headquarters’ meeting rooms on the 8th floor (7/29 and 7/30 on the morning) and 20th floor (7/30 on the afternoon) – Brasilia – DF – Brazil
Starting and ending times:
July 29: 10:07 AM – 11:37 AM; 2:17 PM – 5:51 PM
July 30: 10:10 AM – 11:13 AM; 2:37PM – 6:34 PM
In attendance:
Members of the Copom
Gabriel Muricca Galípolo – Governor
Ailton de Aquino Santos
Diogo Abry Guillen
Gilneu Francisco Astolfi Vivan
Izabela Moreira Correa
Nilton José Schneider David
Paulo Picchetti
Renato Dias de Brito Gomes
Rodrigo Alves Teixeira
Department Heads in charge of technical presentations (attending on July 29 and on the morning of July 30)
André de Oliveira AmanteOpen Market Operations Department
Euler Pereira Gonçalves de MelloResearch Department (also attending on the afternoon of 7/30)
Fábio Martins Trajano de ArrudaDepartment of Banking Operations and Payments System
Luís Guilherme Siciliano PontesInternational Reserves Department
Marcelo Antonio Thomaz de AragãoDepartment of International Affairs
Ricardo SabbadiniDepartment of Economics
Other participants (attending on July 29 and on the morning of July 30)
Alexandre de CarvalhoOffice of Economic Advisor
André Maurício Trindade da RochaHead of the Financial System Monitoring Department
Angelo Jose Mont Alverne DuarteHead of Office of the Deputy Governor for Licensing and Resolution (attending on the mornings of 7/29 and 7/30)
Arnaldo José Giongo GalvãoPress Office Advisor
Cristiano de Oliveira Lopes CozerGeneral Counsel
Edson Broxado de França TeixeiraHead of Office of the Deputy Governor for Supervision
Eduardo José Araújo LimaHead of Office of the Deputy Governor for Economic Policy
Fernando Alberto G. Sampaio C. RochaHead of the Department of Statistics
Isabela Ribeiro Damaso MaiaHead of the Sustainability and International Portfolio Investors Unit (attending on the mornings of 7/29 and 7/30)
Julio Cesar Costa PintoHead of Office of the Governor
Laura Soledad Cutruffo CompariniDeputy Head of the Department of Economics
Leonardo Martins NogueiraHead of Office of the Deputy Governor for Monetary Policy
Marcos Ribeiro de CastroDeputy Head of the Research Department
Mardilson Fernandes QueirozHead of the Financial System Regulation Department
Olavo Lins Romano PereiraDeputy Head of the Department of International Affairs
Renata Modesto BarretoDeputy Head of the Department of Banking Operations and Payments System
Ricardo da Costa MartinelliDeputy Head of the International Reserves Department
Ricardo Eyer HarrisHead of Office of the Deputy Governor for Regulation
Ricardo Franco MouraHead of the Prudential and Foreign Exchange Regulation Department
Rogerio Antonio LuccaExecutive Secretary
Simone Miranda BurelloAdvisor in the Office of the Deputy Governor for Monetary Policy

The members of Copom analyzed the recent performance and prospects for the Brazilian and international economies, under the monetary policy framework, whose objective is to comply with the inflation targets established by the National Monetary Council. This document represents Copom’s best effort to provide an English version of its policy meeting minutes. In case of inconsistency, the Portuguese version prevails.

World-Watching: India: Building an Export-Oriented Apparel Sector

[from ICRIER, 28 July, 2025]

The Kotak-ICRIER Centre of Excellence for Agriculture Policy, Sustainability, and Innovations (KICEAPSI) is delighted to present its Agri-Food Trends and Analytics Bulletin (AF-TAB), Volume 5, Issue 1, on “Building an Export-oriented Apparel Sector.” [archived PDF] Amidst an evolving geopolitical landscape and shifting global trade patterns, India’s textiles and apparel (T&A) sector stands at a crucial juncture. The country has a rich cultural heritage in textiles and is one of the few nations with the entire T&A value chain, yet its export share in apparel market remains low and stagnant over the last two decades, at least. With China gradually vacating the export market space and global buyers looking to diversify sourcing, India must act swiftly.

This AF-TAB issue explores this window of opportunity through three interesting articles. The first article, ‘India’s Apparel Sector and the Window of Opportunity’, examines India’s stagnant export performance and the structural constraints that have prevented it from capturing a larger global share. It highlights how fragmentation, poor logistics, and high input costs weigh the sector down, despite strong domestic potential. The second article, ‘Missing the Closet: Is India Exporting What the World Wears?’ analyses India’s export basket against global demand trends. It reveals a mismatch between what India produces–largely cotton-based basics and what the global markets demand—man-made fibres (MMF)-based, fashion-forward garments. This misalignment is most visible in key markets like the U.S. and EU. The third article, ‘PM MITRA Parks—Can They Lift Apparel Exports?’, evaluates the government’s flagship scheme designed to address these inefficiencies. While PM MITRA is a much-needed step to create scale, plug-and-play infrastructure, and attract investment, its success depends on timely execution, policy alignment, and strategic targeting.

Read the bulletin [archived PDF].

Economics-Watching: Kuwait: GDP Returns to Growth in Q1 2025 as Impact of Oil Output Cuts Fades

[from NBK Economic Research, 21 July, 2025]

by Mohammad Al-Shehri, Assistant Economist & Omar Al-Nakib, Head of MENA Research

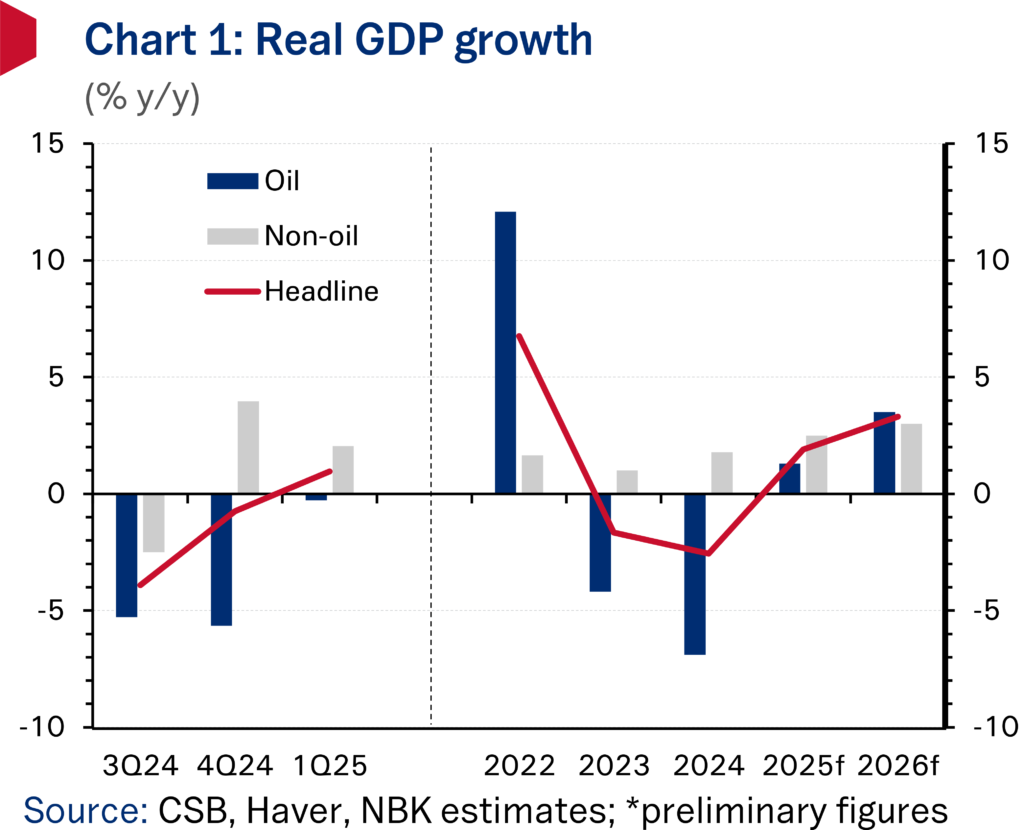
Preliminary official figures show GDP expanding 1% y/y in Q1 2025 following seven consecutive quarters of contraction, helped by a less severe downturn in oil output. With the negative effects of earlier voluntary oil production cuts beginning to fade, oil GDP recorded only a marginal decline, the softest since Q2 2023. Growth in non-oil activity remained positive though eased, weighed by a moderation in the manufacturing, real estate, and transport sectors. The near-term outlook for GDP is one of positive growth, lifted by rising oil production after Kuwait started to restore 135 kb/d of oil output cuts between April and September 2025, while the non-oil sector should also register further steady gains.

Non-oil GDP growth softens in Q1 2025 after strong performance in Q4 2024

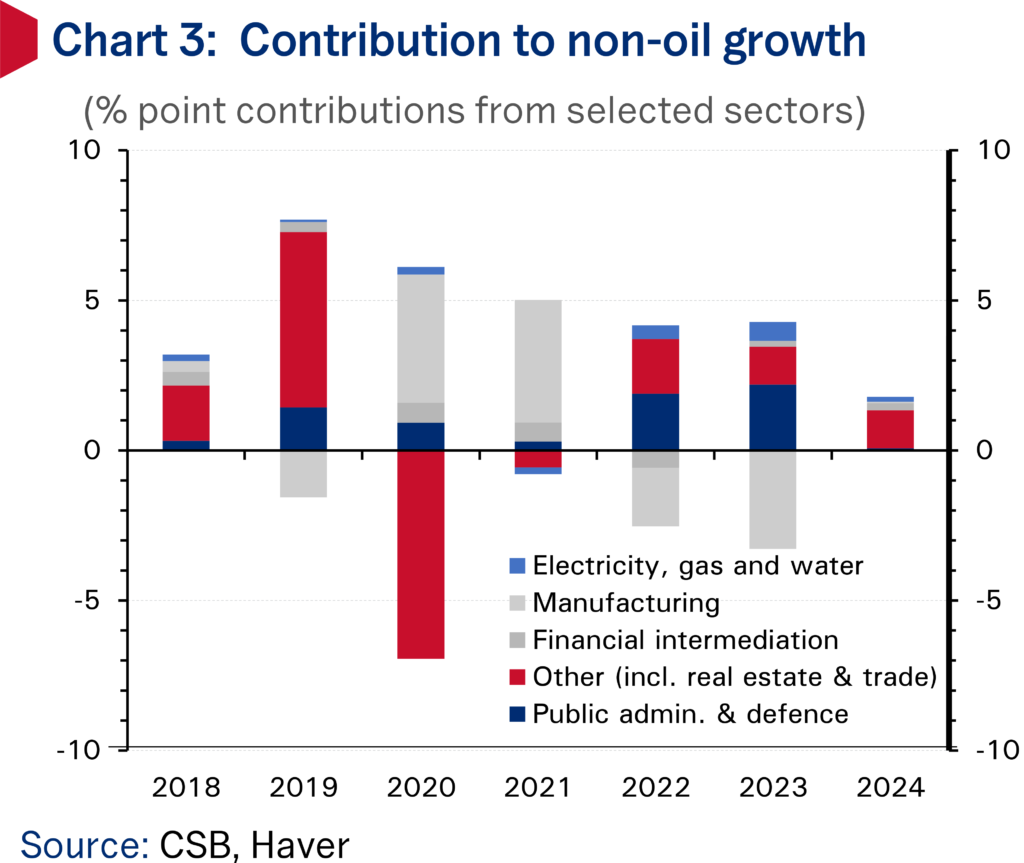
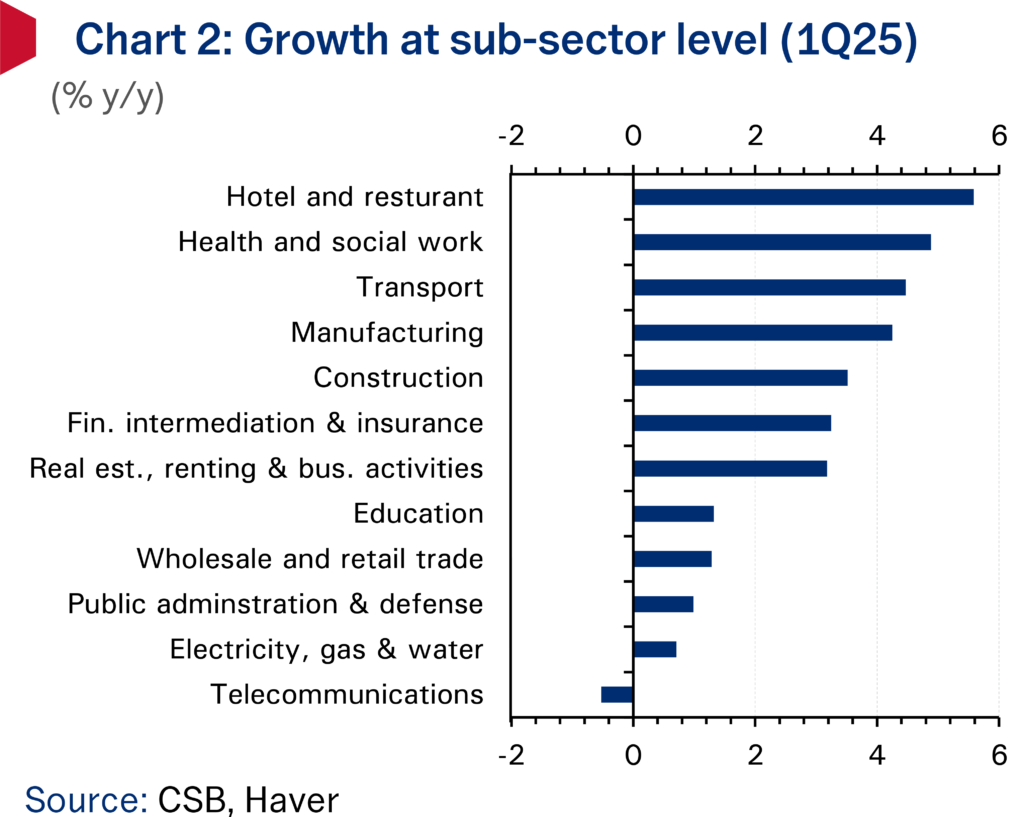
Growth in the non-oil sector weakened in Q1 2025, slowing to 2% y/y compared to 4% recorded in the prior quarter. (Chart 1.) The softer expansion in non-oil activity reflected, among other things, a moderation in the manufacturing sector, where activity grew at a still-solid 4.3% despite a decline in refined petroleum products output but slowed notably from the 12.2% reading registered in Q4 2024. Growth in other sectors including real estate, wholesale & retail trade, transport, and education also slowed. Offsetting the slowdown was stronger expansion in the non-oil economy’s largest segments: public administration and defense as well as financial intermediation and insurance, which grew 1% and 3.2% y/y, respectively. (Chart 2.)

Chart 1: Real GDP growth

Chart 2: Growth at sub-sector level (1Q25)

Oil sector logs marginal contraction, set to return to growth in Q2

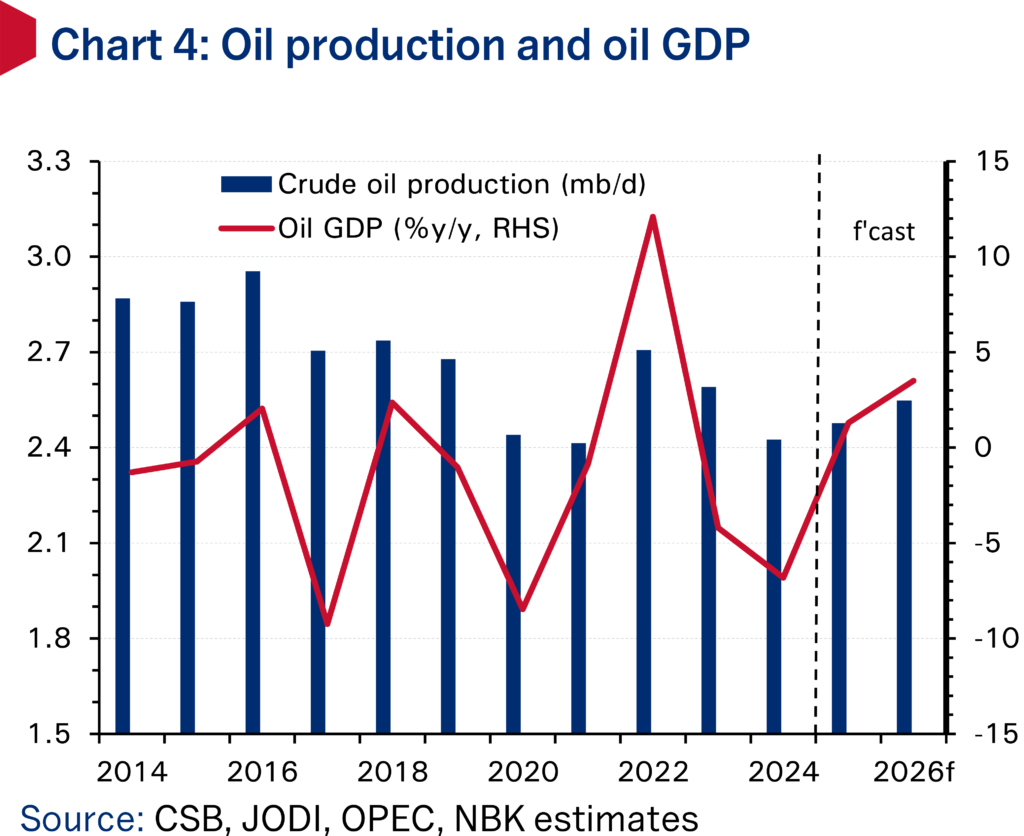
The contraction in oil GDP eased significantly to -0.3% y/y from -5.7% y/y in Q4 2024, registering the softest rate of decline since Kuwait embarked on cutting oil production in Q2 2023 after participating in the voluntary cuts scheme with 7 other OPEC+ members. (Chart 4.) Kuwait’s oil production averaged 2.415 mb/d in Q1 2025, a 0.7% decline from the same quarter last year, according to OPEC secondary sources. However, oil sector fortunes are set to shift in Q2 2025 and thereafter, after the OPEC-8 member alliance started unwinding the 2.2 mb/d voluntary cut tranche in April 2025. Originally planned to be unwound over the course of 18 months, OPEC+ has accelerated the pace of supply hikes with output now on a path to be fully restored in September, a full year ahead of schedule. For Kuwait, crude production rose by 0.5% q/q in Q2 to 2.426 mb/d and is set to accelerate further to average 2.533 mb/d in H2 2025. With the oil market so far able to absorb the additional OPEC and global supply and oil prices currently holding near $70/bbl, an upside risk to our oil sector outlook involves the potential unwinding of the outstanding OPEC-8 voluntary cuts (1.66 mb/d), of which Kuwait’s share is 128 kb/d.

Growth heading back into positive territory in 2025

Growth in total GDP is set to remain on a positive trajectory in the near term, buoyed by further steady expansion in non-oil economic activity and increased oil production. Non-oil GDP is set to benefit from the government’s reform drive which includes the recent passing of the debt law that could catalyze the implementation of key development projects and the potential approval of the ‘mortgage’ law later in 2025, which could spur higher household borrowing and consumer spending. Economic indicators for Q2 2025 pointed to a healthy pace of non-oil economic activity. The key ‘output’ and ‘new orders’ balances in the non-oil private sector PMI gauge both averaged a very robust 57+ in Q2 2025, real estate activity continued to expand at a robust pace with earlier price falls in the residential sector abating, while credit growth stood at a healthy 5.5% y/y in May, and could benefit in coming months if interest rates are reduced further.

Nonetheless, there are also downside risks to the outlook. Local consumer spending growth (according to central bank card transactions data) turned negative in Q1 2025, extending the weakening trend now observed for more than a year. The government’s ongoing fiscal consolidation push will also weigh on wage and job growth. Overall, we see GDP growing 1.9% this year, boosted by expansions in both the oil and non-oil sectors of 1.2% and 2.5%, respectively.

Chart 3: Contribution to non-oil growth

Chart 4: Oil production and oil GDP

Read this article as an archived PDF.

Economics-Watching: Multivariate Core Trend Inflation

[from the Federal Reserve Bank of New York]

Overview

The Multivariate Core Trend (MCT) model measures inflation’s persistence in the seventeen core sectors of the personal consumption expenditures (PCE) price index.

Whether inflation is short-lived or persistent, concentrated in a few sectors or broad-based, is of deep relevance to policymakers. We estimate a dynamic factor model on monthly data for the major sectors of the personal consumption expenditures (PCE) price index to assess the extent of inflation persistence and its broadness. The results give a measure of trend inflation and shed light on whether inflation dynamics are dominated by a trend common across sectors or are sector-specific.

The New York Fed updates the MCT estimates and share sectoral insights at or shortly after 2 p.m. on the first Monday after the release of personal consumption expenditures (PCE) price index data from the Bureau of Economic Analysis. Data are available for download.

September 2023 Update

  • Multivariate Core Trend (MCT) inflation was 2.9 percent in September, a 0.3 percentage point increase from August (which was revised up from 2.5 percent). The 68 percent probability band is (2.4, 3.3).
  • Services ex-housing accounted for 0.54 percentage point (ppt) of the increase in the MCT estimate relative to its pre-pandemic average, while housing accounted for 0.50 ppt. Core goods had the smallest contribution, 0.03 ppt.
  • A large part of the persistence in housing and services ex-housing is explained by the sector-specific component of the trend.

Latest Release: 2:00 p.m. ET October 31, 2023

View the Multivariate Core Trend of PCE Inflation data here.

Frequently Asked Questions

What is the goal of the Multivariate Core Trend (MCT) analysis?

The New York Fed aims to provide a measure of inflation’s trend, or “persistence,” and identify where the persistence is coming from.

What data are reported?

The New York Fed’s interactive charts report monthly MCT estimates from 1960 to the present. The New York Fed also provides estimates of how much three broad sectors (core goods, core services excluding housing, and housing) are contributing to overall trend inflation over the same time span. The New York Fed further distinguishes whether the persistence owes to common or sector-specific components. Data are available for download.

What is the release schedule?

The New York Fed updates the estimate of inflation persistence and share sectoral insights following the release of PCE price data from the U.S. Bureau of Economic Analysis each month.

What is the modeling strategy?

A dynamic factor model with time-varying parameters is estimated on monthly data for the seventeen major sectors of the PCE price index. The model decomposes each sector’s inflation as the sum of a common trend, a sector-specific trend, a common transitory shock, and a sector-specific transitory shock. The trend in PCE inflation is constructed as the sum of the common and the sector-specific trends weighted by the expenditure shares.

The New York Fed uses data from all seventeen of the PCE’s sectors; however, in constructing the trend in PCE inflation, we exclude the volatile non-core sectors (that is, food and energy). The approach builds on Stock and Watson’s 2016 “Core Inflation and Trend Inflation.”

How does the MCT measure differ from the core personal consumption expenditures (PCE) inflation measure?

The core inflation measure simply removes the volatile food and energy components. The MCT model seeks to further remove the transitory variation from the core sectoral inflation rates. This has been key in understanding inflation developments in recent years because, during the pandemic, many core sectors (motor vehicles and furniture, for example) were hit by unusually large transitory shocks. An ideal measure of inflation persistence should filter those out.

PCE data are subject to revision by the Bureau of Economic Analysis (BEA). How does that affect MCT estimates?

BEA monthly revisions as well as other BEA periodic revisions to PCE price data do lead to reassessments of the estimated inflation persistence as measured by the MCT estimates. Larger revisions may lead to a more significant reassessment. A recent example of the latter case is described on Liberty Street Economics in “Inflation Persistence: Dissecting the News in January PCE Data.”

Historical estimates in our MCT data series back to 1960 are based on the latest vintage of data available and incorporate all prior revisions.

How does the MCT Inflation measure relate to other inflation measures?

The MCT model adds to the set of tools that aim at measuring the persistent component of PCE price inflation. Some approaches, such as the Cleveland Fed’s Median PCE and the Dallas Fed’s Trimmed Mean, rely on the cross-sectional distribution of price changes in each period. Other approaches, such as the New York Fed’s Underlying Inflation Gauge (UIG), rely on frequency-domain time series smoothing methods. The MCT approach shares some features with them, namely: exploiting the cross-sectional distribution of price changes and using time series smoothing techniques. But the MCT model also has some unique features that are relevant to inflation data. For example, it allows for outliers and for the noisiness of the data and for the relation with the common component to change over time.

How useful can MCT data be for policymakers?

The MCT model provides a timely measure of inflationary pressure and provides insights on how much price changes comove across sectors.

View the Multivariate Core Trend of PCE Inflation data here.

Technology-Watching: Quantum Microchips Connected in Record-Breaking World First

[from UK Research and Innovation]

Researchers in the UK have successfully transferred data between quantum microchips for the first time.

This helps overcome a key obstacle to building a commercial quantum computer.

The milestone achieved by a team from the University of Sussex and Brighton-based quantum computer developer Universal Quantum, allows chips to be linked like a jigsaw.

On track to useful quantum computers

It means that many more qubits, the basic calculating unit, can be joined together than is possible on a single microchip. This will make a more powerful quantum computer possible.

The project, which has been backed by the Engineering and Physical Sciences Research Council (EPSRC), has also broken the world record for quantum connection speed and accuracy.

The scaling of qubit numbers from the current level of around 100 qubits to nearer 1 million is central to creating a quantum processor that can make useful calculations.

The significant achievement is based on a technical blueprint for creating a large-scale quantum computer, which was first published in 2017 with funding from EPSRC.

Within the blueprint was the ground-breaking concept successfully demonstrated with this research of linking quantum computing modules with electrical fields.

Unlocking UK potential

The UK is a leader in the global race to develop useful quantum computers, which represent a step-change in computing power.

Their development may help solve pressing challenges from drug discovery to energy-efficient fertilizer production. But their impact is expected to sweep across the economy, transforming most sectors and all our lives.

Potential to scale up

Winfried Hensinger, Professor of Quantum Technologies at the University of Sussex and Chief Scientist and co-founder at Universal Quantum said:

As quantum computers grow, we will eventually be constrained by the size of the microchip, which limits the number of quantum bits such a chip can accommodate.

In demonstrating that we can connect 2 quantum computing chips, a bit like a jigsaw puzzle, and, crucially, that it works so well, we unlock the potential to scale up by connecting hundreds or even thousands of quantum computing microchips.

Speed and precision

The researchers were successful in transporting the qubits using electrical fields with a 99.999993% success rate and a connection rate of 2424 transfers per second. Both numbers are world records.

Dr. Kedar Pandya, Director of Cross-Council Programmes at EPSRC, said:

This significant milestone is evidence of how EPSRC funded science is seeding the commercial future for quantum computing in the UK.

The potential for complex technologies, like quantum, to transform our lives and create economic value widely relies on visionary early-stage investment in academic research.

We deliver that crucial building block and are delighted that the University of Sussex and its spin-out company, Universal Quantum, are demonstrating the strength it supports.

Institute of Physics award winner

Universal Quantum has been awarded €67 million from the German Aerospace Center to build 2 quantum computers.

The University of Sussex spin-out was also recently named as one of the 2022 Institute of Physics award winners in the business start-up category.