Japan Inc. Now Sells No Yen to Invest Abroad

Earnings on Japan’s foreign direct investment (FDI) reached 103% of new FDI in 2022–25. With dividends and retained earnings counted together, Japan Inc. now needs to sell little yen to invest abroad.

[by OKUBO Takuji]

Key takeaways

  • Foreign affiliates now earn about as much as Japan invests abroad each year. Reinvested earnings, dividends and interest together reached 103% of new outward FDI in 2022–25, against 48% in 1996–2000.
  • Dividends from foreign affiliates account for a growing share of Japanese corporate profit. We estimate that foreign affiliates contributed 13.4% of Japan Inc.’s earnings in FY2025, up from 1.7% in FY1996.
  • Corporate investment abroad now involves little net yen selling. After dividends and interest paid home, the estimated outflow has been close to zero since 2022, down from about ¥5 trillion a year, or about 1% of GDP, on average in the 2010s.

Japan’s FDI stock now earns 103% of new investment

It is often said that Japan’s ageing population and slow growth give its companies too few investment opportunities at home. A Japanese government report in 2024 included the following passages.

“Japan’s ageing and shrinking population depresses expected demand at home. Expected returns remain higher abroad, so Japanese companies have accelerated outward direct investment” (my translation). — MATSUBAYASHI Yōichi [松林 洋一], MOF PRI, chapter 8, p.136.

“Companies invested abroad because they saw no promising investments in Japan; they are unlikely to bring back every return. On a cash-flow basis, the external balance is in deficit and is one factor behind the weak yen” (my translation). — KARAKAMA Daisuke [唐鎌 大輔], MOF PRI, chapter 10, pp.178 and 175.

However, my review of recent data shows that while their premise of low growth prospects in Japan is probably still right, the direct investment Japan has accumulated abroad has reached a level where it earns enough to cover Japan’s new investment abroad. This changes the exchange-rate implication even if Japan keeps investing abroad.

As chart 1 shows, earnings on the accumulated investment stock rose from 48% of new outward FDI in 1996–2000 to 103% in 2022–25.

Chart 1
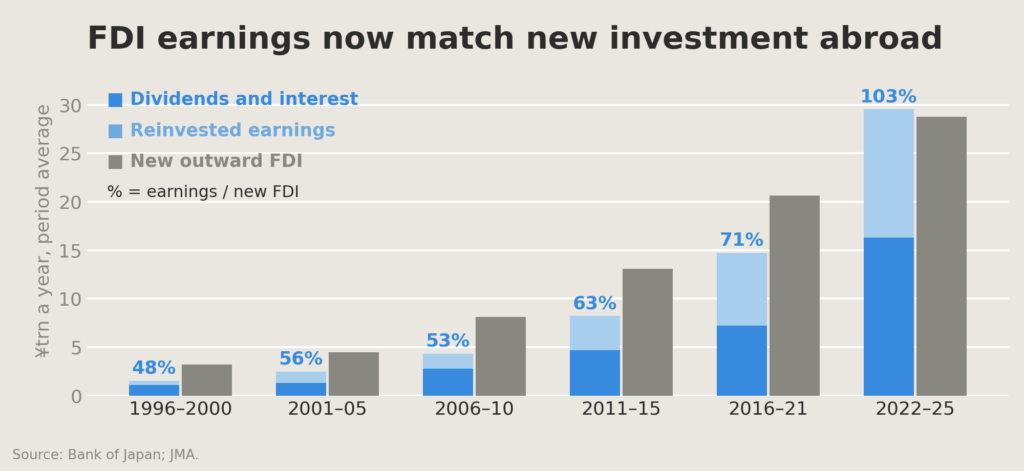
Overseas affiliates pay interest and dividends to their parent companies in Japan. Those dividends have become a sizable part of corporate Japan’s income: we estimate that they made up 13.4% of Japanese corporate profit in FY2025, up from 1.7% in FY1996.

When foreign affiliates retain their earnings on their balance sheets, Japan’s balance of payments statistics record them as FDI from Japan, even though no money crosses the border. While the companies receiving FDI dividends and the companies paying for new FDI are not necessarily the same, Japan Inc. as a whole is now financing its FDI almost entirely from the earnings of its overseas affiliates. At the current level of FDI, little new yen needs to be converted into foreign currencies as Japan goes about investing abroad.

In the rest of this report, I explain how foreign direct investment by Japanese companies evolved, and its near-term outlook. This report is the third in a series on the yen repatriation theme that I have published over the past few weeks, following “Yen Repatriation Starts with the Whale”, on capital flows through Japan’s national pension funds, and “Mrs Watanabe No More”, on Japanese households’ assets invested abroad.

A strong yen helped drive Japan’s first outward FDI boom

Japan’s outward investment was heavily restricted after WWII, requiring case-by-case permission from the government. Approvals became more and more automatic over the years until outward investment became “free in principle” in 1980. Trade friction with the US-led Japanese carmakers to restrain their exports from 1981, pushing them to build factories abroad. The rapid appreciation of the yen was also a factor. The yen strengthened from ¥242 per dollar before the Plaza Accord in September 1985 to ¥121 by the end of 1987. Japanese producers had to move lower value-added work abroad. The strong yen also gave Japanese financial institutions sizable purchasing power for a while, until the stock and property bubbles burst in 1990 and 1991.

All of these factors contributed to a rapid increase in outward FDI through the 1980s and 1990s (chart 2).

Chart 2

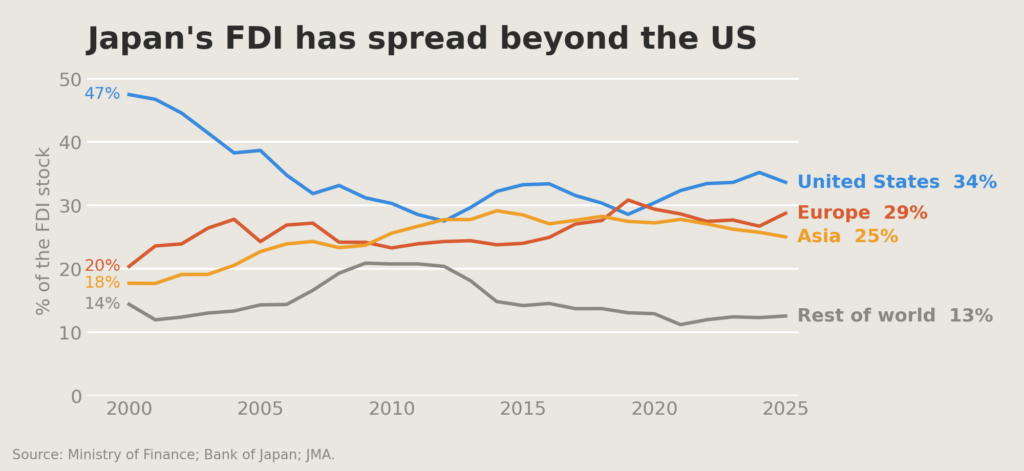
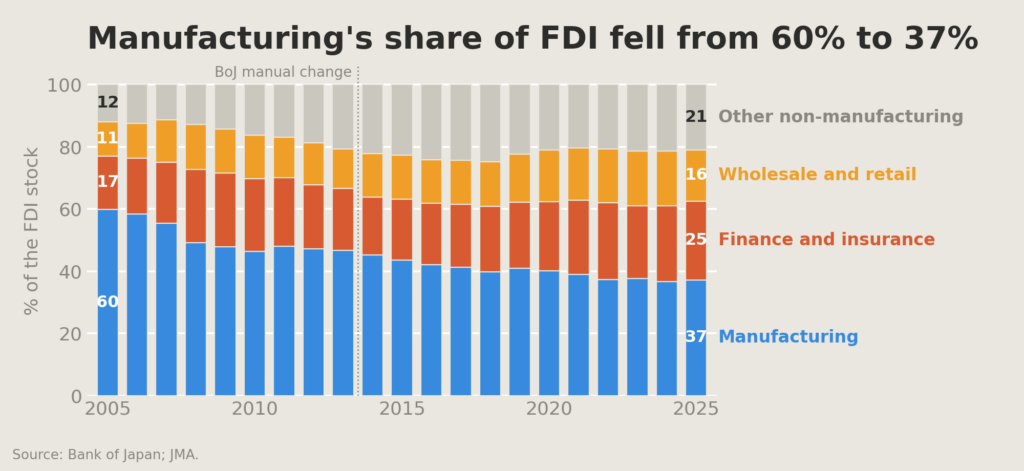
Even after the bubble burst, the strong yen kept pushing manufacturers to move abroad. In 2005, manufacturers accounted for 60% of the FDI stock. As Japanese manufacturers expanded their supply chains abroad, Asia’s share of outward FDI rose from about 12% in FY1986–90 to 19% in FY1995–99, and Asia held 23% of the FDI stock by 2005 (chart 3).

Chart 3
Japan’s outward FDI stock rose to 56% of GDP

The next phase was sustained by a different pressure. With weak growth and low interest rates at home, Japan Inc. kept investing abroad, across a broader range of industries. Between 1995 and 2025, the stock of FDI rose from 9% of Japan’s GDP to 58% (chart 4). In 2025, it is as large as about 38% of the private sector’s domestic fixed capital, on our estimate.

Chart 4

By industry composition and by destination compositions changed over time. Manufacturing’s share of the FDI stock had fallen to 37% by 2025, giving Japan’s FDI more breadth. By destination, we are seeing a revival of FDI toward the United States. It accounted for 34% of the stock in 2025, Europe 29% and Asia 25% (see earlier chart 3).
Thus, after decades of overseas investment, Japan’s FDI stock is now large enough that its earnings are sufficient to finance new investment abroad, at least for now. In the next section, I consider whether this will continue, and in particular whether Japanese companies may bring an even larger share of their overseas earnings back to Japan, given the weak yen, higher borrowing costs in yen and possibly better investment opportunities at home.

The weak yen has slowed offshoring, not reversed it

The real depreciation of the yen over the past 15 years made production in Japan more competitive. There is some evidence that manufacturers are considering bringing production back to Japan. The 2023 manufacturing white paper found more firms shifting production back from China than moving there, and they named the weak yen as one reason. We see some signs of reshoring. Japanese manufacturers’ overseas production ratio rose from 18.0% in FY2011 to 27.2% in FY2023, but it may have started to decline or at least stabilize. The ratio fell to 26.7% in FY2024. A Cabinet Office survey of listed manufacturers puts the ratio at 24.5% in FY2025, and their plan for FY2030 is broadly unchanged at 24.7%. The weak yen seems to have stabilized the wave of offshoring, but I see no firm evidence of a move back onshore yet.

Domestic investment has grown slowly despite the weak yen

There are tentative signs that domestic capital spending is starting to grow again. For three decades it grew at a very low speed. In real terms, private business investment rose only 26% between FY1997 and FY2025, less than 1% a year. In comparison, capital spending grew by about 4% a year on average in the United States. In my view, a weak currency is only one of the factors manufacturers weigh in designing their global production chains. The weak yen makes production in Japan competitive today, but they have also seen the exchange rate swing violently within short periods. Japan also has a shrinking population problem. It started to address it by opening a door to immigration, but the door is only tentatively open. Overall, my view is that the weak yen alone is unlikely to give Japan Inc. sufficient incentive to bring its capital back to Japan and to the yen.

Economic security is bringing some production home

The government is pushing harder than the currency, mostly in the name of economic security, even before the Takaichi government came along. The government currently has a ¥250 trillion domestic investment target for FY2040 and named AI and semiconductors among its 17 strategic fields. Semiconductors are where the money has gone furthest. In November 2024, under the Ishiba government, Japan committed more than ¥10 trillion of public support to AI and semiconductors by FY2030, aiming to draw more than ¥50 trillion of public and private investment over ten years. Japan managed to lure a TSMC plant to Japan, backed by a sizable subsidy. Rapidus, a government-supported Japanese semiconductor maker, has received a sizable subsidy and is building a factory in Hokkaido. Japan’s production of integrated circuits and discrete semiconductors rose from ¥2.7 trillion in 2019 to ¥4.1 trillion in 2025.

Under the name of economic security, the Japanese government is promoting other industries such as batteries, shipbuilding and pharmaceuticals. Defence spending adds to the push. Japan’s defence budget rose from about ¥5 trillion in FY2022 to ¥9.0 trillion in FY2026. Some defence contractors, such as Mitsubishi Heavy Industries, have doubled their defence revenue.

Japan’s industrial-policy record gives reason for caution

The Japanese government and the Ministry of Economy, Trade and Industry (METI), the key agency behind Japan’s industry policy, may claim some expertise in their industrial policies. Empirical studies in the past paint a poor track record, though. Rapidus, the most ambitious semiconductor project, has had no independent cost-benefit assessment (Negrine et al., 2025). While defence and economic security-driven policies have a different logic, I doubt that these industrial policies will succeed in bringing large-scale manufacturing investment back to Japan so long as macro factors such as Japan’s demography remain unfavourable.

FDI no longer appears to drive yen weakness

The weak yen and non-economic geopolitical factors do point to a halt in Japan’s four-decade offshoring trend, although it is a stabilization, rather than an economy-wide reversal of past offshoring. Japan Inc. will continue to invest more abroad, rather than within its borders. Given the sizable growth in the stock of cumulative FDI, Japan Inc. no longer needs to convert yen into overseas currency to keep investing abroad though. Net of dividends and interest paid home, Japan’s FDI sold about ¥5 trillion of yen a year, or about 1% of GDP, on average in the 2010s; since 2022 the net flow has been close to zero. There is also an interesting development in an effort to allow more share-exchange based M&A for cross-border deals that will further reduce the need for Japanese companies to spend their yen to purchase overseas assets. In my view, Japan Inc.’s FDI is no longer a factor to drive the yen weaker.

References

World-Watching: Container Shipping Financial Insight, Nov. 2023

[from Drewry Shipping Consultants]

Driven by weak 3Q23 financial results, the Drewry Container Equity Index decreased 3.7% last month (as of 22 Nov 2023). Additionally, asset prices continue to fall due to the supply-demand imbalance.

  • Container shipping companies’ 3Q23 financial results showcased a sharp dip in profits or even losses. On a group level, eleven liners (which report quarterly results) among our portfolio of 13 companies reported an average slump of 54.6% YoY in their 3Q23 topline. Operating costs declined 18.1% YoY amid falling chartering costs and lowering bunker prices. However, the cost reduction was insufficient to offset the plunge in topline; thus, EBIT contracted 94.1% YoY on average.
  • The Drewry Container Equity Index tumbled 28.1% YTD 2023 (ending 22 November), driven by lowering freight rates (WCI: -30.7% in YTD 2023), which squeezed earnings over the quarters. On the contrary, the S&P 500 posted an 18.4% growth. The Drewry Container Equity Index declined 3.4% in the month ending 22 November 2023. Talking about equity prices individually, APMM’s stock price fell 9.0% amid EBIT loss for its Ocean segment in 3Q23, staff cuts and reduced capex guidance, highlighting APMM’s efforts toward reducing costs faced with the bleak industry outlook. Hapag-Lloyd’s stock price slumped 22.2% as its EBIT margin (3Q23: 5.1%) slid below its pre-pandemic level (3Q19: 7.8%). ZIM became the first carrier to report impairment of assets worth USD 2.0bn in 3Q23, and its stock price fell 18.1%. Meanwhile, China-exposed container companies benefitted from the positive sentiment arising from the proposed fiscal stimulus by the Chinese government, possibly boosting the out-of-China and intra-Asia trades. Asian stocks in the broader index rose 2.0% to 19.4% in the month ending 22 November 2023.
  • Mainly driven by weak earnings prospects, the Drewry Container Equity Index trades at a P/B of 0.5x, a 47.5% discount to its pre-pandemic average (2013-19). We expect freight rates to fall sharply in 2024 and increasingly incur losses. Thus, we expect the multiple to remain suppressed.
  • As the fleet of container shipping companies expands, the charter market softens. For instance, 1-year TC rates declined 14.2% and 52.5% YoY in October for vessels sized 1,110 teu and 8,500 teu. Rates declined more for larger vessels as these constitute the majority of the order book and new deliveries. The YoY decline has continued since October 2022, but rates improved slightly during April-May 2023. However, this was not due to the fundamentally strong market but MSC and CMA CGM’s aggressive chartering of vessels to expand their fleets. Now that the two companies have stopped chartering in vessels, the charter market continues to decline.
  • Driven by the softening charter market, second-hand asset prices are also weakening. In October, on a YoY basis, prices for five-year-old vessels (2,700 teu and 7,200 teu) contracted 30.6% and 31.5%, and for 10-year-old ships, prices tumbled between 36.7% and 53.2%. Contrary to the sale and purchase market, newbuild prices (1,500 teu and 14,000 teu) continue to increase and rose by an average of 2.2% YoY, led by a shortage of capacity in shipyards.
  • The charter market and the S&P market have a direct impact on container shipping companies’ earnings. Costs related to chartering-in slots or vessels from other non-operating vessel owners form a significant portion of container shipping companies’ cost structure. In the 3Q23 results, this cost was reduced,
    marginally relieving downside pressure on the operating margin of container shipping companies. In line with the declining charter market, we expect this trend to continue in 4Q23. We also expect other companies to follow ZIM in reporting impairment losses as prices for older vessels continue to fall.

Read the report [archived PDF] for additional graphs.

World-Watching: Germany Bundesbank: What Moves Markets?

[Deutsche Bundesbank discussion paper 16/2022 by Mark Kerssenfischer & Maik Schmeling]

Non-technical summary

Research question

A key question in the macro-finance literature concerns the drivers of asset prices. Are asset prices mainly driven by news, or by changes in sentiment and other factors unrelated to economic fundamentals? In most asset pricing models, news play a dominant role. But in empirical investigations, the explanatory power of news is often quite low.

Contribution

We study the explanatory power of news by building a large, time-stamped event database covering a wealth of news related to the macroeconomy, including macroeconomic data releases, central bank announcements, bond auctions, election results, sovereign rating downgrades, and natural catastrophes. We combine this event database with high-frequency stock price and bond yield changes, both for the U.S. and the euro area, going back to 2002.

Results

We find that roughly half of all stock and bond price movements in the U.S. and euro area occur in tight windows around clearly identifiable news and in this sense can be explained by those news. On the positive side, this share is much higher than most previous studies found. However, our results still ascribe a large role to return variation that cannot be linked to news about economic fundamentals.

Read the paper [archived PDF].

Asia-Watching: New Studies on Tariffs; FDIs and Global Value Chains

[from Asia-Pacific Economic Cooperation, May 15, 2022]

Study on Tariffs: Analysis of the
Regional Comprehensive Economic Partnership
Tariff Liberalization Schedules

prepared by Carlos Kuriyama, Sylwyn C. Calizo Jr. & Jason Carlo O. Carranceja

RCEP is the largest regional free trade agreement (FTA) in the world. Its potential is huge, as its 15 members account for about 2.2 billion people (30% of the global population), a regional gross domestic product (GDP) of about USD38,813 billion (30% of global GDP), and 28.8% of global trade. This study examines market access commitments and comparing the extent of tariff liberalization within RCEP as well as the other major regional FTA in the Asia-Pacific, the Comprehensive and Progressive Agreement for Trans-Pacific Partnership (CPTPP).

Read the full article [archived PDF].

The FDI Network, Global Value Chain Participation and Economic Upgrading

by Luna Ge Lai, Nguyen Thu Quynh & Akhmad Bayhaqi

Foreign direct investment (FDI) represents an important internationalization pathway to global value chain (GVC) participation. APEC economies as a group have dominated as FDI recipients, accounting for nearly 52% of the global inward FDI stock. This study analyses the role of FDI in economies’ GVC participation.

Read the full article [archived PDF].

Education and “Then and Now” Thinking: Zola’s Novel L’Argent

It is amazing to see how certain nineteenth century phenomena, such as Émile Zola’s novel L’Argent (“Money”), eerily echo with our own times. The novel has fundamentalist evangelical Christianity, international financial chicanery, anti-Semitism, the signs of full-blown “casino capitalism” convulsing the whole of society, global technical innovations. The historical background as all this unfolds is explosive and complex.

L’Argent is the eighteenth novel in the Rougon-Macquart series by Émile Zola. It was serialized in the periodical Gil Blas beginning in November 1890, before being published in novel form by Charpentier et Fasquelle in March 1891.

The novel focuses on the financial world of the Second French Empire as embodied in the Paris Bourse and exemplified by the fictional character of Aristide Saccard. Zola’s intent was to show the terrible effects of speculation and fraudulent company promotion, the culpable negligence of company directors, and the impotency of contemporary financial laws. (Think of Dodd-Frank in our time and how insiders have “noiselessly” dismantled it.)

The novel takes place in 1864-1869, beginning a few months after the death of Saccard’s second wife Renée (see La Curée). Saccard is bankrupt and an outcast among the Bourse financiers. Searching for a way to reestablish himself, Saccard is struck by plans developed by his upstairs neighbor, the engineer Georges Hamelin, who dreams of restoring Christianity to the Middle East through great public works: rail lines linking important cities, improved roads and transportation, renovated eastern Mediterranean ports, and fleets of modern ships to move goods around the world.

Saccard decides to institute a financial establishment to fund these projects. He is motivated primarily by the potential to make incredible amounts of money and reestablish himself on the Bourse. In addition, Saccard has an intense rivalry with his brother Eugène Rougon, a powerful Cabinet minister who refuses to help him after his bankruptcy and who is promoting a more liberal, less Catholic agenda for the Empire. Furthermore, Saccard, an intense anti-Semite, sees the enterprise as a strike against the Jewish bankers who dominate the Bourse. From the beginning, Saccard’s Banque Universelle (Universal Bank) stands on shaky ground.

In order to manipulate the price of the stock, Saccard and his colleagues in the syndicate, which he has set up to jumpstart the enterprise, buy their own stock and hide the proceeds of this illegal practice in a dummy account fronted by a straw man.

While Hamelin travels to Constantinople to lay the groundwork for their enterprise, the Banque Universelle goes from strength to strength. Stock prices soar, going from 500 francs a share to more than 3,000 francs in three years. Furthermore, Saccard buys several newspapers which serve to maintain the illusion of legitimacy, promote the Banque, excite the public, and attack Rougon.

The novel follows the fortunes of about 20 characters, cutting across all social strata, showing the effects of stock market speculation on rich and poor. The financial events of the novel are played against Saccard’s personal life. Hamelin lives with his sister Caroline, who, against her better judgment, invests in the Banque Universelle and later becomes Saccard’s mistress. Caroline learns that Saccard fathered a son, Victor, during his first days in Paris. She rescues Victor from his life of abject poverty, placing him in a charitable institution. But Victor is completely unredeemable, given over to greed, laziness, and thievery. After he attacks one of the women at the institution, he disappears into the streets, never to be seen again.

Eventually, the Banque Universelle cannot sustain itself. Saccard’s principal rival on the Bourse, the Jewish financier Gundermann, learns about Saccard’s financial trickery and attacks, losing stock upon the market, devaluing its price, and forcing Saccard to buy millions of shares to keep the price up. At the final collapse, the Banque holds one-fourth of its own shares worth 200 million francs. The fall of the Banque is felt across the entire financial world. Indeed, all of France feels the force of its collapse. The effects on the characters of L’Argent are disastrous, including complete ruin, suicide, and exile, though some of Saccard’s syndicate members escape and Gundermann experiences a windfall.

History itself is of course “bubbling along” and does not go away:

Because the financial world is closely linked with politics, L’Argent encompasses many historical events, including:

By the end of the novel, the stage is set for the Franco-Prussian War (1870–1871) and the fall of the Second Empire.

The twentieth century world and the twenty-first century one do resonate with Zola’s novel. That tells you, the student, that there are deep structures underlying endless changes.

The arrival of cars and planes, computers and lasers, internet and AI have not altered these substructures entirely and that is educational, since “then and now” thinking is part of a meta-intelligent (i.e., perspectival) education process.