Economics-Watching: Tracking Business Sentiment in the Western United States

[from the Federal Reserve Bank of San Francisco, Economic Letters, 11 August, 2025]

by Hamza Abdelrahman, Luiz Edgard Oliveira and Aditi Poduri

Information the San Francisco Fed collects from businesses and community sources for the Beige Book provides timely insights into economic activity at both the national and regional levels. Two new indexes based on Beige Book questionnaire responses track business sentiment across the western United States. The indexes track data on economic activity and inflation, serving as early indicators of official data releases and helping improve near-term forecasting accuracy. The latest index readings suggest weakening economic growth and intensifying inflationary pressures over the coming months.


The San Francisco Fed serves the 12th District—the largest in the Federal Reserve System, representing nine western states, two territories, and a commonwealth. To better understand and analyze the regional economy, we collect information from a variety of business and community sources to create the San Francisco Fed’s report for the Beige Book. This is compiled with reports from other Districts and published by the Federal Reserve Board of Governors eight times a year. 

Views about the economy from businesses and communities play an important role in shaping economic outcomes. For example, expectations for future inflation can help spur or slow current consumer spending and business investment. Furthermore, economic forecasters rely on models that incorporate both more traditional “hard” quantitative data and “soft” qualitative information on sentiment. Adding these soft measures has been shown to improve the accuracy of economic forecasts (see Shapiro, Moritz, and Wilson 2022 and their cited literature). Among the many sentiment measures available, two popular approaches rely on survey data, as in the University of Michigan’s Surveys of Consumers, or on textual analysis, as in the SF Fed’s Daily News Sentiment Index.

This Economic Letter examines the economic information collected through the SF Fed’s Beige Book questionnaire over the past 10-plus years. We analyze this information by constructing sentiment indexes from the qualitative data and comparing them with quantitative measures of national and regional economic activity and inflation. We introduce two indexes—the SF Fed Business Sentiment Index and the SF Fed Inflation Gauge Index—which track our contacts’ views and expectations for economic growth and inflation, respectively. We find that these new indexes serve as reliable early indicators of official data releases and help improve near-term forecast accuracy. The SF Fed Business Sentiment Index has generally exhibited patterns similar to other recent business and household sentiment indexes, and the SF Fed Inflation Gauge Index has shown a strong uptick in expected inflation. To regularly monitor changes in these two indexes, the San Francisco Fed has launched a new Twelfth District Business Sentiment data page.

Constructing regional sentiment indexes

The San Francisco Fed sends out a Beige Book questionnaire to business and community contacts across the District eight times a year to gather regional information. In addition to answering questions regarding their organizations, respondents share their views on regional and national topics, including economic activity and inflationary pressures.

In two questions, respondents indicate whether they see national output growth and inflation rates increasing, decreasing, or staying stable over the coming year using a standard five-tiered scale. We use these responses since 2014 to formulate two business sentiment indexes, one on economic activity and another on inflation. We assign standard weights to the five-tiered qualitative scale that are symmetrical around zero. For example, we ask if activity is expected to “decrease significantly” = –2, “decrease” = –1, “remain unchanged” = 0, “increase” = 1, or “increase significantly” = 2. We add up the weighted shares of responses for each tier within each index. We then normalize each resulting series by its own average and standard deviation for ease of comparison with traditional economic indicators.

Tracking business sentiment

Figure 1 shows how the SF Fed Business Sentiment Index (blue line), compiled from responses to the question on national economic activity, compares with data on changes in national GDP (green line). We measure national output as the four-quarter change in inflation-adjusted, or real, GDP, normalized by its average and standard deviation so that it is centered around zero and, hence, more directly comparable to the SF Fed Business Sentiment Index. The vertical axis shows how many standard deviations away each observation is from its respective measure’s average from 2014 to mid-2025.

Figure 1
Economic growth versus business sentiment
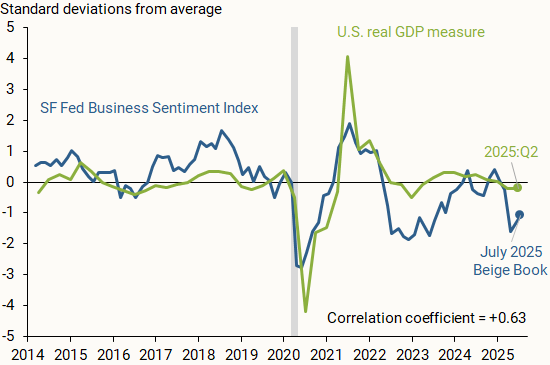
Notes: Indicators normalized by their respective averages and standard deviations based on data from 2014 to present. Gray bar indicates NBER recession dates. Correlation coefficient is calculated between quarterly versions of both indicators.
Source: Bureau of Economic Analysis, FRBSF Beige Book questionnaire responses, and authors’ calculations.

The SF Fed Business Sentiment Index generally tracks the movements in national GDP over the past decade; a correlation coefficient of +0.63 on a scale of –1 to 1 indicates a moderately strong positive relationship between the two measures. A relatively recent exception started in 2022, when our index began showing a considerable decline relative to the national GDP measure. Respondents across the District were downbeat about economic growth and reported expectations of a sharp decline in consumer spending and overall household financial health following the depletion of pandemic-era savings (Abdelrahman and Oliveira 2023). A similar decline appeared in other measures of business and household sentiment. Nevertheless, overall economic growth continued at a solid pace. This decoupling between sentiment and hard data that began in 2022 was dubbed a “vibecession” (Daly 2024, Scanlon 2022).

Another possible reason for the divergence between national real GDP and our Business Sentiment Index is the influence of the regional economy. Although respondents are asked about their views of national GDP, their responses may be affected by regional outcomes. Thus, our index may also reflect a regional perspective from our business and community contacts.

Figure 2 supports this rationale, showing the SF Fed Business Sentiment Index alongside a measure of regional output growth (gold line). We find that the measures closely track one another, including for 2022 and 2023, with a correlation coefficient of +0.74. We define District real GDP growth as the year-over-year percent change in the total output of the District’s nine states as reported by the Bureau of Economic Analysis (BEA). We normalize the series as described before.

Figure 2
Regional economic growth and business sentiment
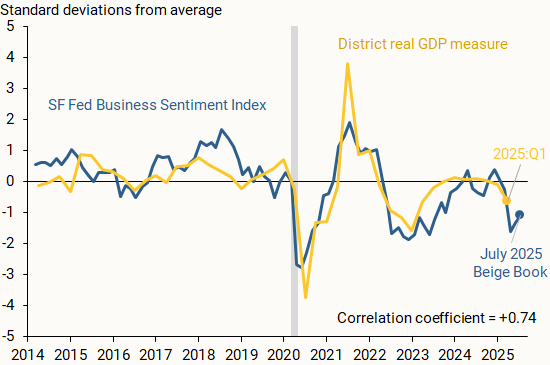
Notes: Indicators normalized by their respective averages and standard deviations based on data from 2014 to present. Gray bar indicates NBER recession dates. Correlation coefficient is calculated between quarterly versions of both indicators.
Source: Bureau of Economic Analysis, FRBSF Beige Book questionnaire responses, and authors’ calculations.

Our findings indicate that the SF Fed Business Sentiment Index can serve as an accurate early indicator for national and regional output growth. Since the regional Beige Book questionnaire is collected twice each quarter, it provides particularly timely insights into economic activity during the current quarter. By contrast, the first GDP data release for any given quarter usually arrives a full month after that quarter has ended, and initial data releases for state-level output growth arrive with even more delay.

Over the first half of this year, the SF Fed Business Sentiment Index turned negative, with contacts citing elevated uncertainty about trade policy and downbeat expectations for the labor market. This notable decline is also seen in other measures of household and business sentiment, including national measures, such as the University of Michigan’s Surveys of Consumers, and regional measures, such as the Cleveland Fed’s Survey of Regional Conditions and Expectations and the Dallas Fed’s Texas Business Outlook Surveys.

Gauging business views on inflationary pressures

Our Beige Book questionnaire responses also provide insights into how business and community contacts in the District see national inflation evolving. Figure 3 compares the SF Fed Inflation Gauge Index (blue line) with monthly changes in the year-over-year headline personal consumption expenditures (PCE) inflation rate published by the BEA (green line). We normalize the inflation series and index as discussed earlier.

Figure 3
SF Fed Inflation Gauge Index versus realized inflation
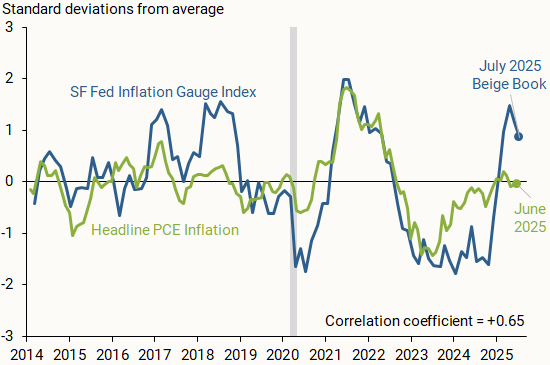
Notes: Green line is the percentage point change in year-over-year headline PCE inflation shown as a 6-month moving average. Indicators normalized by their respective averages and standard deviations based on data from 2014 to present. Gray bar indicates NBER recession dates. Correlation coefficient is calculated between quarterly versions of both indicators.
Source: Bureau of Economic Analysis, FRBSF Beige Book questionnaire responses, and authors’ calculations.

Similar to our business sentiment index, the inflation gauge index is an early indicator for official inflation data releases. The index generally tracks changes in headline PCE inflation over the past decade, with a correlation coefficient of +0.65.

The most recent index results suggest a strong uptick in expected inflation among SF Fed business contacts, with several responses citing trade policy adjustments and inflation being persistently above the Federal Reserve’s 2% target. The recent peak resembles the one in 2018, which followed heightened trade tensions with China. The surge tracks other business and household-based measures of short-term inflation expectations, such as the Atlanta Fed’s Business Inflation Expectations and the New York Fed’s Survey of Consumer Expectations.

Making better projections

Beyond tracking data on national and regional economic conditions, we consider whether our two indexes can help improve one-year-ahead projections of output growth and overall inflation. We run linear regressions on a 2014–2022 data sample and estimate out-of-sample projections for the period starting in the first quarter of 2023. We run this analysis for the three economic measures—national GDP, regional GDP, and inflation—once with our index included on the right-hand side of the regression equation and once without the index. For this analysis, we use versions of the SF Fed Business Sentiment Index and the SF Fed Inflation Gauge Index that have been aggregated quarterly.

Figure 4 compares the out-of-sample projection accuracy of the two iterations. Across all economic measures, incorporating the SF Fed Business Sentiment Index or the SF Fed Inflation Gauge Index in the regression noticeably reduced the forecast errors for the out-of-sample period. This general result appears to hold when we project output growth and inflation one quarter ahead, in line with other studies that incorporate soft data from the Beige Book in short-term projections (Balke and Petersen 2002). The results are also consistent when using a local projections method from Jordà (2005) for one-year-ahead projections of output growth and shorter-term projections of inflation. This further supports the usefulness of our qualitative measures as early indicators of the future economic landscape over the short term.

Figure 4
Forecast errors with and without SF Fed sentiment indexes
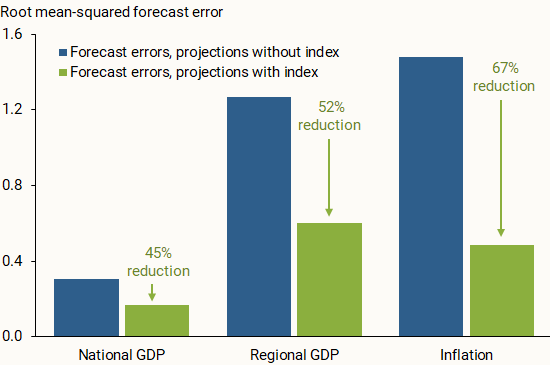
Notes: Root mean-squared errors of out-of-sample projections from 2023:Q1 to 2025:Q2 including and excluding the SF Fed Business Sentiment Index (for GDP) and SF Fed Inflation Gauge Index (for inflation).
Source: Bureau of Economic Analysis, FRBSF Beige Book questionnaire responses, and authors’ calculations.

Conclusion

Information collected from businesses and communities through the San Francisco Fed’s regional Beige Book questionnaire can provide valuable insights into the national and regional economies. Sentiment indexes described in this Letter use responses from Twelfth District Beige Book contacts to generally track economic activity and inflation. Our two indexes serve as reliable early indicators of official data, which could help improve near-term forecast accuracy. The SF Fed Business Sentiment Index remained negative for much of 2022 and 2023, possibly reflecting more subdued growth within the District relative to the United States. Meanwhile, the SF Fed Inflation Gauge Index spiked in recent months following adjustments to trade policy.

References

Abdelrahman, Hamza, and Luiz E. Oliveira. 2023. “The Rise and Fall of Pandemic Excess Savings.” FRBSF Economic Letter 2023-11 (May 8).

Balke, Nathan S., and D’Ann Petersen. 2002. “How Well Does the Beige Book Reflect Economic Activity? Evaluating Qualitative Information Quantitatively.” Journal of Money, Credit and Banking 34 (1), pp. 114–136.

Daly, Mary C. 2024. “Fireside Chat with Mary C. Daly at the San Diego County Economic Roundtable.” January 19.

Jordà, Òscar. 2005. “Estimation and Inference of Impulse Responses by Local Projections.” American Economic Review 95(1), pp. 161–182.

Scanlon, Kyla. 2022. “The Vibecession: The Self-Fulfilling Prophecy.” Kyla Substack (June 30).

Shapiro, Adam Hale, Moritz Sudhof, and Daniel Wilson. 2022. “Measuring News Sentiment.” Journal of Econometrics 228(2), pp. 221–243.
China to Sustain Top-Down, Debt-Fueled Investment in Major Projects and Security Capacities, Ex-Official Says

Dong Yu, now at Tsinghua, says via state media that Beijing-decreed, central govt bond-backed construction will continue into the next five years.

[from the Center for China & Globalization’s Pekingology]

by Zichen Wang, 10 August, 2025

The key concept in today’s newsletter is 国家重大战略实施和重点领域安全能力建设, in abbreviation in Chinese as 两重 liǎng zhòng.

In English, it is translated officially as the implementation of major national strategies and building up security capacity in key areas, hereinafter referred to as “Two Major Undertakings.”

The concept first appeared in official policy documents in the Chinese Premier’s Report on the Work of the Government [archived PDF] in March 2024.

To systematically address funding shortages facing some major projects for building a great country and advancing national rejuvenation, it is proposed that, starting this year and over each of the next several years, ultra-long special treasury bonds be issued. These bonds will be used to implement major national strategies and build up security capacity in key areas. One trillion yuan of such bonds will be issued in 2024.

By the end of the year, the yuan tag, despite being approved by the national legislature, had changed by 300 billion. The People’s Daily newspaper reported in December 2024.

As of now, the 700 billion yuan in ultra-long-term special treasury bonds allocated for the “two major undertakings” has been distributed in three batches to specific projects.

In 2025, the following year, the Report on the Work of the Government [archived PDF] says,

A total of 1.3 trillion yuan of ultra-long special treasury bonds will be issued, 300 billion yuan more than last year.

735 billion yuan will be earmarked in the central government budget for investment. We will put ultra-long special treasury bonds to good use, increase ultra-long-term loans and other types of financing support, and strengthen top-down organization and coordination to ensure greater support for the implementation of major national strategies and security capacity building in key areas.

A simultaneous Finance Ministry budget plan [archived PDF] rounds up the overall central government spending for the Two Major Undertakings to 800 billion yuan in 2025.

In yuan terms, the much-touted new government subsidies to households pale in comparison with the two major undertakings.

Also from the 2025 Report on the Work of the Government [archived PDF]:

Ultra-long special treasury bonds totaling 300 billion yuan will be issued to support consumer goods trade-in programs. This represents an increase of 150 billion yuan over the previous year.

This week, China announced this week that the phased free preschool education policy will cover all children in their final year of kindergartens, saving families 20 billion yuan. Childcare subsidies unveiled in July amount to 90 billion yuan. 

As Joe Biden repeated over the years,

Don’t tell me what you value. Show me your budget, and I’ll tell you what you value.

The National Development and Reform Commission said last month:

In 2025, a total of 800 billion yuan has been allocated for the “two major undertakings,” supporting 1,459 projects in key areas such as ecological restoration in the Yangtze River Basin, major transportation infrastructure along the Yangtze River, the New Western Land–Sea Corridor, high-standard farmland, major water conservancy projects, urban underground pipeline networks, the “Three-North” shelterbelt program, and the renovation of hospital wards.

Now that the 2025 money has been spent by July and China is drawing up its next Five-Year Plan for 2026-2030, will there be more such projects in the future?

In a column for the state-run China News Service this week, Dong Yu, previously Deputy Director-General of the Second Economic Bureau of the Office of the Central Financial and Economic Affairs Commission and, before that, an official at China’s National Development and Reform Commission (NDRC), pointedly said,

In the next step, during the formulation and implementation of the 15th Five-Year Plan, the “two major undertakings” will continue to occupy an important place, be organically incorporated into the new five-year plan, and form close alignment and sustained momentum with major national strategies, major plans, major projects, and key initiatives…

…Such a major strategy will be pursued with persistence—it will not remain rhetorical, nor will it be reversed abruptly.

He did not cite a source of information in his article.

Continuing with his lecturing style, Dong, now Executive Vice Director of China Institute for Development Planning, Tsinghua University, rebuked some unspecified market analysis that had observed the investments just were a one-time boost shot.

Some market institutions once analyzed that when China’s economy was facing short-term difficulties and challenges, the launch of the “two major undertakings” was mainly aimed at expanding investment in the short term to stabilize growth. Such a view clearly lacks a professional understanding of the decision-making intentions and logic, fails to properly grasp the relationship between the short term and the medium-to-long term, as well as between objectives and means, and inverts the proper order of priorities—a misconception that needs to be pointed out and corrected.

Dong also highlighted what he said was the unusual nature of the “strategic move,” including that central government debts fueled the investments, and they were selected “top-down,” rather than primarily relying on local government proposal or input.

The two undertakings were formally submitted for deliberation at the 2024 National People’s Congress after the central leadership made its decision and arrangements…

The central authorities have shown firm determination in this work, adopting the ultra-long-term special treasury bond—a macro policy tool that has rarely been used. Compared with several past issuances of special treasury bonds, the funding arrangement for the “two major undertakings” spans a longer cycle, has a broader scope of application, and will continue to advance in the next stage. It can be said that the scale and intensity are unprecedented. In 2024, a total of 700 billion yuan in ultra-long-term special treasury bonds was allocated, and in 2025, the figure is 800 billion yuan, all of which have now been fully disbursed.

The organization of the “two major undertakings” construction is top-down, completely different from the past practice in the investment sector where projects were determined through bottom-up applications. The purpose is to facilitate the smoother downward transmission of the needs of major national strategies. Relevant [central] government departments, by identifying shortcomings and weaknesses, specifying key areas, and refining project requirements, have ensured that the project list is no longer a collection of fragmented local items. Instead, projects are planned in an integrated manner by category and sector, with strengthened guidance for key regions, more targeted measures, and clearer standards.

Although an exhaustive list of the 1,459 projects does not appear to be available to the public, the “security capacity” build-up in the two major undertakings should be understood in broad terms, and Dong claims the investments put China on a sounder footing globally now that Donald Trump rules America again.

In recent years, the central authorities have emphasized security awareness and bottom-line thinking in development planning, a shift closely related to changes in the international situation. The closer China’s economy becomes intertwined with the global economy, the more comprehensive its considerations must be regarding issues such as food security, energy security, industrial security, and ecological security. The second “undertaking” in the “two major undertakings”—the strengthening of security capabilities in key areas—is precisely a forward-looking arrangement. The dramatic changes in the international environment since the beginning of 2025 have further underscored and confirmed the necessity of enhancing security capabilities, fully demonstrating that the central authorities’ thinking and deployment have been prescient and ahead of the curve.

Dong’s article via China News Service is fully translated below.

中央这一先手棋很不寻常

This Strategic First Move by the Central Authorities Is Highly Unusual

by Dong Yu, Executive Vice President, Institute for China Development Planning, Tsinghua University

The issuance of ultra-long-term special treasury bonds to support the implementation of major national strategies and the building of security capacities in key areas (hereinafter referred to as the “two major undertakings”) has become one of the hottest topics in China’s economy in recent years. Any observation of China’s present and future economic trajectory must include research and analysis of these two undertakings. More than a year has passed since the initiative was launched, making it both necessary and timely to evaluate its effectiveness, understand its operating mechanisms, and look ahead to its prospects.

The “Two Major Undertakings” Are by No Means Ordinary Policy Measures

In terms of decision-making background and process, as well as policy intensity and scope, the launch and implementation of the two major undertakings stand out from other policies. They represent a top-level design initiative.

Understanding a policy starts with its background. From the sequence of events leading to the proposal, this was a proactive, historic choice. The two undertakings were formally submitted for deliberation at the 2024 National People’s Congress after the central leadership made its decision and arrangements. The timing was significant: the 20th Communist Party of China National Congress had laid out a series of major long- and medium-term strategic initiatives that needed concrete engineering projects to push forward. China was midway through two Five-Year Plans, yet strategic advancement could not wait. The central leadership thus introduced the two major undertakings as a groundbreaking initiative.

Strategically, the undertakings directly address the needs of advancing long-term objectives. From the outset, they have been aimed squarely at the goals of Chinese modernization. By breaking down these goals into specific tasks and identifying the most difficult bottlenecks, the undertakings found their points of focus. Some of these tasks might take decades for other countries to achieve, but China has chosen not to delay—tackling them head-on at the starting stage of the new journey toward modernization. This model is uniquely Chinese and has been proven by history to be a key factor in China’s remarkable development successes.

The undertakings are also highly forward-looking—a “first move” by the central leadership. In recent years, national development planning has placed greater emphasis on security and on guarding the bottom line, in response to changes in the international environment. The closer China’s economy is linked to the global economy, the more comprehensive its considerations must be on food security, energy security, industrial security, and ecological security, and other issues. The second “major” in the initiative—security capacity building in key areas—is an arrangement made in anticipation of future challenges. The sharp changes in the international environment since 2025 have only highlighted and validated the necessity of strengthening security capacities, demonstrating that the central leadership’s thinking and arrangements were ahead of the curve.

The undertakings also have a strong overall and systemic quality, constituting a key move in macroeconomic governance. They focus on areas of outstanding importance to economic and social development and have a high degree of relevance to the overall development landscape. The policy toolkit they employ integrates investment, fiscal, science and technology, education, social, and ecological policies. This comprehensive package embodies the use of systems thinking to drive development and will significantly impact all aspects of the economy and society.

A Manifestation of Central Will

Extraordinary measures are for extraordinary tasks. The strategic objectives of Chinese modernization are long-term undertakings, and the two major undertakings provide the foundational support through systematic design and substantial funding.

The central leadership has committed to this initiative by adopting the rarely used macroeconomic tool of ultra-long-term special treasury bonds. Compared with previous special bond issuances, the funding for the two undertakings spans a longer cycle and serves a wider range of purposes, with plans for continued implementation. In both scale and intensity, this is unprecedented: 700 billion yuan in 2024 and 800 billion yuan in 2025, all of which has already been allocated.

In terms of priorities, it vividly reflects the principle of “concentrating resources to accomplish major undertakings.” The focus areas include urban–rural integration, regional coordination, high-quality population development, food security, energy and resource security, ecological security, and self-reliance and strength in science and technology—all crucial to building a strong nation and achieving national rejuvenation. These require coordinated planning and advancement. In just over a year, the high-level requirements have been translated into batches of concrete projects, reflecting the efficiency of implementation.

Project selection is guided by the principle that only the central government can resolve these issues. Some involve urgent development bottlenecks with significant obstacles that cannot be overcome by conventional means, such as scientific and technological breakthroughs, high-standard farmland construction, and upgrading the quality of higher education. Others are long-desired but previously unachievable projects that lack local willingness or capacity to implement, such as major cross-regional infrastructure, cross-basin wastewater treatment, and urban underground utility upgrades.

The organization of the “two major undertakings” construction is top-down, completely different from the past practice in the investment sector where projects were determined through bottom-up applications. The purpose is to facilitate the smoother downward transmission of the needs of major national strategies. Relevant [central] government departments, by identifying shortcomings and weaknesses, specifying key areas, and refining project requirements, have ensured that the project list is no longer a collection of fragmented local items. Instead, projects are planned in an integrated manner by category and sector, with strengthened guidance for key regions, more targeted measures, and clearer standards.

A Combination of “Hard” and “Soft” Measures

From the start, the undertakings were designed not only to fund “hard” engineering projects but also to include comprehensive arrangements for “soft” institutional and policy measures—an important innovation.

The emphasis on soft measures is pragmatic. Given the high importance and public nature of the projects, long-term mechanisms must be designed to ensure smooth progress during construction and sustainable operation thereafter. This includes drafting specialized plans to provide strategic guidance, introducing targeted policies to improve funding efficiency, and innovating institutional arrangements to safeguard implementation.

The implementation process is thus also a process of improving the investment and financing system, updating project management approaches, and enhancing investment effectiveness. In some sectors, soft-measure experiments have had positive impacts, creating healthy interaction with hard investments.

For example, the healthy operation of urban underground pipelines depends on sound maintenance mechanisms. Some local governments have attracted long-term institutional funds into major pipeline projects through debt or equity investment plans, stabilizing private sector returns via operational rights, government subsidies, and tax incentives. Others have introduced province-wide upstream–downstream gas price linkage, set reasonable water supply return rates based on market profits, and advanced the marketization of gas and water prices—reducing losses for public utilities and encouraging private investment.

Similarly, in the quality undergraduate expansion program, mechanisms play a guiding role: schools effectively implementing expansion plans receive increased support, while those performing poorly see reduced support; universities without expanded undergraduate admission plans are generally excluded from special bond funding. Disciplines and programs are adjusted dynamically to align talent training with economic and societal needs.

Directly Relevant to Everyone

The nature of the undertakings is not determined by project size but by their strategic objectives and significance. As long as they align with major national strategies, they are included—whether as large standalone projects, such as high-speed rail along the Yangtze River, or as “project packages,” such as Yangtze River wastewater treatment composed of multiple treatment facilities. This flexible, problem-oriented approach allows better alignment with public needs.

As projects break ground and enter operation, their benefits to people’s livelihoods will become increasingly evident. Observers should not see the undertakings as distant from daily life; they will bring tangible improvements to everyone’s quality of life.

For example:

  • Urban underground pipelines: Upgrades to gas, water, and heating systems will greatly improve safety and resilience. Renovation of old gas pipelines is nearing completion, reducing accident rates by over 30%. Eliminating hidden risks in unseen places increases residents’ sense of security.
  • Food security: Gradually converting all permanent basic farmland into high-standard farmland will stabilize grain output and enhance food safety. Higher standards mean safer products, so people will eat with greater confidence.
  • Yangtze River protection: Building or upgrading over 60,000 kilometers of sewage pipelines in the Yangtze Economic Belt will greatly improve the river’s ecological environment and resolve long-standing public concerns.
  • Transportation: Creating the shortest Shanghai–Chengdu high-speed rail corridor (approx. 1,900 km) will connect the Yangtze River Delta, the middle Yangtze region, and the Chengdu–Chongqing area more quickly, cutting travel time nearly in half and boosting east–west connectivity.
  • Ecological security: Implementing the “Three-North” shelterbelt project over 130 million mu (93 million hectares), with good survival rates for trees, shrubs, and grasses, will safeguard northern ecological security and create new income opportunities.
  • Higher education: “Double First-Class” universities will see markedly improved conditions, with over 500,000 new standard dorm beds. Quality undergraduate enrollment will rise by 16,000 in 2024 and over 20,000 in 2025, giving more students access to quality education and ensuring basic living needs for those from low-income families.
A Bold Stroke in the History of Development

The two major undertakings are a major decision by the CPC Central Committee and the State Council, aimed at the overall strategy of building a strong country and achieving national rejuvenation. They play an irreplaceable role in advancing Chinese modernization.

They are not short-term measures but focus on medium- to long-term development. Some market institutions once analyzed that when China’s economy was facing short-term difficulties and challenges, the launch of the “two major undertakings” was mainly aimed at expanding investment in the short term to stabilize growth. Such a view clearly lacks a professional understanding of the decision-making intentions and logic, fails to properly grasp the relationship between the short term and the medium-to-long term, as well as between objectives and means, and inverts the proper order of priorities — a misconception that needs to be pointed out and corrected.

Since implementation began, the undertakings have provided important support for economic stability. Although their starting point was not short-term growth, the resulting investment has boosted employment and consumption, helping to expand domestic demand and stabilize growth. In the next step, during the formulation and implementation of the 15th Five-Year Plan, the “two major undertakings” will continue to occupy an important place, be organically incorporated into the new five-year plan, and form close alignment and sustained momentum with major national strategies, major plans, major projects, and key initiatives.

They will also bolster the country’s core competitiveness. As foundational support for Chinese modernization, they will strengthen factor security and resolve long-term bottlenecks, with far-reaching significance for shaping China’s development prospects. In an era of intensifying major-power competition, they will provide stable expectations and significantly enhance China’s capacity to manage international uncertainty. Such a major strategy will be pursued with persistence—it will not remain rhetorical, nor will it be reversed abruptly.

Though implementation has only recently begun, the undertakings’ historic role will continue to grow over time. In the future, looking back, they will surely stand as an important part of the “China story” and leave a bold stroke in the history of the People’s Republic’s development.

World-Watching: U.S. Greenlighted H20 Chips Export on Its Own Initiative, China Says

Beijing clarifies its deal with Washington didn’t include NVIDIA’s 4th-best AI chip, disputing widely-reported comments by U.S. Commerce Secretary Howard Lutnick

by Zichen Wang, from Pekingnology

The U.S. greenlighted NVIDIA’s China-specific Artificial Intelligence chip, known as the H20, for export to China on its own initiative, China said on Friday.

In a statement dedicated to the recent U.S. approval of the semiconductor giant’s 4th-best Artificial Intelligence chip, China’s Ministry of Commerce said on its website that in early July, the U.S. had already lifted restrictions on China under the agreement reached between the two countries in London.

“We have taken note that Washington has now taken the initiative to announce it will authorize sales of NVIDIA’s H20 chips to China,” the trade ministry added.

Beijing’s clarification stands in stark contrast to widely reported public comments earlier this week by U.S. Commerce Secretary Howard Lutnick, who told Reuters on Tuesday that “We put that in the trade deal with the magnets,” referring to the agreement made to restart Chinese rare earth shipments to U.S. manufacturers. He did not provide additional details, according to Reuters.

NVIDIA’s H20 was designed to be technologically inferior. The company also sells three other chips that far surpass the H20’s power.

Commerce Secretary Howard Lutnick echoed NVIDIA CEO Jensen Huang’s view of why a U.S. company should sell chips to China. Andrew Harnik/Getty Images

On Monday, July 14, the Silicon Valley company announced in a blog post that the U.S. government had approved the sale of the H20, three months after the Donald Trump administration shut down NVIDIA’s artificial intelligence chip sales to China, after CEO Jensen Huang met President Trump in Washington D.C., and before he departed for Beijing.

Huang dominates Chinese headlines this week with his speech at an industry conference and public events with Chinese AI leaders. He visited China’s Ministry of Commerce and was received by Wang Wentao, the minister, on Thursday.

商务部新闻发言人就美批准对华销售英伟达H20芯片有关情况答记者问

MOFCOM Spokesperson Responds to Questions on the U.S. Approval of NVIDIA H20 Chip Sales to China

2025-07-18 13:43

Question:

U.S. officials have recently stated that Washington’s decision to approve sales of NVIDIA’s H20 chips to China is part of China–U.S. economic and trade negotiations. They also claimed that Chinese firms, including Huawei, are already producing equivalent chips domestically and that the United States does not want China to achieve full import substitution. How does the Ministry of Commerce (MOFCOM) view this?

Answer:

Following the China–U.S. economic and trade consultations in London, the two sides have maintained close communication, finalized the “London framework,” and moved forward with implementation. China, in accordance with its laws and regulations, approves export applications for controlled items that meet the necessary criteria. In early July, the United States reciprocally lifted the restrictions on China that had been discussed during those talks.

We have taken note that Washington has now taken the initiative to announce it will authorize sales of NVIDIA’s H20 chips to China. Beijing believes the United States should abandon a zero-sum mentality and continue to roll back a range of unwarranted trade and technology restrictions on China.

Cooperation and mutual benefit are the only viable path; suppression and containment lead nowhere. In May, the United States issued new export-control guidelines targeting Huawei’s Ascend chips, tightening restrictions on Chinese semiconductor products under unfounded pretexts. By wielding administrative power to distort fair market competition, these measures severely undermine the legitimate rights and interests of Chinese companies. China has made its position clear and firmly opposes such actions.

We look forward to the United States working with China in a spirit of equality to correct these erroneous practices, foster a sound environment for mutually beneficial cooperation between the two countries’ enterprises, and jointly safeguard the stability of global semiconductor supply chains.

Kierkegaard and Existence

There are various striking intuitions about human existence. For example, in his brilliant memoirs, Speak, Memory, Nabokov begins with the deep reflection where human existence is compared to a baby in a cradle, rocking, completely vulnerable and uncertain. All of this is bracketed by two episodes of infinite darkness. The first episode took place before you were born and the second takes place after you’re gone. Your existence is a temporary flame, like that of a lit match.

A MetaIntelligent comment on this would be that the profound ingenuity of the 19th century mathematicians analyzing the size and nature of infinity (e.g., Richard Dedekind or Georg Cantor) cannot in the last analysis wrestle down human existence into mathematics.

The modern progenitor of this kind of human existence-watching is the Danish genius Søren Kierkegaard. In one of his masterpieces, Concluding Unscientific Postscript to Philosophical Fragments (1846), he makes the claim that knowledge, theory, speculative thinking and infinity-watching à la Dedekind and Cantor, cannot possibly explain human existence, because it subsumes all of these.

In 2025, this would mean that the Kierkegaard sense of things would tell you that neuroscience can never really explain how existence is sensed by a living person.

Kierkegaard writes, “in my view the misfortune of the age was precisely that it had too much knowledge, had forgotten what existence means, and what inwardness signifies.” He continues, “for a knowledge-seeker, when he has finished studying China he can take up Persia; when he has studied French he can begin Italian; and then go on to astronomy, the veterinary sciences, and so forth, and always be sure of a reputation as a tremendous fellow.”

By way of contrast, “inwardness in love does not consist in consummating seven marriages with Danish maidens, then cutting loose on the French, the Italian, and so forth, but consists in loving one and the same woman, and yet being constantly renewed in the same love, making it always new in the luxuriant flowering of the mood.” (Concluding Unscientific Postscript to Philosophical Fragments, page 232.)

Kierkegaard’s kind of existence-watching can be understood as a turning-upside-down of the famous phrase from Descartes, “I think, therefore I am.” For Kierkegaard, “I am, therefore I think.” Notice that “I think” is an epistemological statement or knowledge-watching. “I am” is an ontological statement.

This existentialist tradition of putting ontology before epistemology finds its culmination in Heidegger. As he says in his opus, Being and Time (1927), “human being is ultimately the being for whom being itself is an issue.”

Heidegger vs. Marx as World Watchers

Marx (1818-1883) implies that the foundation of human reality is econo-technical, and on that basis society creates thoughts and philosophies, art and poems. This explanation seems appealing when we think of the economic development of China in our time, for example, or the rise of computers and software.

In a way, Heidegger (1889-1976) turns this upside down. At the basis of world history is society producing culture. You can make a simple “cartoon” and say that for Marx, economics shapes everything, and for Heidegger culture replaces economics.

For example, in his book, What Is Called Thinking? (English translation, 1968, Harper & Row), Heidegger argues the foundation of all Western thinking and culture comes from axioms such as logos [Ancient Greek: λόγος] (from which we have logic, cosmology, psychology, epistemology, etc.), as well as legein (the Greek verb λέγειν, “to speak”).

Heidegger states (on page 204), “Without the λέγειν of that logic, modern man would have to make do without his automobile. There would be no airplanes, no turbines, no Atomic Energy Commission.”

Our MI comment on this is that any monocausal explanation of how mankind went from Neanderthal to the Manhattan skyline is completely inadequate. You must create a “double-helix” of Marx and Heidegger, adding the dimensions of surprise and unintended consequences. Without the physics concepts of emergence and complexity, we have no possibility of understanding how we got to now. In the site tagline, we use the word “composite” as a reference to this kind of deeper understanding.

“De-Globalization?”

The classic study of the “swirl of processes and events” that ended previous globalization episodes is the theme of Princeton Professor Harold James’ 2002 book, The End of Globalization: Lessons from the Great Depression.

“Globalization” is here. Signified by an increasingly close economic interconnection that has led to profound political and social change worldwide, the process seems irreversible. In this book, however, Harold James provides a sobering historical perspective, exploring the circumstances in which the globally integrated world of an earlier era broke down under the pressure of unexpected events.

James examines one of the great historical nightmares of the twentieth century: the collapse of globalism in the Great Depression. Analyzing this collapse in terms of three main components of global economics—capital flows, trade and international migration—James argues that it was not simply a consequence of the strains of World War I, but resulted from the interplay of resentments against all these elements of mobility, as well as from the policies and institutions designed to assuage the threats of globalism.

Could it happen again? There are significant parallels today: highly integrated systems are inherently vulnerable to collapse, and world financial markets are vulnerable and unstable.

While James does not foresee another Great Depression, his book provides a cautionary tale in which institutions meant to save the world from the consequences of globalization—think WTO and IMF, in our own time—ended by destroying both prosperity and peace.

Legitimate fears about “globalization reversal” have been well put by Zakaria:

Davos, Switzerland —

President Trump’s speech here at the World Economic Forum went over relatively well. That’s partly because Davos is a conclave of business executives, and they like Trump’s pro-business message. But mostly, the president’s reception was a testament to the fact that he and what he represents are no longer unusual or exceptional. Look around the world and you will see: Trump and Trumpism have become normalized.

Davos was once the place where countries clamored to demonstrate their commitment to opening up their economies and societies. After all, these forces were producing global growth and lifting hundreds of millions out of poverty. Every year, a different nation would become the star of the forum, usually with a celebrated finance minister who was seen as the architect of a boom. The United States was the most energetic promoter of these twin ideas of economic openness and political freedom.

Today, Davos feels very different. Despite the fact that, throughout the world, growth remains solid and countries are moving ahead, the tenor of the times has changed. Where globalization was once the main topic, today it is the populist backlash to it. Where once there was a firm conviction about the way of the future, today there is uncertainty and unease.

This is not simply atmospherics and rhetoric. Ruchir Sharma of Morgan Stanley Investment Management points out that since 2008, we have entered a phase of “deglobalization.” Global trade, which rose almost uninterruptedly since the 1970s, has stagnated, while capital flows have fallen. Net migration flows from poor countries to rich ones have also dropped. In 2018, net migration to the United States hit its lowest point in a decade.

The shift in approach can best be seen in the case of India. In 2018, Prime Minister Narendra Modi came to Davos to decry the fact that “many countries are becoming inward focused and globalization is shrinking.” Since then, his government has increased tariffs on hundreds of items and taken steps to shield India’s farmers, shopkeepers, digital companies and many others from the dangers of international competition. The Office of the U.S. Trade Representative recently called out India for having the highest tariffs of any major economy in the world.

Indian officials used to aggressively court foreign investment, which was much needed to spur growth. Last week, with India’s economy slowing badly, Jeff Bezos announced a $1 billion investment in the country. (Bezos owns The Post.) But the minister of commerce and industry scoffed at the move, saying Amazon wasn’t “doing a great favor to India” and besides was probably engaging in anti-competitive, “predatory” practices. Often, protectionist policies help favored local producers. Malaysian Prime Minister Mahathir Mohamad recently criticized some of Modi’s policies toward Muslims. The Indian government effectively cut off imports of Malaysian palm oil. In a familiar pattern, one of the chief beneficiaries was a local billionaire long associated with Modi.

The Economist notes that Europe, once one of the chief motors for openness in economics and politics, is also rediscovering state intervention to prop up domestic industries. And if you think the Internet is exempt from these tendencies, think again. The European Center for International Political Economy tracks the number of protectionist measures put in place to “localize” the digital economy in 64 countries. It has been surging for years, especially since 2008.

It’s important not to exaggerate the backlash to globalization.

As a 2019 report by DHL demonstrates, globalization is still strong and, by some measures, continues to expand. People still want to trade, travel and transact across the world. But in government policy, where economic logic once trumped politics, today it is often the reverse. Economist Nouriel Roubini argues that the cumulative result of all these measures — protecting local industries, subsidizing national champions, restricting immigration — is to sap growth. “It means slower growth, fewer jobs, less efficient economies,” he told me recently. We’ve seen it happen many times in the past, not least in India, which suffered decades of stagnation as a result of protectionist policies, and we will see the impact in years to come.

Nevertheless, today, nationalism and protectionism prevail.

This phase of deglobalization is being steered from the top. The world’s leading nations are, as always, the agenda-setters. The example of China, which has shielded some of its markets and still grown rapidly, has made a deep impression on much of the world. Probably deeper still is the example of the planet’s greatest champion of liberty and openness, the United States, which now has a president who calls for managed trade, more limited immigration and protectionist measures. At Davos, Trump invited every nation to follow his example. More and more are complying.

“The world is de-globalizing. Trump set the example.” The Washington Post, Fareed Zakaria

Students should sense that while history does not repeat itself, it sometimes rhymes and this is a major danger. It also might imply that coping with climate change will be all the harder because American-led unilateralism everywhere would mean world policy paralysis.

World-Watching: Container Shipping Financial Insight, Nov. 2023

[from Drewry Shipping Consultants]

Driven by weak 3Q23 financial results, the Drewry Container Equity Index decreased 3.7% last month (as of 22 Nov 2023). Additionally, asset prices continue to fall due to the supply-demand imbalance.

  • Container shipping companies’ 3Q23 financial results showcased a sharp dip in profits or even losses. On a group level, eleven liners (which report quarterly results) among our portfolio of 13 companies reported an average slump of 54.6% YoY in their 3Q23 topline. Operating costs declined 18.1% YoY amid falling chartering costs and lowering bunker prices. However, the cost reduction was insufficient to offset the plunge in topline; thus, EBIT contracted 94.1% YoY on average.
  • The Drewry Container Equity Index tumbled 28.1% YTD 2023 (ending 22 November), driven by lowering freight rates (WCI: -30.7% in YTD 2023), which squeezed earnings over the quarters. On the contrary, the S&P 500 posted an 18.4% growth. The Drewry Container Equity Index declined 3.4% in the month ending 22 November 2023. Talking about equity prices individually, APMM’s stock price fell 9.0% amid EBIT loss for its Ocean segment in 3Q23, staff cuts and reduced capex guidance, highlighting APMM’s efforts toward reducing costs faced with the bleak industry outlook. Hapag-Lloyd’s stock price slumped 22.2% as its EBIT margin (3Q23: 5.1%) slid below its pre-pandemic level (3Q19: 7.8%). ZIM became the first carrier to report impairment of assets worth USD 2.0bn in 3Q23, and its stock price fell 18.1%. Meanwhile, China-exposed container companies benefitted from the positive sentiment arising from the proposed fiscal stimulus by the Chinese government, possibly boosting the out-of-China and intra-Asia trades. Asian stocks in the broader index rose 2.0% to 19.4% in the month ending 22 November 2023.
  • Mainly driven by weak earnings prospects, the Drewry Container Equity Index trades at a P/B of 0.5x, a 47.5% discount to its pre-pandemic average (2013-19). We expect freight rates to fall sharply in 2024 and increasingly incur losses. Thus, we expect the multiple to remain suppressed.
  • As the fleet of container shipping companies expands, the charter market softens. For instance, 1-year TC rates declined 14.2% and 52.5% YoY in October for vessels sized 1,110 teu and 8,500 teu. Rates declined more for larger vessels as these constitute the majority of the order book and new deliveries. The YoY decline has continued since October 2022, but rates improved slightly during April-May 2023. However, this was not due to the fundamentally strong market but MSC and CMA CGM’s aggressive chartering of vessels to expand their fleets. Now that the two companies have stopped chartering in vessels, the charter market continues to decline.
  • Driven by the softening charter market, second-hand asset prices are also weakening. In October, on a YoY basis, prices for five-year-old vessels (2,700 teu and 7,200 teu) contracted 30.6% and 31.5%, and for 10-year-old ships, prices tumbled between 36.7% and 53.2%. Contrary to the sale and purchase market, newbuild prices (1,500 teu and 14,000 teu) continue to increase and rose by an average of 2.2% YoY, led by a shortage of capacity in shipyards.
  • The charter market and the S&P market have a direct impact on container shipping companies’ earnings. Costs related to chartering-in slots or vessels from other non-operating vessel owners form a significant portion of container shipping companies’ cost structure. In the 3Q23 results, this cost was reduced,
    marginally relieving downside pressure on the operating margin of container shipping companies. In line with the declining charter market, we expect this trend to continue in 4Q23. We also expect other companies to follow ZIM in reporting impairment losses as prices for older vessels continue to fall.

Read the report [archived PDF] for additional graphs.

Zheng Yongnian (郑永年) on How to Address Western Public Opinion on China: Facts, Science and Reason

[from Pekingology at the Center for China and Globalization (CCG)]

“Be open, open, and more open,” especially to businesses, investors, media, universities, and research institutions. And tit-for-tat doesn’t work, the professor says.

by Zichen Wang, Shuyuan Han, and Li Huiyan

Professor Zheng Yongnian (郑永年), the Founding Director of the Institute for International Affairs at the Chinese University of Hong Kong, Shenzhen, on January 28 published an article on how China should address Western public opinion on China. His advice is in the last part of the article, and below is a translation.

(Emphasis by Pekingnology.)

First, we need to understand how such narratives are formed. Historically, China held a bias due to its self-isolation and limited knowledge of the West. Despite losing the two Opium Wars, Chinese intellectuals at that time still saw Westerners as uncivilized. It was not until China was defeated by Japan, a neighboring country once considered as China’s student, that they realized their ignorance and a need for reform. Before China’s Reform and Opening up, Chinese people barely knew anything about the West. They always assumed Westerners were in deep distress, repeating the same lack of understanding of the West.

Similarly, the West’s uncertainty and fear towards China’s rise stem from a lack of understanding and even fear of the country, and their ingrained ideology would lead to misconceptions.

China is the world’s second-largest economy. The externalities and influence of its economy on the West are obvious. Upon joining the WTO, some Chinese people also felt unsettled by the externalities of the West. Some said, “the wolf is coming.” Now it is the West that is experiencing such worries.

It is crucial to recognize the significant impact of the Western hypocritical narratives against China, even if they are based on ideology rather than facts. We must also acknowledge that ideology-based public opinion from the West can exert a powerful influence on their policies toward China.

Historically, the West tended to demonize others while presenting themselves as morally superior, which enabled them to apply Social Darwinism to international politics easily and thus legitimizing conflicts and even wars with other nations. Given the Soviet Union’s failure in the ideological arena during the Cold War, we should by no means ignore any ideology-based public opinion toward China from the West.

Second, to make rational responses to the Western ideology-based criticisms, we should draw lessons from the history of the world economy, such as the lessons of the Soviet Union, as well as our practices, such as the rhetorical battle with the West in the past few years. Coming up with an externally-facing public opinion based on a different ideology is not the most effective in addressing public opinion attacks based on an ideology. Empirically, tit-for-tat is ineffective and can worsen the situation. Again, the failure of the Soviet Union is a prime example, as its battle with a Western ideology failed. When faced with China-demonizing based on ideology from the West, we need to do the simplest thing, namely resorting to facts, science, and reason.

Third, and most importantly, China needs to prioritize its sustainable development, which ultimately benefits the country itself. It is important to recognize that the foundation of the government’s governance lies in its citizens, not Western praise. The support from its people is crucial for both the nation’s longevity and stability., China’s sustainable development also benefits the world economy by boosting its growth. As mentioned above, China has been the largest contributor to the growth of the world economy since it joined the WTO.

It is crucial to prioritize the building of a knowledge system based on China’s practical experiences. Regarding global soft power, we need a knowledge system based on our experiences rather than a certain ideology. While there has been a proposal for an autonomous knowledge system, continuous effort is still required.

Fourth, given the substantial externalities of our economy, we must further communicate and coordinate with other countries on economic policies, regardless of their respective sizes. Our duty is to fulfill the responsibility as a major player in the international community, which also benefits China.

After the 1997-1998 Asian financial crisis, China promised not to devalue its currency, and that commitment became an international public good in Asia. Similarly, after the global financial crisis from 2007 to 2008, China made similar contributions. As China re-opens its economy after the pandemic, it is important not only to take note of the hypocritical comments from certain quarters in the Western world but also to recognize the positive evaluations and high expectations from many international organizations.

Fifth, we must be open, open, and more open. Despite China’s efforts, there remains a persistent ideological camp in the West that views China through an ideological lens, a situation made worse by the past three years of the pandemic. The pandemic was so severe that it hindered travel across borders; as a result, some Western media and scholars tend to assess China through ideology since they couldn’t come here to see the facts with their own eyes.

The assessment of China through a uniform ideological lens appears to have strengthened the original Western ideological camp. However, the United States and the West have more than one ideology, and not all people believe in the prevailing ideology in the public opinion sphere. China’s openness provides a “seeing is believing” opportunity for different groups in the West. China should increase its openness to Western groups, including businesses, investors, media, universities, and research institutions. The changes in their understanding could render those ideological-based public opinions less effective.

Facing the Global South: Building a New International System by Yang Ping

“If you raise [the development of the BRI] to the strategic level, there are countries where … you will have to lose money and there are countries where you will be free to make money.”

by Thomas des Garets Geddes, Sinification

Dear Everyone,

How to respond to the growing political divide between China and the West marked by partial decoupling, security alliances, and the risk of sanctions, amongst other things, continues to be a major topic of discussion among China’s intellectual elite. As already evidenced in previous editions of this newsletter, opinions vary considerably. Those presented here so far have ranged from Da Wei (达巍) stressing the importance of preserving if not strengthening ties with the West and Shen Wei (沈伟) arguing in favor of reforming the WTO and building up a network of free trade agreements to Ye Hailin (叶海林) emphasizing the need for China to demonstrate its military might to demobilize U.S. allies and Lu Feng (路风) calling for self-reliance and greater assertiveness in the field of tech. A certain amount of overlap certainly exists among these perspectives but the differences are nonetheless striking.

Today’s edition of Sinification looks at a speech made last month by Yang Ping (杨平), head and editor-in-chief of the highly regarded Beijing Cultural Review (文化纵横, hereafter BCR). Yang is also director of the Longway Foundation (修远基金会) which publishes BCR. The foundation describes its publication as “the most influential magazine of intellectual thought and commentary in China” and sees itself as having a key role in helping shape the direction of intellectual debates in China (“议题的设置就是意识形态斗争成功的一半”). Indeed, BCR often republishes old articles at key junctures as so often highlighted by David Ownby’s wonderful Reading the China Dream.

The following are excerpts from an edited transcript of a speech by Yang made at an event hosted by Renmin University’s Chongyang Institute for Financial Studies, which was attended by China’s Vice-minister of foreign affairs Xie Feng (谢锋). In his speech, Yang advocates building a new international system led by countries in the Global South (which, of course, includes China) rather than the West. His ideas are not particularly novel but are nevertheless noteworthy in that they represent yet another viewpoint in the ongoing debate over how China should respond to the increasing tensions that characterize its relations with the U.S. and other Western countries. Next week, I will be sharing a somewhat longer piece that proposes a way of protecting China from the growing threat of Western sanctions.

Yang’s speech in a nutshell:

  • “Capitalist politics” are no longer in line with “capitalist economics.” The former now undermines globalization, while the latter supports it.
  • Sanctions, export controls, friend-shoring and alliance-building are damaging the world economy and further alienating China from the current U.S.-led international order.
  • China must respond to this growing trend by building a “new type of international system” with other countries in the Global South.
  • BRI projects should be increasingly focused on achieving this goal and thus allow more room for loss-making endeavors.

Capitalist politics ≠ Capitalist economics

“Since 2022 and the Russo-Ukrainian conflict, our main focus and topic of discussion has been China’s construction of a new type of international system.

“The most important feature of today’s world is the beginning of a separation between capitalist politics and capitalist economics. The capitalist political order and the capitalist economic order do not support each other [any longer].

“We have witnessed two typical manifestations of the separation of politics and the economy and the impact of politics on the economy:

  1. The first is the conflict between Russia and Ukraine. The sanctions imposed on Russia by the United States and the West have reached unthinkable, abominable [令人发指] and unimaginable proportions. Under established international rules, it was understood that such sanctions could not possibly occur, but now they have. These include the fracturing of the financial system, the expropriation and seizure of Russian private assets and the freezing of Russian foreign exchange reserves. These are all abominable and unimaginable forms of confrontation. At the same time, the Russo-Ukrainian conflict has led to serious disruptions in global food and energy systems and supply chains, with massive food ‘shortages’ and soaring food prices, particularly in developing countries. Sanctions and political repression [政治打压] have severely disrupted the [world’s] economic order.
  2. The second is the conflict between the U.S. and China. Since the Trump era, the U.S. has been engaged in a trade war against China, mainly by raising tariffs. Basically, this was simply about balancing trade [with China] and used mainly economic means. But under Biden, it [has become] a war that mixes politics with economics. Biden’s strategy towards China can basically be summed up in just a few words: one, friend-shoring, [i.e.] only allowing friendly countries into [parts of] its supply chains; two, alliance politics, [i.e.] continuously forging an alliance system involving NATO, the European Union, Japan, AUKUS and the four Asia-Pacific countries [I assume he is referring to South Korea, Japan, New Zealand and Australia taking part for the first time in a NATO summit last year] and constantly opposing China [不断应对中国]; three, its so-called ‘precision strikes’, [i.e.] its radical crackdown on China’s high tech [industry], especially our chip industry.”

China is being pushed out of the U.S.-led international system

“The information I have seen so far is that the number of Chinese companies included in the U.S.’s ‘entity list’ has risen from 132 under Trump to over 530 now. The scope of such point-to-point [点对点] precision strikes is constantly expanding. With such a political impact on the economy, we can feel the [world’s] economic order being disrupted across the board. The world is moving inexorably in the direction of decoupling. The phenomenon of politics affecting the economy and the capitalist political order no longer upholding the capitalist economic order are extremely striking.

“In such a context, the challenges now facing China are extremely serious and varied. We have the pressures of dealing both with containment in the Indo-Pacific and with the U.S.-led politics of alliances across the world. More importantly and fundamentally China faces the strategic task of building a new type of international system [新型国际体系] … The existing Western-dominated international system used to be one in which we tried hard to blend [so as] to become one with it. During this process, we [sought to] absorb the West’s advanced technologies and management [practices] and thus complete our mission of industrialisation and modernization.

“But once you enter the existing international system, he [who is already inside] does not want to play with you, and even wants to drive you back out. He wants to divide both supply chains and the economic system into two parts [搞成两套] and desperately wants to contain and suppress you. This is not something that can be determined by your own subjective preferences. He has made up his mind: you have already become his ‘fated opponent’ [命定的对手]. He has to suppress you and drive you out of the existing system.”

Building a new international system with the Global South

“It is at this point that China is faced with the task of constructing a new type of international system that is not dominated by the West. In today’s so-called strategic quadrangle consisting of the U.S., Europe, Russia and China, how to construct such an international system appears particularly difficult [逼庂 literally means ‘narrow’ or ‘cramped’ rather than ‘difficult’].

“But if we look a little further south, we will find a vast number of developing countries, the Third World and the countries of the global South. They should be our strategy’s depth [我们的战略纵深]. That is to say, [we should] build a new type of international relations and a new type of international system that has strategic depth and in which China and the countries of the global South are jointly integrated. [This] is, in my view, an important strategic task for China’s international relations in the coming decades.”

BRI projects: Strategy trumps profitability

“For China today, especially for businesses and governments at all levels [within China] that are currently working hard to develop BRI trade, there is a very important point to which they should be alerted or reminded about: the development of the BRI has to go beyond mere business, beyond the general export of [China’s excess] production capacity, beyond the partial thinking of industry and the partial thinking at the regional level, or the simple economic way of thinking of business. The development of the BRI should be considered at the strategic level. That is, it should be included into China’s strategy when thinking about Africa, South America, Southeast Asia and Central Asia.

“If you raise [the development of the BRI] to the strategic level, there are countries where you won’t be able to make money and will have to lose money, and there are countries where you will be free to make money. You have to unite the two within your organic strategy.

“The strategic task of building a new type of international system is, in my view, a strategic proposition that Chinese think tanks and research institutes should pay very close attention to with regards to international relations.

“Time is limited today. I just wanted to make a start here. I hope to receive your corrections and criticisms. Thank you!”

[Subscribe to Sinification]

The recessive importance of the Global South was previously explored by Richard and his partner Larry, with input from Supratik Bose, many decades ago as shown here.

Globalization and Its Nuances

The PBS TV program History Detectives had an episode entitled “Atocha Spanish Silver” where the wreck of the Spanish ship Atocha was described like this:

“In 1985, one of the greatest treasure discoveries was made off the Florida Keys, when the wreck of the Spanish ship Atocha was found. On board were some forty tons of silver and gold, which in 1622 had been heading from the New World to the Spanish treasury as the means to fund the Thirty Years’ War.”

Is this an obvious case of globalization? What about Marco Polo? Rome–Han dynasty China trade in silks? Silk Road and Samarkand? Colombus? Magellan? Vasco da Gama?

All of these cases constitute a kind of harmless kind of “pop globalization” based on exotic voyages and travels.

Consider another such example, perhaps more academic:

“About the middle of the sixteenth century Antwerp reached its apogee. For the first time in history there existed both a European and a world market; the economies of different parts of Europe had become interdependent and were linked through the Antwerp market, not only with each other but also with the economies of large parts of the rest of the world. Perhaps no other city has ever again played such a dominant role as did Antwerp in the second quarter of the sixteenth century.”

(Europe in the Sixteenth Century, Koenigsberger and Mosse, Holt Rinehart Publishers, 1968, page 50)

Debt repudiations in several places in the 1550s are described like this:

“This caused the first big international bank crash, for the Antwerp bankers now could not meet their own obligations.”

(Europe in the Sixteenth Century, Koenigsberger and Mosse, Holt Rinehart Publishers, 1968, page 51)

This sounds like some kind of identifiably global period.

Actually, modern historians define globalization as “price convergence” (i.e., wheat has now a unified “world price,” implying a world market). This rigorous definition is confirmed by and also shows up in the data in the 1820s and may or may not be prefigured by all the Marco Polo and Atocha silver stories, mentioned above.

These episodes in history are not there yet.

One sees wheat prices and other commodity prices converging in the 1820s and thereafter based on railroads, steamships and telegrams.

The classic in this kind of analysis is:

Globalization and History: The Evolution of a Nineteenth-Century Atlantic Economy, by Kevin O’Rourke and Jeffrey Williamson.

Kevin O’Rourke and Jeffrey Williamson present a coherent picture of In Globalization and History, Kevin O’Rourke and Jeffrey Williamson present a coherent picture of trade, migration, and international capital flows in the Atlantic economy in the century prior to 1914—the first great globalization boom, which anticipated the experience of the last fifty years. The authors estimate the extent of globalization and its impact on the participating countries, and discuss the political reactions that it provoked. The book’s originality lies in its application of the tools of open-economy economics to this critical historical period—differentiating it from most previous work, which has been based on closed-economy or single-sector models. The authors also keep a close eye on globalization debates of the 1990s, using history to inform the present and vice versa. The book brings together research conducted by the authors over the past decade—work that has profoundly influenced how economic history is now written and that has found audiences in economics and history, as well as in the popular press.

(book summary)

In everyday language, we associate the word globalization with some ever-increasing Marco Polo phenomena. While that’s not entirely wrong, globalization in the more technical sense begins to show up in the data only from the 1820s. At this point, we begin to see the convergence of worldwide wheat prices, for example. This makes the world, for the first time, a global “store” with unified prices. Here is the technical beginning of globalization. The years 1870-1914 are subsequently the first real era of modern globalization and represent a kind of “take-off” from the first stirrings of the 1820s. World Wars I & II might be seen as globalization backlash.

At this moment in world history, whether Putin’s invasion of Ukraine will constitute a new wave of deglobalization remains to be seen.