Economic-Watching: Fourth District Beige Book

[from the Federal Reserve Bank of Cleveland, 3 September 2025]

Summary of Economic Activity

Fourth District contacts reported a slight increase in overall business activity in recent weeks and expected activity to rise modestly in the months ahead. Consumer spending was flat, with retailers noting continued affordability concerns among consumers. Manufacturers also reported flat demand for goods, citing trade policy uncertainty as the main driver. Demand for professional and business services grew moderately, albeit at a slower pace than in the past three reporting periods. Contacts generally reported flat employment levels and modest wage pressures. Nonlabor cost pressures remained robust, and selling prices continued to grow modestly.

Read the full report [archived PDF].

Economics-Watching: Neutral Interest Rates and the Monetary Policy Stance

[from the Federal Reserve Bank of Cleveland, 2 September 2025]

by Taylor Horn & Saeed Zaman

The neutral interest rate (r-star) is an important input in monetary policy discussions and is commonly used to assess the stance of monetary policy. This Economic Commentary presents estimates of the neutral interest rate from a recently developed model and provides a high-level description of this new model. With data through 2025:Q2, the model estimates the implied (medium-run) nominal neutral interest rate to be 3.7 percent, with a 68 percent coverage band ranging from 2.9 percent to 4.5 percent. Given that the effective nominal federal funds rate is currently in the range of 4.25 percent to 4.5 percent, this model estimates with a high level of certainty (77 percent probability) that the policy stance is in restrictive territory.

Read the full article [archived PDF].

Economics-Watching: Will Tariffs Touch Off an Inflationary Impulse? Business Execs Think So.

[from Federal Reserve Bank of Atlanta, 21 August 2025]

Summary

Following the inflationary surge from 2021 to 2023, which was touched off by supply chain constraints and shipping bottlenecks, we evaluate a new panel of own-firm price and unit cost growth expectations in the Atlanta Fed’s Survey of Business Uncertainty for signs that the anticipated impact from tariffs is broadening beyond directly affected firms. We find evidence for the potential of tariffs to touch off another bout of high inflation. First, firms that are directly exposed to tariffs have increased their year-ahead price growth expectations sharply (by 0.7 percentage points). Second, firms that are not directly exposed to tariffs but are operating in industries that are highly exposed to tariffs anticipate a moderately higher trajectory for year-ahead price growth (0.3 percentage points). Third, this broadening of overall price pressures—a key feature of the pandemic-era inflationary impulse—is only partially offset by lower price increases from tariff-exposed firms that are operating largely in industries not exposed to tariffs.

Key Findings

  1. Firms, en masse, have increased their year-ahead price growth expectations since the end of 2024. This is especially true for firms directly exposed to tariffs.
  2. We find evidence of a broadening out of the influence of tariffs beyond those directly exposed. Unexposed firms in exposed industries anticipate a moderately higher trajectory of year-ahead price growth.
  3. The broadening of anticipated price growth is only partially offset by lower price growth expectations among tariff-exposed firms that are operating in largely unexposed industries.

Read the full article [archived PDF]

Economics-Watching: Drewry Container Shipping Financial Insight, August 2025

[from Drewry Shipping Consultants, 22 August 2025]

Container shipping companies have reported mixed 2Q25 results. Read the article [archived PDF] for key takeaways from 2Q25 results and other key developments shaping the container shipping sector.

About Drewry Maritime Financial Research

Drewry Maritime Financial Research (DMFR), is the marketing name of Drewry Financial Research Services Ltd. DMFR, is an independent equity research service focused on the maritime industry. DMFR’s parent organisation, Drewry Shipping Consultants Holdings Limited was established more than 50 years ago and is now widely regarded as one of the leading independent sources of global industry analysis and insight. This in-depth industry knowledge is fully applied in our analysis of quoted maritime companies.

Economics-Watching: BIS Alerts for 18 August 2025

[from the Bank for International Settlements]

An Approach to Anti-Money Laundering Compliance for Cryptoassets

BIS Bulletin № 111 (13 August 2025)

by Iñaki Aldasoro, Jon Frost, Sang Hyuk Lim, Fernando Perez-Cruz & Hyun Song Shin

Key takeaways
  • Existing anti-money laundering (AML) approaches relying on trusted intermediaries have limited effectiveness with decentralized record-keeping in permissionless public blockchains.
  • The public transaction history on blockchains can enable AML and other compliance efforts, such as FX regulations, by leveraging the provenance and history of any particular unit or balance of a cryptoasset, including stablecoins.
  • An AML compliance score based on the likelihood that a particular cryptoasset unit or balance is linked with illicit activity may be referenced at points of contact with the banking system (“off-ramps”), preventing inflows of the proceeds of illicit activity and supporting a culture of “duty of care” among crypto market participants.

Read the full article [archived PDF]

Macroeconomic Impact of Tariffs and Policy Uncertainty

BIS Bulletin № 110 (12 August 2025)

by Emanuel Kohlscheen, Phurichai Rungcharoenkitkul, Dora Xia & Fabrizio Zampolli

Key takeaways
  • Tariffs affect economies most directly through trade volume and prices. Tariffs lower output growth everywhere, though the magnitude varies by country and scenario. They also tend to raise inflation, most notably in the imposing countries.
  • Tariffs have indirect effects, including exchange rate shifts, supply chain disruptions, trade diversion and heightened uncertainty. These could worsen growth and inflation effects as well as the policy trade-offs central banks face.
  • If it proves persistent, trade policy uncertainty could depress domestic demand and put global growth at risk.

Read the full article [archived PDF]

Economics-Watching: Why Businesses Say Tariffs Have a Delayed Effect on Inflation

[from the Federal Reserve Bank of Richmond, 8 August, 2025]

by R. Andrew Bauer, Renee Haltom and Matthew Martin

Regional Matters

Ever since new tariffs were enacted in early 2025, a key policy question has been what is the extent to which businesses will pass tariff costs through to prices, and when? The effects of a tariff are rarely straightforward, given, among other things, competitive dynamics and the challenges of implementation, but the historically large and changing nature of these tariffs have created additional levels of uncertainty over the effects.

In uncertain times, anecdotal evidence from businesses can be especially insightful. We are learning how businesses are reacting to tariffs through the Richmond Fed’s business surveys as well as through hundreds of one-on-one conversations with Fifth District businesses since the start of 2025.

These conversations showcase that navigating tariffs is a complex and sometimes protracted process for firms, particularly when there is uncertainty. Firms describe several reasons they may not have experienced the full impact of proposed tariffs yet (even when goods and countries they deal with are subject to them), as well as reasons that even when they have incurred tariff-related cost increases, there can be a delayed impact on pricing decisions.

Reasons Firms May Not Have Incurred Tariffs Yet

Business contacts describe several strategies or circumstances that can delay or reduce the tariffs on inputs or other imported items. These include the following:

As our monthly business surveys have found, many firms report deploying more than one strategy to delay tariffs. Notably, many of these delays are only temporary.

Reasons Tariffs May Have a Delayed Impact on Prices

Even when firms have incurred tariffs, they give several reasons why tariffs may not be immediately reflected in the prices they charge for their products. These include the following:

  • Waiting for tariff policy to clarify. Higher prices could reduce demand for goods and services and/or lead firms to lose market share, so many firms said they are hesitant to increase prices until they’re sure tariffs will remain in place. For example, a large national retailer said if tariffs are finalized at a sufficiently low level, they’ll absorb what they’ve incurred to date, but if high tariffs stick, they’ll have to raise prices. A steel fabricator for industrial equipment described being reluctant to raise prices on the 10 percent cost increases they’d seen thus far but would have to raise prices should the increases reach 12 to 13 percent. A grocery store chain was reluctant to raise prices and instead might reduce margins, which had recovered in recent years, to maintain their customer base. Some firms explicitly noted a strategy to both raise prices over time and pursue efficiency gains to cut costs and completely restore margins within a year or two.
  • Elasticity testing. Firms reported testing across goods whether consumers will accept price increases. A furniture manufacturer said he’s seen competitors pass along just 5 percentage points of the tariffs at a time so it isn’t such a huge shock to customers, though in that sector, “We all end in the same place which is the customer bearing most of it.” A national retailer said most firms are doing a version of stair-stepping tariffs through, e.g., raising prices a small amount once or twice to see if consumer demand holds, and if so, trying again two months later. This retailer said prices were going up very marginally in early summer, would increase more in July and August, and would be up by 3 to 5 percent by the end of Q4 and into 2026. Another national retailer said they would start testing the extent to which demand falls with price increases, e.g., when the first items that were subject to tariffs—in this case back to school items—hit shelves in late July.
  • Blind margin. Some firms reported attempting to pass through cost in less noticeable ways. While any price increase to consumers will be captured in measures of aggregate inflation, the fact that price increases may occur on non-tariffed goods might make it difficult to directly relate price increases to tariffs. An outdoor goods retailer said, “Unless it’s a branded item where everyone knows the price, if something goes for $18, it can also go for $19.” A national retailer plans to print new shelf labels with updated pricing, which will be less noticeable for consumers compared to multiple new price stickers layered on top. This takes time (akin to a textbook “menu cost” in economics), so it will not be reflected in prices until July and August. A grocery store said their goal was to increase average prices across the store but focus on less visible prices.
  • Selling out of preexisting inventory: Many firms noted they still have production inventory from before tariffs were announced, so they do not need to raise prices as long as they still sell these lower cost goods. A national retailer noted they have at least 25 weeks of inventory on hand for most imported products. A firm that produces grocery items said they will decide how much to raise prices as they get closer to selling tariff-affected products. Similarly, retailers order seasonal items quarters in advance. Many were receiving items for fall and winter when the new tariffs were going into effect in the spring. They paid the tariff then, but we won’t see the price increase until those items hit the shelves in the fall or winter. One retailer speculated that seasonal décor items will look the most like a one-time increase.
  • Pre-established prices. Many firms face infrequent pricing due to factors like annual contracts or pre-sales. For example, a dealer of farm equipment gets half its sales through incentivized pre-sales to lock in demand and smooth around crop cycles. They noted that while it would be difficult to retroactively ask those customers to pay for part of the tariff, they will pass tariffs directly through on spare parts. A steel fabricator for industrial equipment has a contract for steel through Q3, so they haven’t been impacted yet by price increases. However, they will face new costs once that contract expires.

In general, compared to small firms, large firms have more ability to negotiate with vendors, temporarily absorb costs, burn cash, wait for strategic opportunity, and test things out. This matters because large firms often lead pricing behavior among firms, so these strategic choices may influence the response of inflation to tariffs more generally. Even within firm size, one often hears that negotiations on price vary considerably by relationship and item.

Conclusion

A key question surrounding tariffs is whether any effects on inflation will resemble a short-lived price increase—as in the simplest textbook model of tariffs—or a more sustained increase to inflation that may warrant tighter Fed monetary policy. When asked in May what will determine the answer, Fed Chair Jerome Powell cited three factors [archived PDF]: 1) the size of the tariff effects; 2) how long it takes to work their way through to prices; and 3) whether inflation expectations remain anchored. The insights shared above suggest the process from proposed tariffs to the prices set by firms is far from instantaneous or clear-cut, particularly when tariff policy is changing.

Sensing from businesses suggests that the impact of tariffs on their price-setting [archived PDF] has been lagged, but it is starting to play out. Nonetheless, it remains highly uncertain how tariffs will impact consumer inflation. The discussion above makes clear that firms are nimble and innovative in the face of challenge, and they are concerned about losing customers in the current environment, particularly consumer-facing firms. We will continue to learn from our business contacts and share their insights.


Views expressed are those of the author(s) and do not necessarily reflect those of the Federal Reserve Bank of Richmond or the Federal Reserve System.

Economics-Watching: Tracking Business Sentiment in the Western United States

[from the Federal Reserve Bank of San Francisco, Economic Letters, 11 August, 2025]

by Hamza Abdelrahman, Luiz Edgard Oliveira and Aditi Poduri

Information the San Francisco Fed collects from businesses and community sources for the Beige Book provides timely insights into economic activity at both the national and regional levels. Two new indexes based on Beige Book questionnaire responses track business sentiment across the western United States. The indexes track data on economic activity and inflation, serving as early indicators of official data releases and helping improve near-term forecasting accuracy. The latest index readings suggest weakening economic growth and intensifying inflationary pressures over the coming months.


The San Francisco Fed serves the 12th District—the largest in the Federal Reserve System, representing nine western states, two territories, and a commonwealth. To better understand and analyze the regional economy, we collect information from a variety of business and community sources to create the San Francisco Fed’s report for the Beige Book. This is compiled with reports from other Districts and published by the Federal Reserve Board of Governors eight times a year. 

Views about the economy from businesses and communities play an important role in shaping economic outcomes. For example, expectations for future inflation can help spur or slow current consumer spending and business investment. Furthermore, economic forecasters rely on models that incorporate both more traditional “hard” quantitative data and “soft” qualitative information on sentiment. Adding these soft measures has been shown to improve the accuracy of economic forecasts (see Shapiro, Moritz, and Wilson 2022 and their cited literature). Among the many sentiment measures available, two popular approaches rely on survey data, as in the University of Michigan’s Surveys of Consumers, or on textual analysis, as in the SF Fed’s Daily News Sentiment Index.

This Economic Letter examines the economic information collected through the SF Fed’s Beige Book questionnaire over the past 10-plus years. We analyze this information by constructing sentiment indexes from the qualitative data and comparing them with quantitative measures of national and regional economic activity and inflation. We introduce two indexes—the SF Fed Business Sentiment Index and the SF Fed Inflation Gauge Index—which track our contacts’ views and expectations for economic growth and inflation, respectively. We find that these new indexes serve as reliable early indicators of official data releases and help improve near-term forecast accuracy. The SF Fed Business Sentiment Index has generally exhibited patterns similar to other recent business and household sentiment indexes, and the SF Fed Inflation Gauge Index has shown a strong uptick in expected inflation. To regularly monitor changes in these two indexes, the San Francisco Fed has launched a new Twelfth District Business Sentiment data page.

Constructing regional sentiment indexes

The San Francisco Fed sends out a Beige Book questionnaire to business and community contacts across the District eight times a year to gather regional information. In addition to answering questions regarding their organizations, respondents share their views on regional and national topics, including economic activity and inflationary pressures.

In two questions, respondents indicate whether they see national output growth and inflation rates increasing, decreasing, or staying stable over the coming year using a standard five-tiered scale. We use these responses since 2014 to formulate two business sentiment indexes, one on economic activity and another on inflation. We assign standard weights to the five-tiered qualitative scale that are symmetrical around zero. For example, we ask if activity is expected to “decrease significantly” = –2, “decrease” = –1, “remain unchanged” = 0, “increase” = 1, or “increase significantly” = 2. We add up the weighted shares of responses for each tier within each index. We then normalize each resulting series by its own average and standard deviation for ease of comparison with traditional economic indicators.

Tracking business sentiment

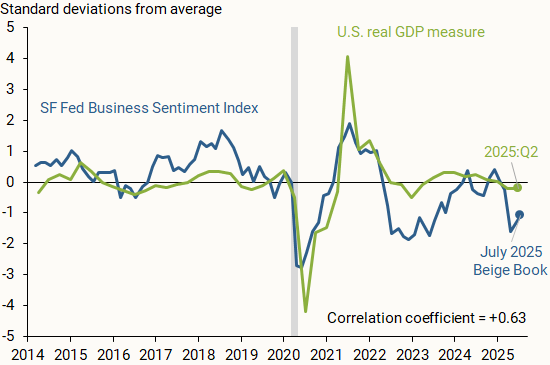
Figure 1 shows how the SF Fed Business Sentiment Index (blue line), compiled from responses to the question on national economic activity, compares with data on changes in national GDP (green line). We measure national output as the four-quarter change in inflation-adjusted, or real, GDP, normalized by its average and standard deviation so that it is centered around zero and, hence, more directly comparable to the SF Fed Business Sentiment Index. The vertical axis shows how many standard deviations away each observation is from its respective measure’s average from 2014 to mid-2025.

Figure 1
Economic growth versus business sentiment

Notes: Indicators normalized by their respective averages and standard deviations based on data from 2014 to present. Gray bar indicates NBER recession dates. Correlation coefficient is calculated between quarterly versions of both indicators.
Source: Bureau of Economic Analysis, FRBSF Beige Book questionnaire responses, and authors’ calculations.

The SF Fed Business Sentiment Index generally tracks the movements in national GDP over the past decade; a correlation coefficient of +0.63 on a scale of –1 to 1 indicates a moderately strong positive relationship between the two measures. A relatively recent exception started in 2022, when our index began showing a considerable decline relative to the national GDP measure. Respondents across the District were downbeat about economic growth and reported expectations of a sharp decline in consumer spending and overall household financial health following the depletion of pandemic-era savings (Abdelrahman and Oliveira 2023). A similar decline appeared in other measures of business and household sentiment. Nevertheless, overall economic growth continued at a solid pace. This decoupling between sentiment and hard data that began in 2022 was dubbed a “vibecession” (Daly 2024, Scanlon 2022).

Another possible reason for the divergence between national real GDP and our Business Sentiment Index is the influence of the regional economy. Although respondents are asked about their views of national GDP, their responses may be affected by regional outcomes. Thus, our index may also reflect a regional perspective from our business and community contacts.

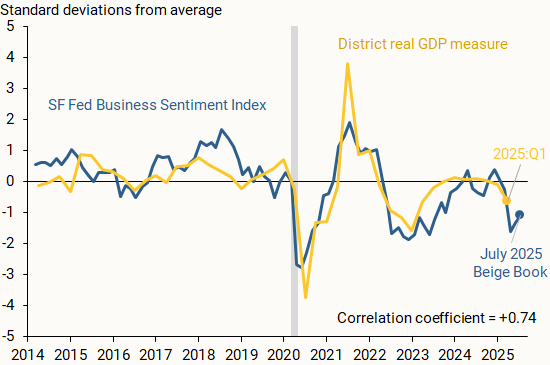
Figure 2 supports this rationale, showing the SF Fed Business Sentiment Index alongside a measure of regional output growth (gold line). We find that the measures closely track one another, including for 2022 and 2023, with a correlation coefficient of +0.74. We define District real GDP growth as the year-over-year percent change in the total output of the District’s nine states as reported by the Bureau of Economic Analysis (BEA). We normalize the series as described before.

Figure 2
Regional economic growth and business sentiment

Notes: Indicators normalized by their respective averages and standard deviations based on data from 2014 to present. Gray bar indicates NBER recession dates. Correlation coefficient is calculated between quarterly versions of both indicators.
Source: Bureau of Economic Analysis, FRBSF Beige Book questionnaire responses, and authors’ calculations.

Our findings indicate that the SF Fed Business Sentiment Index can serve as an accurate early indicator for national and regional output growth. Since the regional Beige Book questionnaire is collected twice each quarter, it provides particularly timely insights into economic activity during the current quarter. By contrast, the first GDP data release for any given quarter usually arrives a full month after that quarter has ended, and initial data releases for state-level output growth arrive with even more delay.

Over the first half of this year, the SF Fed Business Sentiment Index turned negative, with contacts citing elevated uncertainty about trade policy and downbeat expectations for the labor market. This notable decline is also seen in other measures of household and business sentiment, including national measures, such as the University of Michigan’s Surveys of Consumers, and regional measures, such as the Cleveland Fed’s Survey of Regional Conditions and Expectations and the Dallas Fed’s Texas Business Outlook Surveys.

Gauging business views on inflationary pressures

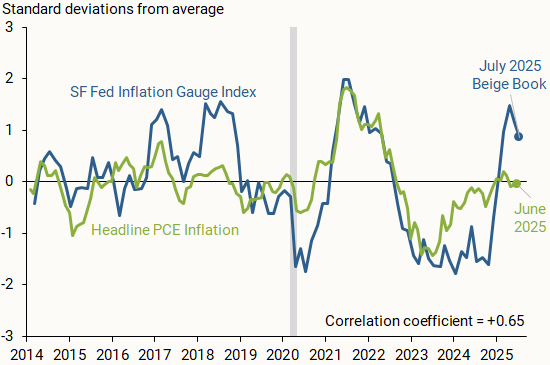
Our Beige Book questionnaire responses also provide insights into how business and community contacts in the District see national inflation evolving. Figure 3 compares the SF Fed Inflation Gauge Index (blue line) with monthly changes in the year-over-year headline personal consumption expenditures (PCE) inflation rate published by the BEA (green line). We normalize the inflation series and index as discussed earlier.

Figure 3
SF Fed Inflation Gauge Index versus realized inflation

Notes: Green line is the percentage point change in year-over-year headline PCE inflation shown as a 6-month moving average. Indicators normalized by their respective averages and standard deviations based on data from 2014 to present. Gray bar indicates NBER recession dates. Correlation coefficient is calculated between quarterly versions of both indicators.
Source: Bureau of Economic Analysis, FRBSF Beige Book questionnaire responses, and authors’ calculations.

Similar to our business sentiment index, the inflation gauge index is an early indicator for official inflation data releases. The index generally tracks changes in headline PCE inflation over the past decade, with a correlation coefficient of +0.65.

The most recent index results suggest a strong uptick in expected inflation among SF Fed business contacts, with several responses citing trade policy adjustments and inflation being persistently above the Federal Reserve’s 2% target. The recent peak resembles the one in 2018, which followed heightened trade tensions with China. The surge tracks other business and household-based measures of short-term inflation expectations, such as the Atlanta Fed’s Business Inflation Expectations and the New York Fed’s Survey of Consumer Expectations.

Making better projections

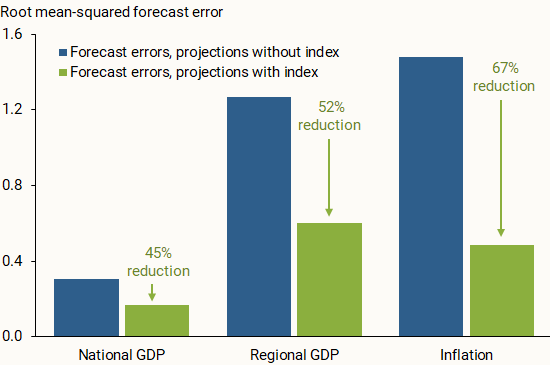
Beyond tracking data on national and regional economic conditions, we consider whether our two indexes can help improve one-year-ahead projections of output growth and overall inflation. We run linear regressions on a 2014–2022 data sample and estimate out-of-sample projections for the period starting in the first quarter of 2023. We run this analysis for the three economic measures—national GDP, regional GDP, and inflation—once with our index included on the right-hand side of the regression equation and once without the index. For this analysis, we use versions of the SF Fed Business Sentiment Index and the SF Fed Inflation Gauge Index that have been aggregated quarterly.

Figure 4 compares the out-of-sample projection accuracy of the two iterations. Across all economic measures, incorporating the SF Fed Business Sentiment Index or the SF Fed Inflation Gauge Index in the regression noticeably reduced the forecast errors for the out-of-sample period. This general result appears to hold when we project output growth and inflation one quarter ahead, in line with other studies that incorporate soft data from the Beige Book in short-term projections (Balke and Petersen 2002). The results are also consistent when using a local projections method from Jordà (2005) for one-year-ahead projections of output growth and shorter-term projections of inflation. This further supports the usefulness of our qualitative measures as early indicators of the future economic landscape over the short term.

Figure 4
Forecast errors with and without SF Fed sentiment indexes

Notes: Root mean-squared errors of out-of-sample projections from 2023:Q1 to 2025:Q2 including and excluding the SF Fed Business Sentiment Index (for GDP) and SF Fed Inflation Gauge Index (for inflation).
Source: Bureau of Economic Analysis, FRBSF Beige Book questionnaire responses, and authors’ calculations.

Conclusion

Information collected from businesses and communities through the San Francisco Fed’s regional Beige Book questionnaire can provide valuable insights into the national and regional economies. Sentiment indexes described in this Letter use responses from Twelfth District Beige Book contacts to generally track economic activity and inflation. Our two indexes serve as reliable early indicators of official data, which could help improve near-term forecast accuracy. The SF Fed Business Sentiment Index remained negative for much of 2022 and 2023, possibly reflecting more subdued growth within the District relative to the United States. Meanwhile, the SF Fed Inflation Gauge Index spiked in recent months following adjustments to trade policy.

References

Abdelrahman, Hamza, and Luiz E. Oliveira. 2023. “The Rise and Fall of Pandemic Excess Savings.” FRBSF Economic Letter 2023-11 (May 8).

Balke, Nathan S., and D’Ann Petersen. 2002. “How Well Does the Beige Book Reflect Economic Activity? Evaluating Qualitative Information Quantitatively.” Journal of Money, Credit and Banking 34 (1), pp. 114–136.

Daly, Mary C. 2024. “Fireside Chat with Mary C. Daly at the San Diego County Economic Roundtable.” January 19.

Jordà, Òscar. 2005. “Estimation and Inference of Impulse Responses by Local Projections.” American Economic Review 95(1), pp. 161–182.

Scanlon, Kyla. 2022. “The Vibecession: The Self-Fulfilling Prophecy.” Kyla Substack (June 30).

Shapiro, Adam Hale, Moritz Sudhof, and Daniel Wilson. 2022. “Measuring News Sentiment.” Journal of Econometrics 228(2), pp. 221–243.

China to Sustain Top-Down, Debt-Fueled Investment in Major Projects and Security Capacities, Ex-Official Says

Dong Yu, now at Tsinghua, says via state media that Beijing-decreed, central govt bond-backed construction will continue into the next five years.

[from the Center for China & Globalization’s Pekingology]

by Zichen Wang, 10 August, 2025

The key concept in today’s newsletter is 国家重大战略实施和重点领域安全能力建设, in abbreviation in Chinese as 两重 liǎng zhòng.

In English, it is translated officially as the implementation of major national strategies and building up security capacity in key areas, hereinafter referred to as “Two Major Undertakings.”

The concept first appeared in official policy documents in the Chinese Premier’s Report on the Work of the Government [archived PDF] in March 2024.

To systematically address funding shortages facing some major projects for building a great country and advancing national rejuvenation, it is proposed that, starting this year and over each of the next several years, ultra-long special treasury bonds be issued. These bonds will be used to implement major national strategies and build up security capacity in key areas. One trillion yuan of such bonds will be issued in 2024.

By the end of the year, the yuan tag, despite being approved by the national legislature, had changed by 300 billion. The People’s Daily newspaper reported in December 2024.

As of now, the 700 billion yuan in ultra-long-term special treasury bonds allocated for the “two major undertakings” has been distributed in three batches to specific projects.

In 2025, the following year, the Report on the Work of the Government [archived PDF] says,

A total of 1.3 trillion yuan of ultra-long special treasury bonds will be issued, 300 billion yuan more than last year.

735 billion yuan will be earmarked in the central government budget for investment. We will put ultra-long special treasury bonds to good use, increase ultra-long-term loans and other types of financing support, and strengthen top-down organization and coordination to ensure greater support for the implementation of major national strategies and security capacity building in key areas.

A simultaneous Finance Ministry budget plan [archived PDF] rounds up the overall central government spending for the Two Major Undertakings to 800 billion yuan in 2025.

In yuan terms, the much-touted new government subsidies to households pale in comparison with the two major undertakings.

Also from the 2025 Report on the Work of the Government [archived PDF]:

Ultra-long special treasury bonds totaling 300 billion yuan will be issued to support consumer goods trade-in programs. This represents an increase of 150 billion yuan over the previous year.

This week, China announced this week that the phased free preschool education policy will cover all children in their final year of kindergartens, saving families 20 billion yuan. Childcare subsidies unveiled in July amount to 90 billion yuan. 

As Joe Biden repeated over the years,

Don’t tell me what you value. Show me your budget, and I’ll tell you what you value.

The National Development and Reform Commission said last month:

In 2025, a total of 800 billion yuan has been allocated for the “two major undertakings,” supporting 1,459 projects in key areas such as ecological restoration in the Yangtze River Basin, major transportation infrastructure along the Yangtze River, the New Western Land–Sea Corridor, high-standard farmland, major water conservancy projects, urban underground pipeline networks, the “Three-North” shelterbelt program, and the renovation of hospital wards.

Now that the 2025 money has been spent by July and China is drawing up its next Five-Year Plan for 2026-2030, will there be more such projects in the future?

In a column for the state-run China News Service this week, Dong Yu, previously Deputy Director-General of the Second Economic Bureau of the Office of the Central Financial and Economic Affairs Commission and, before that, an official at China’s National Development and Reform Commission (NDRC), pointedly said,

In the next step, during the formulation and implementation of the 15th Five-Year Plan, the “two major undertakings” will continue to occupy an important place, be organically incorporated into the new five-year plan, and form close alignment and sustained momentum with major national strategies, major plans, major projects, and key initiatives…

…Such a major strategy will be pursued with persistence—it will not remain rhetorical, nor will it be reversed abruptly.

He did not cite a source of information in his article.

Continuing with his lecturing style, Dong, now Executive Vice Director of China Institute for Development Planning, Tsinghua University, rebuked some unspecified market analysis that had observed the investments just were a one-time boost shot.

Some market institutions once analyzed that when China’s economy was facing short-term difficulties and challenges, the launch of the “two major undertakings” was mainly aimed at expanding investment in the short term to stabilize growth. Such a view clearly lacks a professional understanding of the decision-making intentions and logic, fails to properly grasp the relationship between the short term and the medium-to-long term, as well as between objectives and means, and inverts the proper order of priorities—a misconception that needs to be pointed out and corrected.

Dong also highlighted what he said was the unusual nature of the “strategic move,” including that central government debts fueled the investments, and they were selected “top-down,” rather than primarily relying on local government proposal or input.

The two undertakings were formally submitted for deliberation at the 2024 National People’s Congress after the central leadership made its decision and arrangements…

The central authorities have shown firm determination in this work, adopting the ultra-long-term special treasury bond—a macro policy tool that has rarely been used. Compared with several past issuances of special treasury bonds, the funding arrangement for the “two major undertakings” spans a longer cycle, has a broader scope of application, and will continue to advance in the next stage. It can be said that the scale and intensity are unprecedented. In 2024, a total of 700 billion yuan in ultra-long-term special treasury bonds was allocated, and in 2025, the figure is 800 billion yuan, all of which have now been fully disbursed.

The organization of the “two major undertakings” construction is top-down, completely different from the past practice in the investment sector where projects were determined through bottom-up applications. The purpose is to facilitate the smoother downward transmission of the needs of major national strategies. Relevant [central] government departments, by identifying shortcomings and weaknesses, specifying key areas, and refining project requirements, have ensured that the project list is no longer a collection of fragmented local items. Instead, projects are planned in an integrated manner by category and sector, with strengthened guidance for key regions, more targeted measures, and clearer standards.

Although an exhaustive list of the 1,459 projects does not appear to be available to the public, the “security capacity” build-up in the two major undertakings should be understood in broad terms, and Dong claims the investments put China on a sounder footing globally now that Donald Trump rules America again.

In recent years, the central authorities have emphasized security awareness and bottom-line thinking in development planning, a shift closely related to changes in the international situation. The closer China’s economy becomes intertwined with the global economy, the more comprehensive its considerations must be regarding issues such as food security, energy security, industrial security, and ecological security. The second “undertaking” in the “two major undertakings”—the strengthening of security capabilities in key areas—is precisely a forward-looking arrangement. The dramatic changes in the international environment since the beginning of 2025 have further underscored and confirmed the necessity of enhancing security capabilities, fully demonstrating that the central authorities’ thinking and deployment have been prescient and ahead of the curve.

Dong’s article via China News Service is fully translated below.

中央这一先手棋很不寻常

This Strategic First Move by the Central Authorities Is Highly Unusual

by Dong Yu, Executive Vice President, Institute for China Development Planning, Tsinghua University

The issuance of ultra-long-term special treasury bonds to support the implementation of major national strategies and the building of security capacities in key areas (hereinafter referred to as the “two major undertakings”) has become one of the hottest topics in China’s economy in recent years. Any observation of China’s present and future economic trajectory must include research and analysis of these two undertakings. More than a year has passed since the initiative was launched, making it both necessary and timely to evaluate its effectiveness, understand its operating mechanisms, and look ahead to its prospects.

The “Two Major Undertakings” Are by No Means Ordinary Policy Measures

In terms of decision-making background and process, as well as policy intensity and scope, the launch and implementation of the two major undertakings stand out from other policies. They represent a top-level design initiative.

Understanding a policy starts with its background. From the sequence of events leading to the proposal, this was a proactive, historic choice. The two undertakings were formally submitted for deliberation at the 2024 National People’s Congress after the central leadership made its decision and arrangements. The timing was significant: the 20th Communist Party of China National Congress had laid out a series of major long- and medium-term strategic initiatives that needed concrete engineering projects to push forward. China was midway through two Five-Year Plans, yet strategic advancement could not wait. The central leadership thus introduced the two major undertakings as a groundbreaking initiative.

Strategically, the undertakings directly address the needs of advancing long-term objectives. From the outset, they have been aimed squarely at the goals of Chinese modernization. By breaking down these goals into specific tasks and identifying the most difficult bottlenecks, the undertakings found their points of focus. Some of these tasks might take decades for other countries to achieve, but China has chosen not to delay—tackling them head-on at the starting stage of the new journey toward modernization. This model is uniquely Chinese and has been proven by history to be a key factor in China’s remarkable development successes.

The undertakings are also highly forward-looking—a “first move” by the central leadership. In recent years, national development planning has placed greater emphasis on security and on guarding the bottom line, in response to changes in the international environment. The closer China’s economy is linked to the global economy, the more comprehensive its considerations must be on food security, energy security, industrial security, and ecological security, and other issues. The second “major” in the initiative—security capacity building in key areas—is an arrangement made in anticipation of future challenges. The sharp changes in the international environment since 2025 have only highlighted and validated the necessity of strengthening security capacities, demonstrating that the central leadership’s thinking and arrangements were ahead of the curve.

The undertakings also have a strong overall and systemic quality, constituting a key move in macroeconomic governance. They focus on areas of outstanding importance to economic and social development and have a high degree of relevance to the overall development landscape. The policy toolkit they employ integrates investment, fiscal, science and technology, education, social, and ecological policies. This comprehensive package embodies the use of systems thinking to drive development and will significantly impact all aspects of the economy and society.

A Manifestation of Central Will

Extraordinary measures are for extraordinary tasks. The strategic objectives of Chinese modernization are long-term undertakings, and the two major undertakings provide the foundational support through systematic design and substantial funding.

The central leadership has committed to this initiative by adopting the rarely used macroeconomic tool of ultra-long-term special treasury bonds. Compared with previous special bond issuances, the funding for the two undertakings spans a longer cycle and serves a wider range of purposes, with plans for continued implementation. In both scale and intensity, this is unprecedented: 700 billion yuan in 2024 and 800 billion yuan in 2025, all of which has already been allocated.

In terms of priorities, it vividly reflects the principle of “concentrating resources to accomplish major undertakings.” The focus areas include urban–rural integration, regional coordination, high-quality population development, food security, energy and resource security, ecological security, and self-reliance and strength in science and technology—all crucial to building a strong nation and achieving national rejuvenation. These require coordinated planning and advancement. In just over a year, the high-level requirements have been translated into batches of concrete projects, reflecting the efficiency of implementation.

Project selection is guided by the principle that only the central government can resolve these issues. Some involve urgent development bottlenecks with significant obstacles that cannot be overcome by conventional means, such as scientific and technological breakthroughs, high-standard farmland construction, and upgrading the quality of higher education. Others are long-desired but previously unachievable projects that lack local willingness or capacity to implement, such as major cross-regional infrastructure, cross-basin wastewater treatment, and urban underground utility upgrades.

The organization of the “two major undertakings” construction is top-down, completely different from the past practice in the investment sector where projects were determined through bottom-up applications. The purpose is to facilitate the smoother downward transmission of the needs of major national strategies. Relevant [central] government departments, by identifying shortcomings and weaknesses, specifying key areas, and refining project requirements, have ensured that the project list is no longer a collection of fragmented local items. Instead, projects are planned in an integrated manner by category and sector, with strengthened guidance for key regions, more targeted measures, and clearer standards.

A Combination of “Hard” and “Soft” Measures

From the start, the undertakings were designed not only to fund “hard” engineering projects but also to include comprehensive arrangements for “soft” institutional and policy measures—an important innovation.

The emphasis on soft measures is pragmatic. Given the high importance and public nature of the projects, long-term mechanisms must be designed to ensure smooth progress during construction and sustainable operation thereafter. This includes drafting specialized plans to provide strategic guidance, introducing targeted policies to improve funding efficiency, and innovating institutional arrangements to safeguard implementation.

The implementation process is thus also a process of improving the investment and financing system, updating project management approaches, and enhancing investment effectiveness. In some sectors, soft-measure experiments have had positive impacts, creating healthy interaction with hard investments.

For example, the healthy operation of urban underground pipelines depends on sound maintenance mechanisms. Some local governments have attracted long-term institutional funds into major pipeline projects through debt or equity investment plans, stabilizing private sector returns via operational rights, government subsidies, and tax incentives. Others have introduced province-wide upstream–downstream gas price linkage, set reasonable water supply return rates based on market profits, and advanced the marketization of gas and water prices—reducing losses for public utilities and encouraging private investment.

Similarly, in the quality undergraduate expansion program, mechanisms play a guiding role: schools effectively implementing expansion plans receive increased support, while those performing poorly see reduced support; universities without expanded undergraduate admission plans are generally excluded from special bond funding. Disciplines and programs are adjusted dynamically to align talent training with economic and societal needs.

Directly Relevant to Everyone

The nature of the undertakings is not determined by project size but by their strategic objectives and significance. As long as they align with major national strategies, they are included—whether as large standalone projects, such as high-speed rail along the Yangtze River, or as “project packages,” such as Yangtze River wastewater treatment composed of multiple treatment facilities. This flexible, problem-oriented approach allows better alignment with public needs.

As projects break ground and enter operation, their benefits to people’s livelihoods will become increasingly evident. Observers should not see the undertakings as distant from daily life; they will bring tangible improvements to everyone’s quality of life.

For example:

  • Urban underground pipelines: Upgrades to gas, water, and heating systems will greatly improve safety and resilience. Renovation of old gas pipelines is nearing completion, reducing accident rates by over 30%. Eliminating hidden risks in unseen places increases residents’ sense of security.
  • Food security: Gradually converting all permanent basic farmland into high-standard farmland will stabilize grain output and enhance food safety. Higher standards mean safer products, so people will eat with greater confidence.
  • Yangtze River protection: Building or upgrading over 60,000 kilometers of sewage pipelines in the Yangtze Economic Belt will greatly improve the river’s ecological environment and resolve long-standing public concerns.
  • Transportation: Creating the shortest Shanghai–Chengdu high-speed rail corridor (approx. 1,900 km) will connect the Yangtze River Delta, the middle Yangtze region, and the Chengdu–Chongqing area more quickly, cutting travel time nearly in half and boosting east–west connectivity.
  • Ecological security: Implementing the “Three-North” shelterbelt project over 130 million mu (93 million hectares), with good survival rates for trees, shrubs, and grasses, will safeguard northern ecological security and create new income opportunities.
  • Higher education: “Double First-Class” universities will see markedly improved conditions, with over 500,000 new standard dorm beds. Quality undergraduate enrollment will rise by 16,000 in 2024 and over 20,000 in 2025, giving more students access to quality education and ensuring basic living needs for those from low-income families.
A Bold Stroke in the History of Development

The two major undertakings are a major decision by the CPC Central Committee and the State Council, aimed at the overall strategy of building a strong country and achieving national rejuvenation. They play an irreplaceable role in advancing Chinese modernization.

They are not short-term measures but focus on medium- to long-term development. Some market institutions once analyzed that when China’s economy was facing short-term difficulties and challenges, the launch of the “two major undertakings” was mainly aimed at expanding investment in the short term to stabilize growth. Such a view clearly lacks a professional understanding of the decision-making intentions and logic, fails to properly grasp the relationship between the short term and the medium-to-long term, as well as between objectives and means, and inverts the proper order of priorities — a misconception that needs to be pointed out and corrected.

Since implementation began, the undertakings have provided important support for economic stability. Although their starting point was not short-term growth, the resulting investment has boosted employment and consumption, helping to expand domestic demand and stabilize growth. In the next step, during the formulation and implementation of the 15th Five-Year Plan, the “two major undertakings” will continue to occupy an important place, be organically incorporated into the new five-year plan, and form close alignment and sustained momentum with major national strategies, major plans, major projects, and key initiatives.

They will also bolster the country’s core competitiveness. As foundational support for Chinese modernization, they will strengthen factor security and resolve long-term bottlenecks, with far-reaching significance for shaping China’s development prospects. In an era of intensifying major-power competition, they will provide stable expectations and significantly enhance China’s capacity to manage international uncertainty. Such a major strategy will be pursued with persistence—it will not remain rhetorical, nor will it be reversed abruptly.

Though implementation has only recently begun, the undertakings’ historic role will continue to grow over time. In the future, looking back, they will surely stand as an important part of the “China story” and leave a bold stroke in the history of the People’s Republic’s development.

World-Watching: 272nd Meeting of the Monetary Policy Committee (“Copom”) of the Central Bank of Brazil Press Release

Copom maintains the Selic rate at 15.00% p.a.

[from the Central Bank of Brazil, 30 July, 2025]

​The global environment is more adverse and uncertain due to the economic policy and economic outlook in the United States, mainly regarding its trade and fiscal policies and their effects. Therefore, the behavior and the volatility of different asset classes have been impacted, altering global financial conditions. This scenario requires particular caution from emerging market economies amid heightened geopolitical tensions.

Regarding the domestic scenario, the set of indicators on economic activity has shown some moderation in growth, as expected, but the labor market is still showing strength. In recent releases, headline inflation and measures of underlying inflation remained above the inflation target.

Inflation expectations for 2025 and 2026 collected by the Focus survey remained above the inflation target and stand at 5.1% and 4.4%, respectively. Copom’s inflation projections for the first quarter of 2027, currently the relevant horizon for monetary policy, stand at 3.4% in the reference scenario (Table 1).

The risks to the inflation scenarios, both to the upside and to the downside, continue to be higher than usual. Among the upside risks for the inflation outlook and inflation expectations, it should be emphasized (i) a more prolonged period of de-anchoring of inflation expectations; (ii) a stronger-than-expected resilience of services inflation due to a more positive output gap; and (iii) a conjunction of internal and external economic policies with a stronger-than-expected inflationary impact, for example, through a persistently more depreciated currency. Among the downside risks, it should be noted (i) a greater-than-projected deceleration of domestic economic activity, impacting the inflation scenario; (ii) a steeper global slowdown stemming from the trade shock and the scenario of heightened uncertainty; and (iii) a reduction in commodity prices with disinflationary effects.

The Committee has been closely monitoring the announcements on tariffs by the USA to Brazil, which reinforces its cautious stance in a scenario of heightened uncertainty. Moreover, it continues to monitor how the developments on the fiscal side impact monetary policy and financial assets. The current scenario continues to be marked by de-anchored inflation expectations, high inflation projections, resilience on economic activity and labor market pressures. Ensuring the convergence of inflation to the target in an environment with de-anchored expectations requires a significantly contractionary monetary policy for a very prolonged period.

Copom decided to maintain the Selic rate at 15.00% p.a., and judges that this decision is consistent with the strategy for inflation convergence to a level around its target throughout the relevant horizon for monetary policy. Without compromising its fundamental objective of ensuring price stability, this decision also implies smoothing economic fluctuations and fostering full employment.

The current scenario, marked by heightened uncertainty, requires a cautious stance in monetary policy. If the expected scenario materializes, the Committee foresees a continuation of the interruption of the rate hiking cycle to examine its yet-to-be-seen cumulative impacts, and then evaluate whether the current interest rate level, assuming it stable for a very prolonged period, will be enough to ensure the convergence of inflation to the target. The Committee emphasizes that it will remain vigilant, that future monetary policy steps can be adjusted and that it will not hesitate to resume the rate hiking cycle if appropriate.

The following members of the Committee voted for this decision: Gabriel Muricca Galípolo (Governor), Ailton de Aquino Santos, Diogo Abry Guillen, Gilneu Francisco Astolfi Vivan, Izabela Moreira Correa, Nilton José Schneider David, Paulo Picchetti, Renato Dias de Brito Gomes, and Rodrigo Alves Teixeira.

Table 1

Inflation projections in the reference scenario
Year-over-year IPCA change (%)

Price Index202520261st quarter 2027
IPCA4.93.63.4
IPCA market prices5.13.53.3
IPCA administered prices4.44.03.9

In the reference scenario, the interest rate path is extracted from the Focus survey, and the exchange rate starts at USD/BRL 5.55 and evolves according to the purchasing power parity (PPP). The Committee assumes that oil prices follow approximately the futures market curve for the following six months and then start increasing 2% per year onwards. Moreover, the energy tariff flag is assumed to be “green” in December of the years 2025 and 2026. The value for the exchange rate was obtained according to the usual procedure.

Note: This press release represents the Copom’s best effort to provide an English version of its policy statement. In case of any inconsistency, the original version in Portuguese prevails.