World-Watching: Old Problem, Modern Solution: Emerging Technologies for Anti-Corruption

[from Asia-Pacific Economic Cooperation, 29 July, 2025]

by Emmanuel A. San Andres and Glacer Nino A. Vasquez

Harnessing new tools to strengthen transparency and accountability can help APEC economies combat corruption and build public trust.

The Code of Hammurabi is one of humanity’s oldest surviving legal texts. Etched in basalt nearly four millennia ago, one of the many crimes it proscribes is corruption by a judge, for which the punishment is a hefty fine—“twelve times the fine set by him in the case”—plus removal and perpetual disqualification from office. Today, laws are published online rather than on stone tablets, but corruption remains a scourge across societies.

Thousands of years later, the fight against corruption continues. Corruption scandals continue to make headlines across the region, affecting both public and private institutions. Whether involving procurement fraud or illicit finance flows, these cases underscore how quickly trust can erode when institutions fail to adapt. The need for preventive systems, powered by data, backed by law and enabled by technology, has never been more urgent. Across APEC, the principles of transparency, accountability and integrity remain central to strong public institutions. As economies become more interconnected and more data-driven, emerging technologies are offering new ways to advance these goals.

APEC economies have long relied on oversight mechanisms such as audits, procurement rules, and internal checks to prevent, detect and prosecute corruption. These tools have been effective in fighting corruption, and they remain essential. But at the same time, new technology has also opened new pathways for corruption: The discreet meeting at a coffeeshop may now occur over an encrypted messaging app, and the cash-filled envelope replaced by a cryptocurrency transfer.

As corrupt actors grow more technologically sophisticated, so too must anti-corruption efforts. APEC economies are not new to digital solutions—e-government and e-procurement portals have reduced opportunities for hidden transactions. Beneficial ownership registries and asset tracking systems make it easier to prosecute and penalise incidents of corruption when they do occur. But emerging technologies offer even more powerful tools to prevent, detect and deter corruption.

For example, artificial intelligence and machine learning (AI/ML) enable real-time monitoring, risk scoring, pattern detection, and predictive analytics. These tools can support monitoring and investigation by automating document review and evidence gathering. AI/ML can also enhance institutional capacity through adaptive, personalized training systems.  Meanwhile, advanced data analytics can support the review of large volumes of data, revealing patterns of corrupt activity and informing decision-making. When data from different sources are connected, it becomes easier to understand corruption risks early and act with greater precision.

Blockchain—the technology that enables cryptocurrencies—can be used to create immutable, transparent ledgers for government transactions, supply chain monitoring and secure identity management, making it harder to conceal corrupt activity. Remote sensing and facial recognition technologies also offer potential in compliance monitoring and anomaly detection.

However, implementing these emerging technologies have their share of challenges and risks. The effectiveness of AI/ML systems is only as good as the quality, integrity and objectivity of the data they are fed; biased inputs can produce biased outcomes. Blockchain technology is very energy-intensive, which may hinder its scalability and availability. Facial recognition raises serious concerns over privacy and due process, enabling widespread surveillance without individual consent.

These trends mirror growing international momentum around the digitalization of integrity systems. International organizations are helping lead the way: the OECD is leveraging AI and big data to detect corruption risks and improve compliance, while the World Bank’s Governance Risk Assessment System [archived PDF] uses analytics to uncover fraud in public procurement, with pilots already underway in Brazil. As stewards of major anti-corruption conventions, these institutions are turning innovation into accountability. For APEC economies, this alignment offers a timely opportunity to shape global standards while advancing domestic reform.

It is also important to recognize the central role of human and institutional elements in anti-corruption efforts. Emerging technologies are not a silver bullet; they will only be effective if they are well integrated into government processes and are aligned with the skills of the people who need to use them. Training and capacity building will be essential to bridge capability gaps, while a committed leadership will be needed to implement the legal reforms and oversight structures needed to ensure effective adoption.

Buy-in from anti-corruption stakeholders across government, the private sector and civil society is also crucial to this pursuit. Technologies like AI/ML and advanced analytics require large volumes of reliable data, requiring cooperation and information sharing. Public understanding and trust, ethical use of data and equitable access to technology are all essential to ensuring long-term success.

APEC economies are at different stages of readiness to adopt these emerging technologies. While some economies have yet to develop adequate digital infrastructure, human capital and institutional structures, others are already in a position to expand or integrate more advanced anti-corruption tools into their day-to-day processes. Capacity building, information sharing and dialogue can help narrow this gap while learning from the experiences of those ahead.

This is where regional cooperation can make a difference APEC provides a platform for knowledge sharing, capacity building and policy cooperation. The Anti-Corruption and Transparency Experts Working Group could provide a venue for a collaborative strategy to mainstream emerging technology in anti-corruption work, while building technical capacity for economies that need it. Likewise, the upcoming APEC High-Level Dialogue on Anti-Corruption Cooperation provides an opportunity to reaffirm values and shared commitments in the fight against corruption.

Corruption has existed since the dawn of civilization. As methods to commit corruption have evolved, so must the tools to combat it. People and institutions will always remain at the heart of anti-corruption efforts, but with the right governance and safeguards, emerging technologies can be game-changers in fighting corruption and recovering its proceeds, whether it’s in Babylonian sheqels or in bitcoins.

Emmanuel A. San Andres is a senior analyst, Glacer Niño A. Vasquez is a researcher at the APEC Policy Support Unit. For more on this topic, read the latest issue paper “Technologies for Preventing, Detecting, and Combatting Corruption” [archived PDF].
Economics-Watching: Kuwait: GDP Returns to Growth in Q1 2025 as Impact of Oil Output Cuts Fades

[from NBK Economic Research, 21 July, 2025]

by Mohammad Al-Shehri, Assistant Economist & Omar Al-Nakib, Head of MENA Research

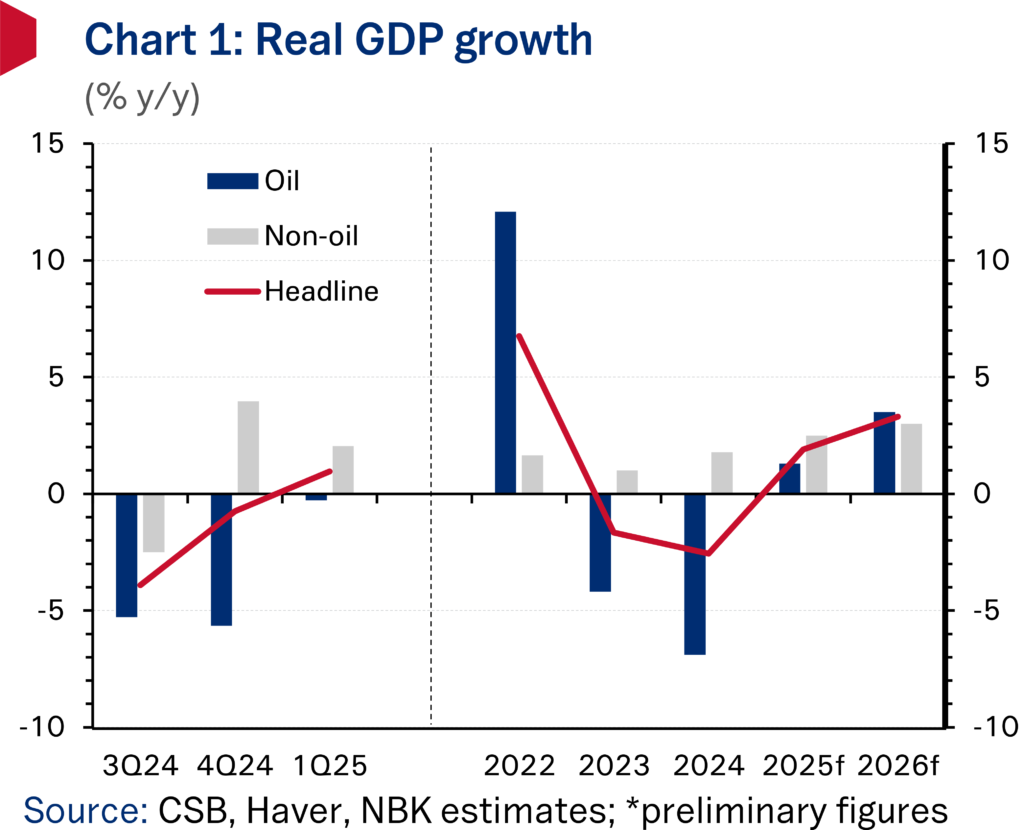
Preliminary official figures show GDP expanding 1% y/y in Q1 2025 following seven consecutive quarters of contraction, helped by a less severe downturn in oil output. With the negative effects of earlier voluntary oil production cuts beginning to fade, oil GDP recorded only a marginal decline, the softest since Q2 2023. Growth in non-oil activity remained positive though eased, weighed by a moderation in the manufacturing, real estate, and transport sectors. The near-term outlook for GDP is one of positive growth, lifted by rising oil production after Kuwait started to restore 135 kb/d of oil output cuts between April and September 2025, while the non-oil sector should also register further steady gains.

Non-oil GDP growth softens in Q1 2025 after strong performance in Q4 2024

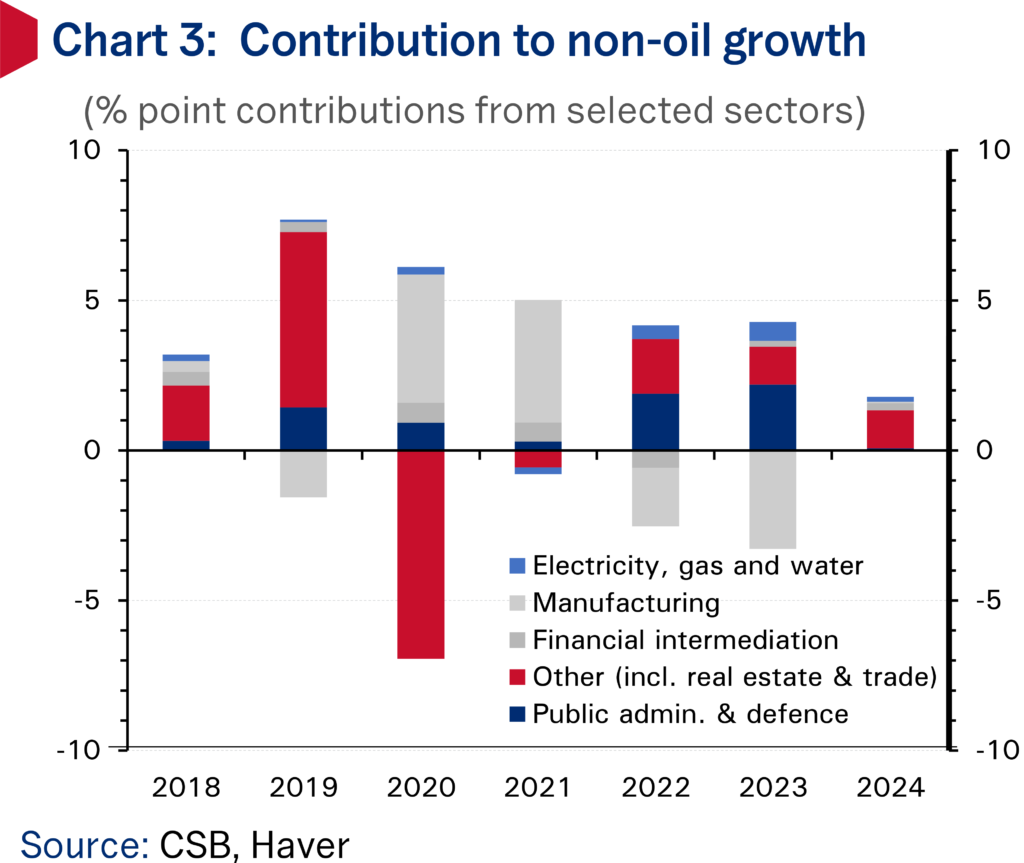
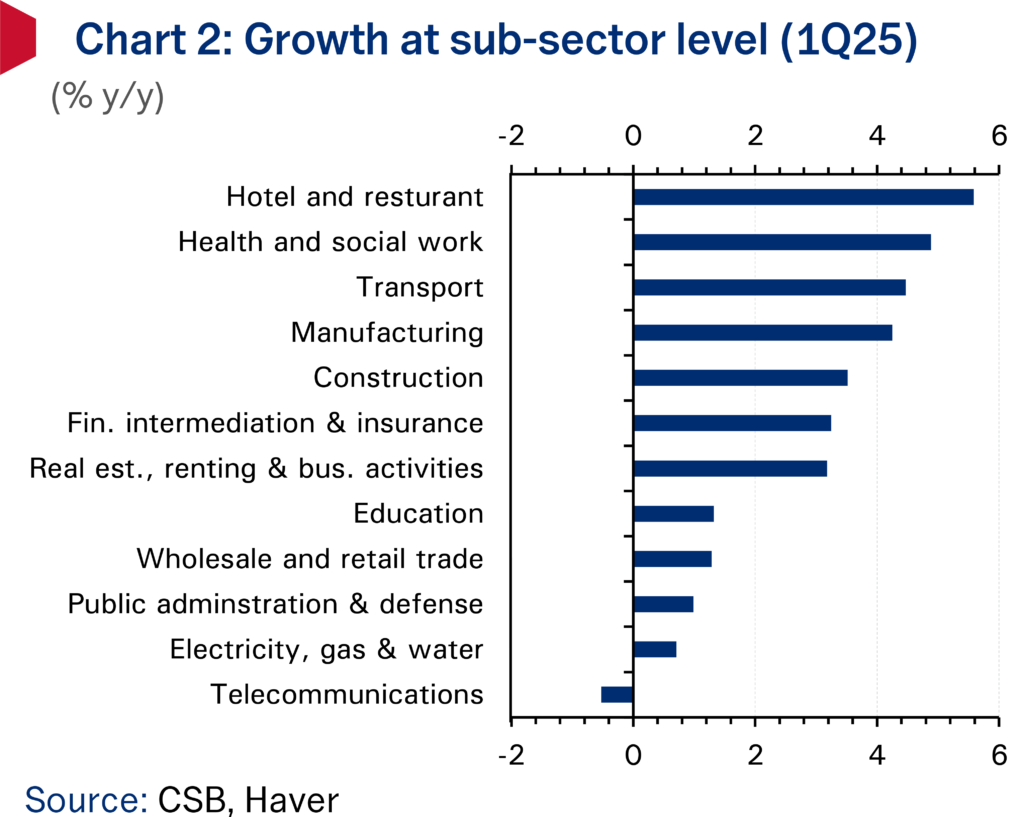
Growth in the non-oil sector weakened in Q1 2025, slowing to 2% y/y compared to 4% recorded in the prior quarter. (Chart 1.) The softer expansion in non-oil activity reflected, among other things, a moderation in the manufacturing sector, where activity grew at a still-solid 4.3% despite a decline in refined petroleum products output but slowed notably from the 12.2% reading registered in Q4 2024. Growth in other sectors including real estate, wholesale & retail trade, transport, and education also slowed. Offsetting the slowdown was stronger expansion in the non-oil economy’s largest segments: public administration and defense as well as financial intermediation and insurance, which grew 1% and 3.2% y/y, respectively. (Chart 2.)

Chart 1: Real GDP growth

Chart 2: Growth at sub-sector level (1Q25)

Oil sector logs marginal contraction, set to return to growth in Q2

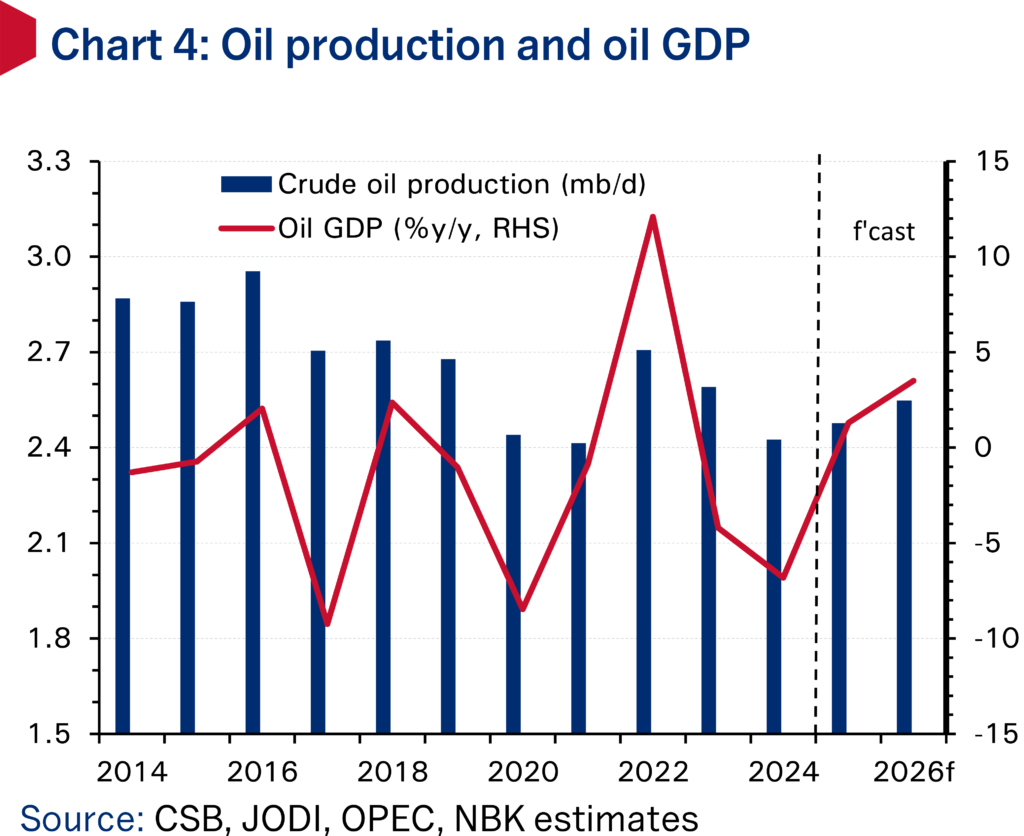
The contraction in oil GDP eased significantly to -0.3% y/y from -5.7% y/y in Q4 2024, registering the softest rate of decline since Kuwait embarked on cutting oil production in Q2 2023 after participating in the voluntary cuts scheme with 7 other OPEC+ members. (Chart 4.) Kuwait’s oil production averaged 2.415 mb/d in Q1 2025, a 0.7% decline from the same quarter last year, according to OPEC secondary sources. However, oil sector fortunes are set to shift in Q2 2025 and thereafter, after the OPEC-8 member alliance started unwinding the 2.2 mb/d voluntary cut tranche in April 2025. Originally planned to be unwound over the course of 18 months, OPEC+ has accelerated the pace of supply hikes with output now on a path to be fully restored in September, a full year ahead of schedule. For Kuwait, crude production rose by 0.5% q/q in Q2 to 2.426 mb/d and is set to accelerate further to average 2.533 mb/d in H2 2025. With the oil market so far able to absorb the additional OPEC and global supply and oil prices currently holding near $70/bbl, an upside risk to our oil sector outlook involves the potential unwinding of the outstanding OPEC-8 voluntary cuts (1.66 mb/d), of which Kuwait’s share is 128 kb/d.

Growth heading back into positive territory in 2025

Growth in total GDP is set to remain on a positive trajectory in the near term, buoyed by further steady expansion in non-oil economic activity and increased oil production. Non-oil GDP is set to benefit from the government’s reform drive which includes the recent passing of the debt law that could catalyze the implementation of key development projects and the potential approval of the ‘mortgage’ law later in 2025, which could spur higher household borrowing and consumer spending. Economic indicators for Q2 2025 pointed to a healthy pace of non-oil economic activity. The key ‘output’ and ‘new orders’ balances in the non-oil private sector PMI gauge both averaged a very robust 57+ in Q2 2025, real estate activity continued to expand at a robust pace with earlier price falls in the residential sector abating, while credit growth stood at a healthy 5.5% y/y in May, and could benefit in coming months if interest rates are reduced further.

Nonetheless, there are also downside risks to the outlook. Local consumer spending growth (according to central bank card transactions data) turned negative in Q1 2025, extending the weakening trend now observed for more than a year. The government’s ongoing fiscal consolidation push will also weigh on wage and job growth. Overall, we see GDP growing 1.9% this year, boosted by expansions in both the oil and non-oil sectors of 1.2% and 2.5%, respectively.

Chart 3: Contribution to non-oil growth

Chart 4: Oil production and oil GDP

Read this article as an archived PDF.

World-Watching: U.S. Greenlighted H20 Chips Export on Its Own Initiative, China Says

Beijing clarifies its deal with Washington didn’t include NVIDIA’s 4th-best AI chip, disputing widely-reported comments by U.S. Commerce Secretary Howard Lutnick

by Zichen Wang, from Pekingnology

The U.S. greenlighted NVIDIA’s China-specific Artificial Intelligence chip, known as the H20, for export to China on its own initiative, China said on Friday.

In a statement dedicated to the recent U.S. approval of the semiconductor giant’s 4th-best Artificial Intelligence chip, China’s Ministry of Commerce said on its website that in early July, the U.S. had already lifted restrictions on China under the agreement reached between the two countries in London.

“We have taken note that Washington has now taken the initiative to announce it will authorize sales of NVIDIA’s H20 chips to China,” the trade ministry added.

Beijing’s clarification stands in stark contrast to widely reported public comments earlier this week by U.S. Commerce Secretary Howard Lutnick, who told Reuters on Tuesday that “We put that in the trade deal with the magnets,” referring to the agreement made to restart Chinese rare earth shipments to U.S. manufacturers. He did not provide additional details, according to Reuters.

NVIDIA’s H20 was designed to be technologically inferior. The company also sells three other chips that far surpass the H20’s power.

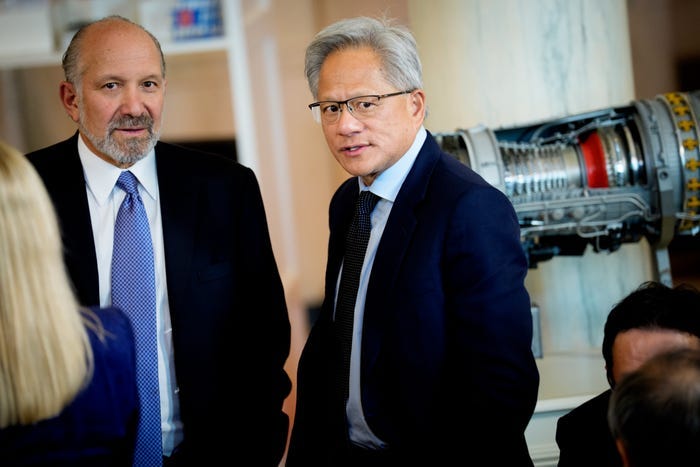
Commerce Secretary Howard Lutnick echoed NVIDIA CEO Jensen Huang’s view of why a U.S. company should sell chips to China. Andrew Harnik/Getty Images

On Monday, July 14, the Silicon Valley company announced in a blog post that the U.S. government had approved the sale of the H20, three months after the Donald Trump administration shut down NVIDIA’s artificial intelligence chip sales to China, after CEO Jensen Huang met President Trump in Washington D.C., and before he departed for Beijing.

Huang dominates Chinese headlines this week with his speech at an industry conference and public events with Chinese AI leaders. He visited China’s Ministry of Commerce and was received by Wang Wentao, the minister, on Thursday.

商务部新闻发言人就美批准对华销售英伟达H20芯片有关情况答记者问

MOFCOM Spokesperson Responds to Questions on the U.S. Approval of NVIDIA H20 Chip Sales to China

2025-07-18 13:43

Question:

U.S. officials have recently stated that Washington’s decision to approve sales of NVIDIA’s H20 chips to China is part of China–U.S. economic and trade negotiations. They also claimed that Chinese firms, including Huawei, are already producing equivalent chips domestically and that the United States does not want China to achieve full import substitution. How does the Ministry of Commerce (MOFCOM) view this?

Answer:

Following the China–U.S. economic and trade consultations in London, the two sides have maintained close communication, finalized the “London framework,” and moved forward with implementation. China, in accordance with its laws and regulations, approves export applications for controlled items that meet the necessary criteria. In early July, the United States reciprocally lifted the restrictions on China that had been discussed during those talks.

We have taken note that Washington has now taken the initiative to announce it will authorize sales of NVIDIA’s H20 chips to China. Beijing believes the United States should abandon a zero-sum mentality and continue to roll back a range of unwarranted trade and technology restrictions on China.

Cooperation and mutual benefit are the only viable path; suppression and containment lead nowhere. In May, the United States issued new export-control guidelines targeting Huawei’s Ascend chips, tightening restrictions on Chinese semiconductor products under unfounded pretexts. By wielding administrative power to distort fair market competition, these measures severely undermine the legitimate rights and interests of Chinese companies. China has made its position clear and firmly opposes such actions.

We look forward to the United States working with China in a spirit of equality to correct these erroneous practices, foster a sound environment for mutually beneficial cooperation between the two countries’ enterprises, and jointly safeguard the stability of global semiconductor supply chains.

Economics-Watching: BRICS Currency Creates Dilemma for the Dollar

by Christopher Whalen, from China Daily

The term “BRICS currency” typically refers to a hypothetical or proposed unified currency for the BRICS grouping. It’s not a single, physical currency currently in use, but rather a concept for a potential future monetary system that some suggest will reduce the dominance of the U.S. dollar in international trade and finance.

Is BRICS currency cooperation about immediate de-dollarization or long-term financial sovereignty? The answer is that BRICS cooperation may include reducing long-term dependence on the dollar as a means of exchange. The dollar is involved in more than half of all trade and 80 percent of all foreign exchange transactions. BRICS currency cooperation aims to gradually reduce the group’s dollar dependency, but challenges remain.

The BRICS concept came about not because the dollar is unsuitable as a means of exchange or unit of account, but rather because of the use of the dollar by Washington as a weapon. As I note in my book, Inflated: Money, Debt and the American Dream, the special role of the dollar in U.S. finance allows the U.S. government to impose harsh compliance and reporting requirements on foreign nationals and institutions. The U.S. is an arbitrary hegemon and does not follow reciprocity with other countries.

The global role of the dollar is an anomaly, the byproduct of two world wars had left the other antagonists broke by the time the Bretton Woods Agreement was signed in July 1944.

Choosing the fiat paper dollar as the default global reserve currency more than seven decades ago reflected the fact that the United States was one of the victors and possessed the wealth that gave Washington unchallenged economic leadership. Prior to World War I, the United Kingdom’s pound sterling was the global standard, but importantly, this paper currency was backed by gold — the only money that is not debt. The dollar, too, was backed by gold — until 1933, when the Franklin Roosevelt administration confiscated gold in private hands to prevent his government from collapsing.

Pound notes started to circulate in England in 1694, shortly after the establishment of the Bank of England. The paper pound helped to fuel the expansion of the British Empire, in large part because the only competing form of money was physical gold. When Britain and other nations left the gold standard in the 1930s, it was due to the deflation caused by the Great Depression rather than a deliberate choice.

The 19th-century rule attributed to English journalist and businessman Walter Bagehot says that in times of crisis, lend freely at a high rate against good collateral. Yet since the currency devaluation and gold seizures of 1933, fiat currencies and below-market interest rates have been the rule. In a global scheme in which the government occupies the prime position, the operative term remains “financial repression”, whereby governments control markets and artificially suppress rates of return on debt. For this reason, the dollar is losing its role as a store of value to gold.

The fact that the dollar continues to trade strongly versus other currencies reflects the reality that as the main means of exchange globally, the dollar cannot be easily replaced. One reason for this continued support for the dollar is that the trade in petroleum and other commodities is so large that it requires an equally large currency to accommodate it. Also, neither the Europeans nor the Japanese, the only two possible alternatives, are willing to risk the external deficits or inflation that the U.S. suffers as the host for the global currency.

What global currency will replace the fiat paper dollar? None. As this article is being written, gold is the second-largest reserve asset for central banks after the dollar. “The initiation in 2002 of the Shanghai Gold Exchange was of great strategic significance, both for gold and the global monetary system,” notes veteran gold fund manager Henry Smyth in an interview in The Institutional Risk Analyst. “Now it is completely clear what happened.”

Smyth and many other observers see the creation of the SGE in 2002 as the return of gold to the international monetary system. But while gold is growing in importance as a reserve asset for many countries, it does not mean that the role of the dollar as a global means of exchange or unit of account is about to change.

The dollar will remain the dominant asset. And even then, displacing the dollar will require a major change in the international monetary system, a change that is already underway.

The author is the chairman of Whalen Global Advisors LLC in New York and the author of Inflated: Money, Debt and the American Dream published by Wiley Global (2025).

Is the World Broken?

Gabriel Marcel was a famous 20th century existence-watcher. He kept circling back to conundrums which preoccupied him his entire life.

The first was how to explain the profound difference between a problem and a mystery. He says, for example, that a problem is something that you can surround, but a mystery is something that surrounds you. He also calls into doubt the ideology of scientism (the belief that science and the scientific method are the best or only way to render truth about the world and reality). According to scientism, the story of mankind since the rise of modern science, with people such as Galileo, is the transformation of all mysteries into problems. With the passage of time, those problems would be solved. However, when we look around us at such science-thinkers like Roger Penrose, Neil Turok and Carlo Rovelli, we find that science is becoming more mysterious and the mysteries are increasingly deep, as anyone who follows quantum mechanics can see.

For the second he kept asking, how it is that I both have a body but that I am a body? Think of the phrase “I am somebody” and notice the last word. The physical body cannot be disentangled from personhood.

In 1933, Marcel published the famous play, Le Monde cassé (French: The Broken World). Compare that to the previous article, “Why Is the World So Nightmarish?” discussing Céline’s 1932 Journey to the End of the Night (French: Voyage au bout de la nuit). Both of these works describe a human world which is completely adrift, disoriented and soulless.

As an existential thinker, Marcel always watched humanity and did a soul-audit. He was not particularly attentive to the other dimension of our earthly stay, namely political economy. In order to make up for this semi-absence, we bring in Gustav Stresemann, who gives us the lens for it. Stresemann died within weeks of the Wall Street crash of 1929.

A few days before his death, Stresemann, the leading German statesman of his time, gave a speech at the League of Nations. In this, he gave an update on the German economic situation of the moment. He stated that the numbers were superficially encouraging, but that Germany, under the surface, was “dancing on a volcano.”

The concept of a country or indeed the whole world in these straits is very profound. It tells us that as people like Céline and Marcel warn us, the world is potentially broken at all moments because the people do not even have a concept of self-possession. Furthermore, the cracks underneath the foundation of the world economy indicate a dangerous fragility at all times. In this larger sense, Marcel’s concept of the broken world combined with Stresemann’s dancing on a volcano, allow us to glimpse an instability that current education does not cover.

Economics-Watching: Kuwait’s Banking Sector Posts Solid Credit Growth in October

[from NBK Group’s Economic Research Department, 21 November, 2024]

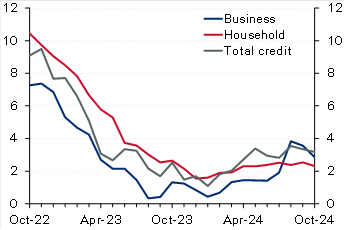
Kuwait: Solid credit growth in October driven by household credit. Domestic credit increased by a solid 0.4% in October, driving up YTD growth to 2.9% (3.2% y/y). The recovery in household credit continued, with growth in October at a solid 0.5%, resulting in a YTD increase of 2.4%. While y/y growth in household credit remains a limited 2.3%, annualized growth over the past four months is a stronger 4.7%. Business credit inched up by 0.2% in October, pushing YTD growth to 3.6% (2.9% y/y). Industry and trade drove business credit growth in October while construction and trade are the fastest growing YTD at 17% and 8%, respectively. In contrast, the oil/gas sector continued its downtrend, deepening the YTD decrease to 13%. Excluding the oil/gas sector, growth in business credit would increase to a relatively good 5% YTD. Looking ahead, the last couple of months of the year (especially December) are usually the weakest for business credit, likely due to increased repayments and write-offs, but it will not be surprising if the recovery in household credit is generally sustained, especially given the commencement of the interest rate-cutting cycle. Meanwhile, driven by a plunge in the volatile public-institution deposits, resident deposits decreased in October, resulting in YTD growth of 2.4% (4.2% y/y). Private-sector deposits inched up in October driving up YTD growth to 4.5% compared with 10% for government deposits while public-institution deposits are a big drag (-14%). Within private-sector KD deposits, CASA showed further signs of stabilization as there was no decrease for the third straight month while the YTD drawdown is a limited 1%.

Chart 1: Kuwait credit growth

(% y/y)

Source: Central Bank of Kuwait (CBK)
Chart 2: UK inflation

(%)

Source: Haver

Egypt: IMF concludes mission for fourth review, sees external risks. The IMF concluded its visit to Egypt after spending close to 2 weeks, holding several in-person meetings with the Egyptian authorities, private sector, and other stakeholders. The IMF released a statement mentioning that the current ongoing geopolitical tensions in the region in addition to an increasing number of refugees have affected the external sector (Suez Canal receipts down by 70%) and put severe pressure on the fiscal front. The Fund acknowledged the Central Bank of Egypt’s commitment to unify the exchange rate, maintain the flexible exchange rate regime, and keep inflation on a firm downward trend over the medium term by substantially tightening monetary policy. It also highlighted that continued policy discipline was also a key to containing fiscal risks, especially those related to the energy sector. The Fund, as always, re-iterated the need for promoting the private sector mainly through an enhanced tax system and accelerating divestment plans of the state firms. Finally, it also said that the discussions would continue over the coming days to finalize the agreement on the remaining policies and reform plans. However, the release did not provide any clear hints about the conclusion on the government’s earlier request to push the timeline of some of the subsidy moves.

Oman: IMF completes article IV with a strong outlook for the economy in 2025. Oman’s economy continued to expand with growth reaching 1.9% in the first half of 2024 (versus 1.2% in 2023), despite being weighed down by OPEC+ mandated oil production cuts as non-oil GDP grew a stronger 3.8% y/y in H1 (versus 1.8% in 2023). The fiscal and current account balances remain in a comfortable situation evident by a decline in public sector debt and the recent rating upgrade to investment grade. The Fund expects Oman’s economic growth to see a strong rebound in 2025, supported by higher oil production. It also believes that fiscal and current account balances will remain in surplus but at lower levels. Key risks to the outlook stem from oil price volatility and intensifying geopolitical tensions. The IMF also mentioned that further efforts are needed to raise nonhydrocarbon revenues through more tax policy measures and the phasing out of untargeted subsidies which should help in freeing up resources to finance growth under the government’s diversification agenda.

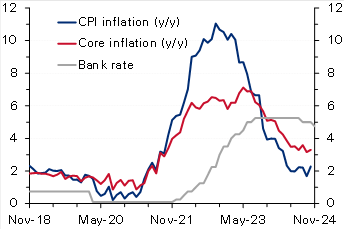
UK: Inflation rises more than forecast, reinforcing BoE’s caution on rate cuts. UK CPI inflation increased to 2.3% y/y in October from 1.7% the previous month, slightly above the market and the Bank of England’s forecast of 2.2%. On a monthly basis too, inflation rose to 0.6%, a seven-month high, from September’s no change. The steep rise was mainly driven by an almost 10% rise in the household energy price cap effective from October. Core inflation also accelerated to 3.3% y/y (0.4% m/m) from 3.2% (0.1% m/m). While goods prices continued to fall (-0.3% y/y), service prices rose at a faster rate of 5% from 4.9%. Recently, the Bank of England had cautioned about inflation quickening next year (projecting a peak rate of 2.8% in Q3 2025), citing the impact of higher insurance contributions and rising minimum wages as outlined in the latest government budget. Therefore, with inflation rising above forecast, the bank will likely slow the pace of monetary easing after delivering two interest rate cuts of 25 bps earlier, with markets now seeing only two additional cuts by the end of 2025.

Eurozone: ECB warns of fiscal and growth risks in its latest Financial Stability Review [archived PDF]. In its most recent Financial Stability Review (November) [archived PDF], the European Central Bank warned that elevated debt and fiscal deficit levels and anemic long-term growth could expose sovereign debt vulnerabilities in the region, stoking concerns of a repeat of the 2011 sovereign debt crisis. Maturing debt being rolled over at much higher borrowing rates raising debt service costs poses risks to countries with little fiscal space and leaves certain governments exposed to market fluctuations. The bank also emphasized the risks of high equity valuations, low liquidity and a greater concentration of exposure among non-banks. Moreover, it sees current geopolitical uncertainties and the possibility of more trade tensions as heightening risks. The Eurozone’s current government debt-to-GDP ratio stands at 88%, but the underlying data suggest a much more precarious situation with Greece, Italy, and France’s ratios at 164%, 137% and 112%. Recently, concerns about France’s high fiscal deficit (around 5.9% of GDP) and elevated debt levels saw yields on the country’s bonds rise steeply, widening the spread gap with German bonds to the highest level in over a decade.

Stock marketsIndexDaily Change (%)YTD Change (%)
Regional
Abu Dhabi (ADI)9,405-0.23-1.80
Bahrain (ASI)2,043-0.373.62
Dubai (DFMGI)4,7610.6117.26
Egypt (EGX 30)30,588-0.33 23.18
GCC (S&P GCC 40)7090.09-0.52
Kuwait (All Share)7,353-0.087.86
KSA (TASI)11,868-0.07-0.83
Oman (MSM 30)4,6090.002.10
Qatar (QE Index)10,4380.12-3.62
International
CSI 3003,9860.2216.17
DAX19,005-0.2913.45
DJIA43,4080.3215.17
Eurostoxx 504,730-0.454.60
FTSE 1008,085-0.174.55
Nikkei 22538,352-0.1614.61
S&P 5005,9170.0024.05
3m interbank rates%Daily Change (bps)YTD Change (bps)
Bahrain5.86-1.29-66.34
Kuwait3.940.00-37.50
Qatar6.000.00-25.00
UAE4.433.81-89.96
Saudi5.50-4.75-73.14
SOFR4.52-0.09-81.13
Bond yields%Daily Change (bps)YTD Change (bps)
Regional
Abu Dhabi 20274.665.0033.9
Oman 20275.496.0033.0
Qatar 20264.686.0016.1
Kuwait 20274.693.0035.0
Saudi 20284.961.0043.9
International 10-year
US Treasury4.411.7755.3
German Bund2.340.3531.2
UK Gilt4.472.6093.0
Japanese Gov’t Bond1.071.045.4
Exchange ratesRateDaily Change (%)YTD Change (%)
KWD per USD0.310.04-0.05
KWD per EUR0.32-0.46-1.98
USD per EUR1.05-0.49-4.47
JPY per USD155.430.5010.19
USD per GBP1.27-0.25-0.62
EGP per USD49.670.3461.00
Commodities$/unitDaily Change (%)YTD Change (%)
Brent crude72.81-0.68-5.49
KEC73.780.74-7.26
WTI68.87-0.75-3.88
Gold2,648.20.8028.40

Disclaimer: While every care has been taken in preparing this publication, National Bank of Kuwait accepts no liability whatsoever for any direct or consequential losses arising from its use. Daily Economic Update is distributed on a complimentary and discretionary basis to NBK clients and associates. This report and previous issues can be found in the “News & Insight / Economic Reports” section of the National Bank of Kuwait’s web site. Please visit their web site, nbk.com, for other bank publications.

“De-Globalization?”

The classic study of the “swirl of processes and events” that ended previous globalization episodes is the theme of Princeton Professor Harold James’ 2002 book, The End of Globalization: Lessons from the Great Depression.

“Globalization” is here. Signified by an increasingly close economic interconnection that has led to profound political and social change worldwide, the process seems irreversible. In this book, however, Harold James provides a sobering historical perspective, exploring the circumstances in which the globally integrated world of an earlier era broke down under the pressure of unexpected events.

James examines one of the great historical nightmares of the twentieth century: the collapse of globalism in the Great Depression. Analyzing this collapse in terms of three main components of global economics—capital flows, trade and international migration—James argues that it was not simply a consequence of the strains of World War I, but resulted from the interplay of resentments against all these elements of mobility, as well as from the policies and institutions designed to assuage the threats of globalism.

Could it happen again? There are significant parallels today: highly integrated systems are inherently vulnerable to collapse, and world financial markets are vulnerable and unstable.

While James does not foresee another Great Depression, his book provides a cautionary tale in which institutions meant to save the world from the consequences of globalization—think WTO and IMF, in our own time—ended by destroying both prosperity and peace.

Legitimate fears about “globalization reversal” have been well put by Zakaria:

Davos, Switzerland —

President Trump’s speech here at the World Economic Forum went over relatively well. That’s partly because Davos is a conclave of business executives, and they like Trump’s pro-business message. But mostly, the president’s reception was a testament to the fact that he and what he represents are no longer unusual or exceptional. Look around the world and you will see: Trump and Trumpism have become normalized.

Davos was once the place where countries clamored to demonstrate their commitment to opening up their economies and societies. After all, these forces were producing global growth and lifting hundreds of millions out of poverty. Every year, a different nation would become the star of the forum, usually with a celebrated finance minister who was seen as the architect of a boom. The United States was the most energetic promoter of these twin ideas of economic openness and political freedom.

Today, Davos feels very different. Despite the fact that, throughout the world, growth remains solid and countries are moving ahead, the tenor of the times has changed. Where globalization was once the main topic, today it is the populist backlash to it. Where once there was a firm conviction about the way of the future, today there is uncertainty and unease.

This is not simply atmospherics and rhetoric. Ruchir Sharma of Morgan Stanley Investment Management points out that since 2008, we have entered a phase of “deglobalization.” Global trade, which rose almost uninterruptedly since the 1970s, has stagnated, while capital flows have fallen. Net migration flows from poor countries to rich ones have also dropped. In 2018, net migration to the United States hit its lowest point in a decade.

The shift in approach can best be seen in the case of India. In 2018, Prime Minister Narendra Modi came to Davos to decry the fact that “many countries are becoming inward focused and globalization is shrinking.” Since then, his government has increased tariffs on hundreds of items and taken steps to shield India’s farmers, shopkeepers, digital companies and many others from the dangers of international competition. The Office of the U.S. Trade Representative recently called out India for having the highest tariffs of any major economy in the world.

Indian officials used to aggressively court foreign investment, which was much needed to spur growth. Last week, with India’s economy slowing badly, Jeff Bezos announced a $1 billion investment in the country. (Bezos owns The Post.) But the minister of commerce and industry scoffed at the move, saying Amazon wasn’t “doing a great favor to India” and besides was probably engaging in anti-competitive, “predatory” practices. Often, protectionist policies help favored local producers. Malaysian Prime Minister Mahathir Mohamad recently criticized some of Modi’s policies toward Muslims. The Indian government effectively cut off imports of Malaysian palm oil. In a familiar pattern, one of the chief beneficiaries was a local billionaire long associated with Modi.

The Economist notes that Europe, once one of the chief motors for openness in economics and politics, is also rediscovering state intervention to prop up domestic industries. And if you think the Internet is exempt from these tendencies, think again. The European Center for International Political Economy tracks the number of protectionist measures put in place to “localize” the digital economy in 64 countries. It has been surging for years, especially since 2008.

It’s important not to exaggerate the backlash to globalization.

As a 2019 report by DHL demonstrates, globalization is still strong and, by some measures, continues to expand. People still want to trade, travel and transact across the world. But in government policy, where economic logic once trumped politics, today it is often the reverse. Economist Nouriel Roubini argues that the cumulative result of all these measures — protecting local industries, subsidizing national champions, restricting immigration — is to sap growth. “It means slower growth, fewer jobs, less efficient economies,” he told me recently. We’ve seen it happen many times in the past, not least in India, which suffered decades of stagnation as a result of protectionist policies, and we will see the impact in years to come.

Nevertheless, today, nationalism and protectionism prevail.

This phase of deglobalization is being steered from the top. The world’s leading nations are, as always, the agenda-setters. The example of China, which has shielded some of its markets and still grown rapidly, has made a deep impression on much of the world. Probably deeper still is the example of the planet’s greatest champion of liberty and openness, the United States, which now has a president who calls for managed trade, more limited immigration and protectionist measures. At Davos, Trump invited every nation to follow his example. More and more are complying.

“The world is de-globalizing. Trump set the example.” The Washington Post, Fareed Zakaria

Students should sense that while history does not repeat itself, it sometimes rhymes and this is a major danger. It also might imply that coping with climate change will be all the harder because American-led unilateralism everywhere would mean world policy paralysis.

Economics-Watching: How Green Innovation Can Stimulate Economies and Curb Emissions

[from IMF Blog, by Zeina Hasna, Florence Jaumotte & Samuel Pienknagura]

Coordinated climate policies can spur innovation in low-carbon technologies and help them spread to emerging markets and developing economies

Making low-carbon technologies cheaper and more widely available is crucial to reducing harmful emissions.

We have seen decades of progress in green innovation for mitigation and adaptation: from electric cars and clean hydrogen to renewable energy and battery storage.

More recently though, momentum in green innovation has slowed. And promising technologies aren’t spreading fast enough to lower-income countries, where they can be especially helpful to curbing emissions. Green innovation peaked at 10 percent of total patent filings in 2010 and has experienced a mild decline since. The slowdown reflects various factors, including hydraulic fracking that has lowered the price of oil and technological maturity in some initial technologies such as renewables, which slows the pace of innovation.

The slower momentum is concerning because, as we show in a new staff discussion note, green innovation is not only good for containing climate change, but for stimulating economic growth too. As the world confronts one of the weakest five-year growth outlooks in more than three decades, those dual benefits are particularly appealing. They ease concerns about the costs of pursuing more ambitious climate plans. And when countries act jointly on climate, we can speed up low-carbon innovation and its transfer to emerging markets and developing economies.

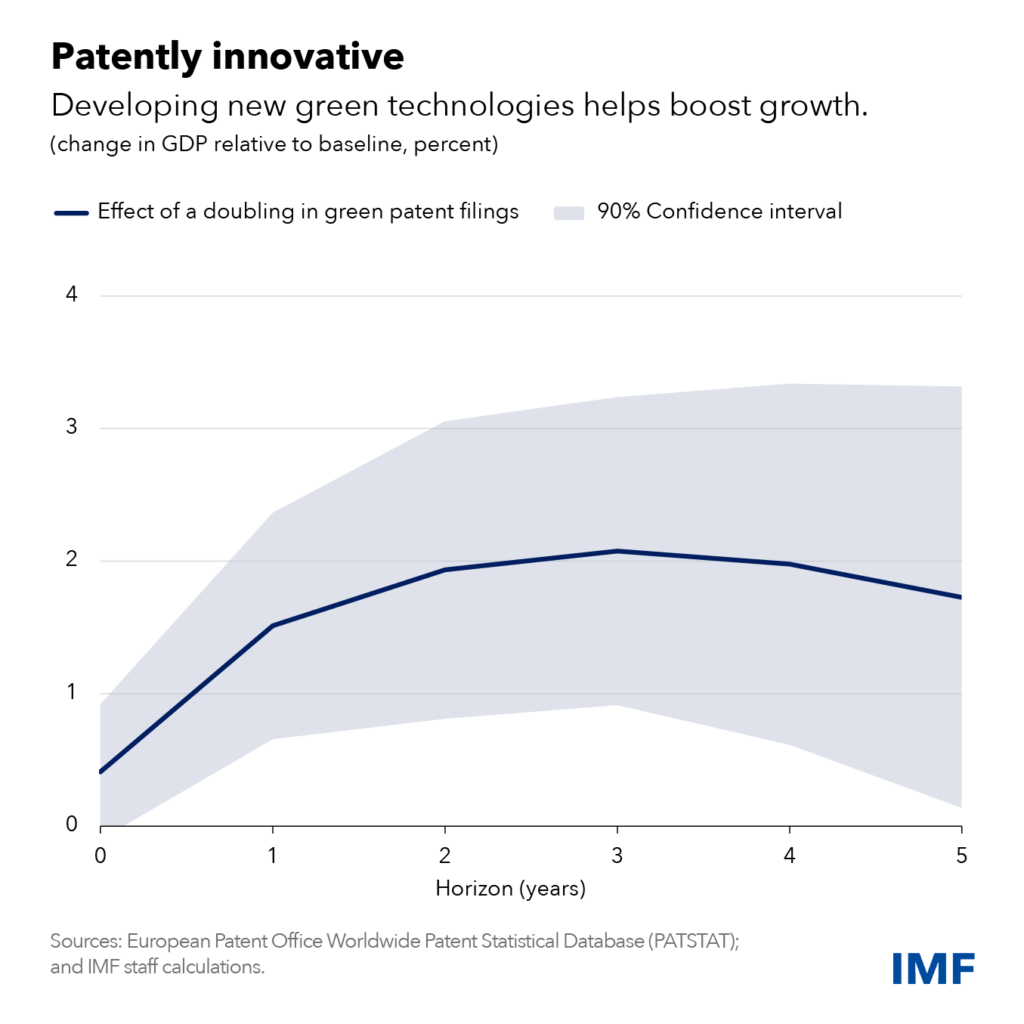
IMF research [archived PDF] shows that doubling green patent filings can boost gross domestic product by 1.7 percent after five years compared with a baseline scenario. And that’s under our most conservative estimate—other estimates show up to four times the effect.

The economic benefits of green innovation mostly flow through increased investment in the first few years. Over time, further growth benefits come from cheaper energy and production processes that are more energy efficient. Most importantly, they come from less global warming and less frequent (and less costly) climate disasters.

Green innovation is associated with more innovation overall, not just a substitution of green technologies for other kinds. This may be because green technologies often require complementary innovation. More innovation usually means more economic growth.

A key question is how countries can better foster green innovation and its deployment. We highlight how domestic and global climate policies spur green innovation. For example, a big increase in the number of climate policies tends to boost green patent filings, our preferred proxy for green innovation, by 10 percent within five years.

Some of the most effective policies to stimulate green innovation include emissions-trading schemes that cap emissions, feed-in-tariffs, which guarantee a minimum price for renewable energy producers, and government spending, such as subsidies for research and development. What’s more, global climate policies result in much larger increases in green innovation than domestic initiatives alone. International pacts like the Kyoto Protocol and the Paris Agreement amplify the impact of domestic policies on green innovation.

One reason policy synchronization has a prominent impact on domestic green innovation is what is called the market size effect. There’s more incentive to develop low-carbon technologies if innovators can expect to sell into a much larger potential market, that is, in countries which adopted similar climate policies.

Another is that climate policies in other countries generate green innovations and knowledge that can be used in the domestic economy. This is known as technology diffusion. Finally, synchronized policy action and international climate commitments create more certainty around domestic climate policies, as they boost people’s confidence in governments’ commitment to addressing climate change.

Climate policies even help spread the use of low-carbon technologies in countries that are not sources of innovation, through trade and foreign-direct investment. Countries that introduce climate policies see more imports of low-carbon technologies and higher green FDI inflows, especially in emerging markets and developing economies.

Risks of protectionism

Lowering tariffs on low-carbon technologies can further enhance trade and FDI in green technologies. This is especially important for middle- and low-income countries where such tariffs remain high. On the flipside, more protectionist measures would impede the broader spread of low-carbon technologies.

In addition, and given evidence of economies of scale, protectionism—with ultimately smaller potential markets—could stifle incentives for green innovation and lead to duplication of efforts across countries.

The risks of protectionism are exacerbated when climate policies, such as subsidies, do not abide by international rules. For example, local content requirements, whereby only locally produced green goods benefit from subsidies, undermine trust in multilateral trade rules and could result in retaliatory measures.

Beyond embracing a rules-based approach to climate policies, the advanced economies, where most green innovation occurs, have an important responsibility: sharing the technology so that emerging and developing economies can get there faster. Such direct technology transfers hold the promise of a double dividend for emerging markets and developing economies—reducing emissions and yielding economic benefits.

—This blog reflects research by Zeina Hasna, Florence Jaumotte, Jaden Kim, Samuel Pienknagura and Gregor Schwerhoff.

Economy-Watching, USA: Global Supply Chain Pressure Index: April 2023 Update

[from the Federal Reserve Bank of New York]

A new reading of the Global Supply Chain Pressure Index has been posted.

Estimates for March 2023

  • Global supply chain pressures decreased again in March, falling from 0.28 to 1.06 standard deviations below the index’s historical average.
  • There were significant downward contributions by many of the factors, with the largest negative contributions from European Area delivery times, European Area backlogs, and Taiwanese purchases.
  • The GSCPI’s recent movements suggest that global supply chain conditions have largely normalized after experiencing temporary setbacks around the turn of the year.

The GSCPI compiles more than two dozen metrics across seven economies—data on global transportation costs and regional manufacturing conditions—to track shifts in supply chain pressures from 1997 to the present.

The GSCPI is updated regularly at 10 AM ET on the fourth business day of each month.

The GSCPI is a product of the Federal Reserve Bank of New York’s Applied Macroeconomics and Econometrics Center.

View the index.

Economy-Watching, USA: First-Quarter GDP Growth Estimate Decreased

[from the Federal Reserve Bank of Atlanta]

GDPNow

First-Quarter GDP Growth Estimate Decreased

On April 5, the GDPNow model estimate for real GDP growth in the first quarter of 2023 is 1.5 percent, down from 1.7 percent on April 3.

The next GDPNow update is Monday, April 10.

Want to see even more economic data? The Atlanta Fed’s EconomyNow app will put GDPNow and all its data tools right in your hands. Download it today to see the latest data on inflation, growth, and the labor market.