Henry Huiyao Wang: A New Compact for China and Europe

CCG President outlines opportunities for China and Europe to deepen cooperation in trade, investment, climate action, and global governance.

[from the Center for China & Globalization, 7 November 2026]

Henry Huiyao Wang [王辉耀], Founder and President of the Center for China & Globalization (CCG), has published an article titled “A New Compact for China and Europe” in the Autumn 2026 issue (No. 36) of Horizons, a journal published by the Center for International Relations and Sustainable Development (CIRSD).
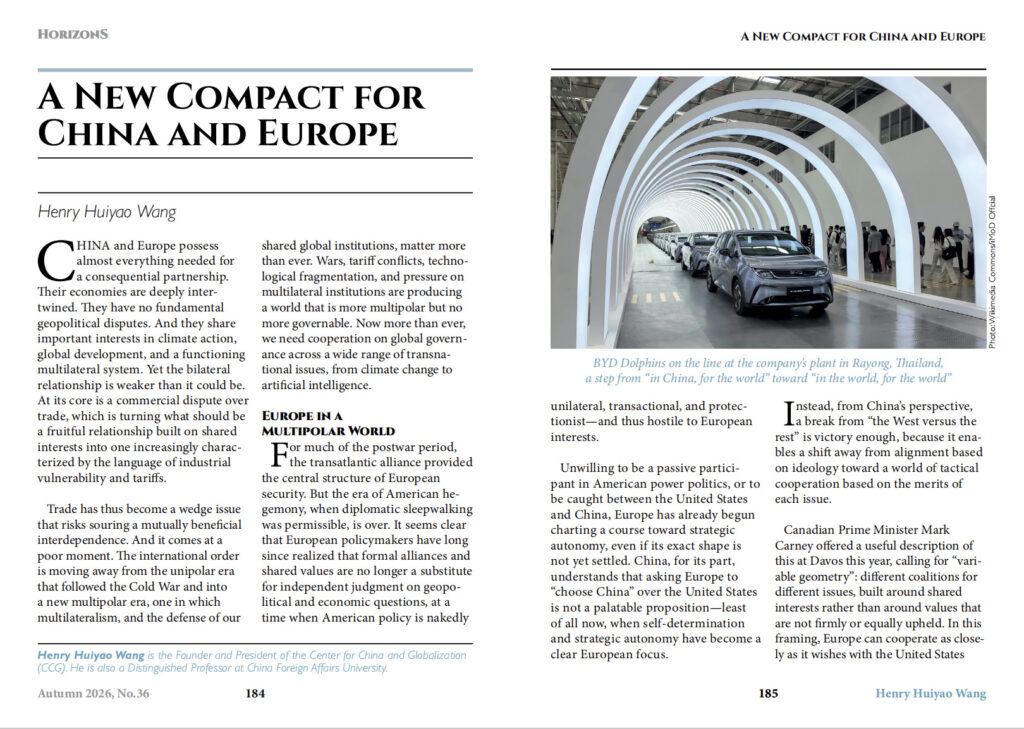
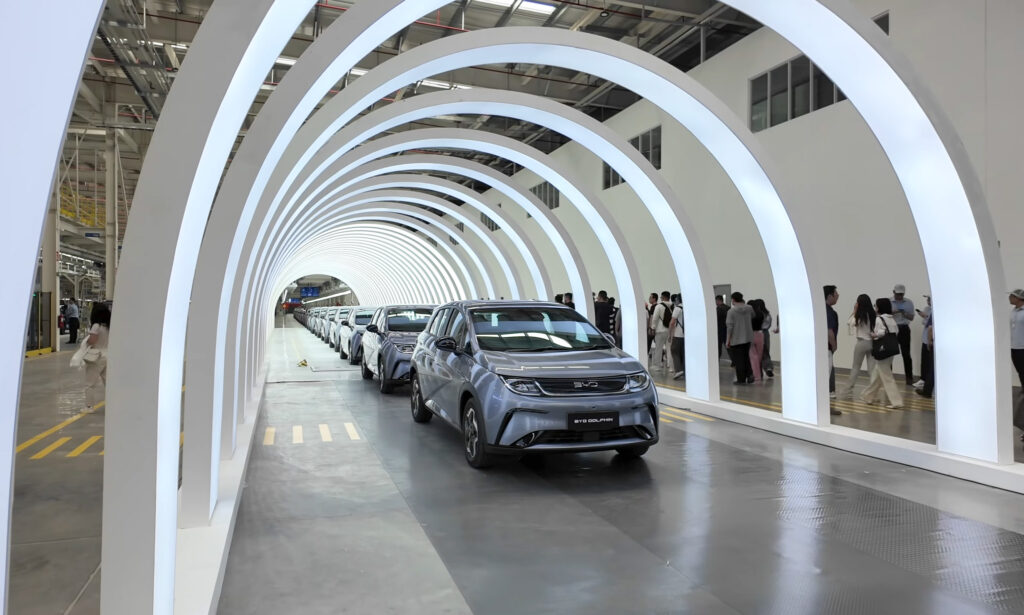
BYD Dolphins on the line at the company’s plant in Rayong, Thailand, a step from “in China, for the world” toward “in the world, for the world”
Wikimedia Commons/iMoD Official

China and Europe possess almost everything needed for a consequential partnership. Their economies are deeply intertwined. They have no fundamental geopolitical disputes. And they share important interests in climate action, global development, and a functioning multilateral system. Yet the bilateral relationship is weaker than it could be. At its core is a commercial dispute over trade, which is turning what should be a fruitful relationship built on shared interests into one increasingly characterized by the language of industrial vulnerability and tariffs.

Trade has thus become a wedge issue that risks souring a mutually beneficial interdependence. And it comes at a poor moment. The international order is moving away from the unipolar era that followed the Cold War and into a new multipolar era, one in which multilateralism, and the defense of our shared global institutions, matter more than ever. Wars, tariff conflicts, technological fragmentation, and pressure on multilateral institutions are producing a world that is more multipolar but no more governable. Now more than ever, we need cooperation on global governance across a wide range of transnational issues, from climate change to artificial intelligence.

Europe in a Multipolar World

For much of the postwar period, the transatlantic alliance provided the central structure of European security. But the era of American hegemony, when diplomatic sleepwalking was permissible, is over. It seems clear that European policymakers have long since realized that formal alliances and shared values are no longer a substitute for independent judgment on geopolitical and economic questions, at a time when American policy is nakedly unilateral, transactional, and protectionist—and thus hostile to European interests.

Unwilling to be a passive participant in American power politics, or to be caught between the United States and China, Europe has already begun charting a course toward strategic autonomy, even if its exact shape is not yet settled. China, for its part, understands that asking Europe to “choose China” over the United States is not a palatable proposition—least of all now, when self-determination and strategic autonomy have become a clear European focus.

Instead, from China’s perspective, a break from “the West versus the rest” is victory enough, because it enables a shift away from alignment based on ideology toward a world of tactical cooperation based on the merits of each issue.

Canadian Prime Minister Mark Carney offered a useful description of this at Davos this year, calling for “variable geometry”: different coalitions for different issues, built around shared interests rather than around values that are not firmly or equally upheld. In this framing, Europe can cooperate as closely as it wishes with the United States on defense, while still finding common cause with China on climate and trade reform, or with India on development. Such flexibility is increasingly the default in our plural world.

A cohesive Europe able to act independently is preferable to a divided continent whose China policy is increasingly shaped elsewhere. But that also means that policymakers in China must address European fears if they are to benefit from engagement and cooperation on shared interests.

The Changing Bargain

The core anxiety facing Europe, and the one undermining a merits-based relationship, is that the old, unspoken economic bargain—European technology and premium manufacturing in exchange for Chinese consumer goods and lower-cost production—is giving way to a more competitive relationship.

China now possesses broad industrial ecosystems, world-class infrastructure, skilled engineering talent, and the capacity for fast commercialization at scale. It no longer competes on wages alone. In electric vehicles, batteries, solar energy, machinery, telecommunications equipment, and, increasingly, advanced digital applications, Chinese firms can combine cost, speed, and technological capability.

But let us not get carried away with catastrophizing. The shared economic foundation between China and the EU remains immense. In 2025, two-way trade in goods and services exceeded €880 billion. Europe imported more than €570 billion in goods from China and exported about €200 billion, producing a large bilateral goods deficit. Yet this figure should be interpreted carefully. The European Union still recorded an overall goods surplus of approximately €128 billion in 2025, as well as a substantial current-account surplus. Nor are all imports finished products: Eurostat data shows that 57 percent of all extra-EU goods imports in 2025 were intermediate products, meaning that much of what Europe imports feeds into value-added production chains from which Europe itself benefits. Europe’s difficulty is that, while its industry remains broadly profitable, certain critical sectors are already under pressure, and the trend seems unlikely to reverse suddenly in favor of European manufacturing.

Europe is not facing this crisis in a vacuum, either. It is compounded by high energy costs, aging populations, fragmented capital markets, and chronic underinvestment. The result is a genuine fear of deindustrialization, with the attendant loss of skilled employment, supplier networks, technological capacity, and social cohesion. This worry is especially potent in the major European economies with large export-oriented manufacturing sectors, such as Germany, France, Italy, and Spain, and it makes the debate over “overcapacity” deeply politically charged.

While the imbalance is a product of industrial excellence, it can also be attributed to weak domestic demand in China. Household consumption there remains around 40 percent of GDP, while families save heavily out of concern over housing, education, health care, and retirement. The 2025 consumption action plan addressed wages, pensions, health care, childcare, paid leave, and benefits for migrant and flexible workers, and China’s first five-year plan devoted specifically to consumption subsequently set a goal of approximately 60 trillion yuan in retail sales by 2030. But it is far too early to call the effort complete. Although per capita disposable income rose by 5 percent and consumption expenditure by 4.4 percent in 2025, the first half of 2026 was weaker, and overall consumption still lags behind where it should be. Stronger pensions, health care, unemployment insurance, childcare, and portable benefits for migrant workers will help reduce precautionary saving, and greater access for foreign goods and services would ensure that stronger Chinese demand creates opportunities for European producers. That transformation, however, is not yet complete.

Europe, for its part, should recognize that competitive success is not in itself an unfair subsidy. The International Energy Agency estimates that producing a battery-electric vehicle costs more than 30 percent less in China than in advanced economies, with only about one-third of the gap attributable to the battery; a similar cost gap exists for conventional vehicles. China’s earlier industrial policies undoubtedly helped establish this ecosystem, but important forms of direct support, including national EV purchase subsidies, have already been phased out.

Rhodium Group estimates that BYD enjoys a cost advantage of approximately $4,700 per vehicle over Tesla’s operations in China, of which grants account for only about $292, while vertical integration and lower research, administrative, and supplier costs explain at least three-quarters of the difference. BYD produces roughly 70 percent of its components in-house, including its batteries. Europe should investigate market-distorting support and is right to insist on transparency, but it should not define the ecosystem, technology, and efficiencies China has built as unfair.

Nor is China’s automobile sector insulated from competition. The number of Chinese electric-vehicle makers was reported at 487 in 2018; by 2025, consolidation had reduced the market to approximately 129 brands produced by about 50 manufacturers, and only 10 to 15 are expected to be profitable by 2030. China exported approximately 5.86 million of the more than 31 million vehicles it sold in 2024, meaning that the large majority were still absorbed at home. By comparison, Volkswagen delivered 9.03 million vehicles worldwide but only 1.12 million in Germany, while Toyota and Lexus sold 10.16 million worldwide and 1.44 million in Japan. Airbus, likewise, sells approximately 68 percent of its aircraft outside Europe. Producing for global markets is accepted as normal when established European or Japanese companies do it; it should not automatically become illegitimate when Chinese firms do the same.

China’s textile industry offers a further precedent. Even as wages rose and some production moved to Vietnam, Bangladesh, and elsewhere, China retained 37 percent of global textile exports and 34 percent of clothing exports in 2017, because supplier clusters, infrastructure, skills, and continual upgrading proved more durable than low labor costs alone.

Beyond economic competition, clearer rules are urgently needed on the securitization of critical industries. The dispute over Nexperia—the Chinese-owned semiconductor company placed under Dutch government control in 2025—rattled supply chains and deepened concern in China about investing abroad. Either the company should not have been sold in the first place, or a clearer regulatory environment might have avoided a quasi-nationalization that rapidly internationalized a corporate dispute, and that still hangs over the mutual investment relationship today.

Likewise, proposals for a European instrument modeled on the United States’ Section 301 powers may offer political reassurance, but Section 301 is a blunt unilateral instrument designed to authorize retaliation. Europe would be better served by an explicitly transitional mechanism. Where an import surge threatens to destabilize domestic markets, temporary safeguards can provide time for adjustment, but they should be evidence-based, reviewable, and subject to firm sunset clauses. Their purpose should be to facilitate adaptation and negotiation, not to turn emergency protection into a permanent wall.

An Industrial Compact for Shared Competitiveness

When I visited Jean Monnet’s house outside Paris this summer, I was reminded of the method that helped build modern Europe: begin with concrete achievements that create the basis for solidarity. That method matters especially now, when trade has become a wedge issue and trust and trade cannot be separated.

We must therefore build a new industrial compact: one that aligns Chinese industrial capacity with Europe’s need for investment, innovation, and employment, and that enables China and Europe to stand together in support of a world of free, fair, and open trade.

First, China should follow through on its ongoing shift from an export– and investment-heavy model toward consumption-led growth. Alongside the social measures described above, this requires reducing the barriers faced by private and foreign businesses, improving market access in services and public procurement, and applying regulation more transparently. European companies should be able to compete in China with confidence that they will receive equal treatment and can protect their intellectual property.

Second, Europe needs to draw a sharper distinction between trade in products that present a genuine security risk and investment that strengthens European productive capacity. Concerns about supply-chain resilience and security in defined strategic sectors are unavoidable, given increasing regionalization. But a presumption against Chinese investment would deprive Europe of capital, technology, competition, and jobs precisely when it needs them most. Instead, Europe could openly welcome investment that meets its requirements on governance, data protection, labor standards, and environmental performance, while increasing the local economic contribution such production provides.

This openness should be anchored by a renewed Comprehensive Agreement on Investment. The agreement reached in principle in 2020 was never implemented and the relationship has changed too much for it simply to be revived unchanged. China and Europe should instead negotiate a new CAI covering market access, national treatment, subsidy transparency, technology transfer, public procurement, and enforceable dispute resolution. It should give European companies more predictable access to China, while establishing clear and consistent conditions for Chinese market access and investment in Europe, with an eye to creating employment and supplier networks there.

China has already demonstrated the value it places on market access by extending tariff-free treatment to goods from 53 African countries, and it could move explicitly to align its standards more closely with Europe’s. Europe, for its part, should reconsider its technology and investment restrictions—especially those implemented specifically to protect U.S. interests, such as the restrictions preventing China from purchasing advanced semiconductor equipment from ASML. Working examples of Chinese investment in Europe already exist. Chinese companies are investing in battery and vehicle production in Hungary, Slovakia, Spain, and Serbia, while European manufacturers—including Volkswagen, BMW, and Mercedes-Benz—continue to deepen their research, production, and partnership networks in China. These investments should not be viewed as isolated commercial transactions. They can become the architecture of a more balanced relationship.

Third, localization must mean more than final assembly. Joint ventures and investment agreements can encourage local supplier development, worker training, research partnerships, and the sharing of production know-how, while respecting intellectual-property rights. Chinese industry was once buoyed by European know-how through joint ventures; in return, European industry can now benefit from Chinese advances. The goal should be a competitive ecosystem in which both Chinese and European firms have a stake.

Fourth, any trade measures should be targeted and temporary. If an import surge threatens serious injury, safeguards can buy time for adaptation. But they should have clear evidentiary thresholds, sunset clauses, and review procedures. Protection without a productivity strategy merely postpones decline and risks marginalization, rather than allowing a dynamic industrial sector to emerge. At the same time, Europe can and should complete its own agenda: lowering energy costs, deepening the single market, mobilizing investment, scaling up innovative companies, and improving infrastructure.

Here, China can become Europe’s “fitness partner.” The phrase may sound counterintuitive at a moment of industrial anxiety, but the underlying idea is important. Healthy competition from China can push European companies and governments to confront long-delayed reforms, reduce costs, and innovate faster. Shelter from competitive pressure does not create health; competition, by contrast, can serve as a yardstick for rebuilding strength. China, meanwhile, gains more from a prosperous and capable Europe than from a weakened market increasingly hostile to Chinese commerce.

Finally, the compact should look beyond the bilateral market. Chinese and European joint ventures could look abroad, toward the product and development needs of the Global South. Joint production for Global South markets could be a starting point, moving in time toward joint financing of development and infrastructure to accelerate green industrialization in Africa, Asia, Latin America, and the Middle East.

This would represent the next stage of globalization: not simply Chinese companies “in China, for the world,” but “in the world, for the world.” It would spread productive capacity more widely, answer concerns about concentrated supply chains, and make development a shared undertaking rather than an arena for geopolitical competition.

From Commercial Trust to Strategic Cooperation

An industrial compact cannot by itself remove all political differences. But it would serve as a springboard, and a trust-building exercise, for deeper commitments and further work on shared interests.

Climate cooperation is the most obvious bridge. China’s manufacturing scale has lowered the global cost of solar panels, batteries, and electric vehicles, in a very real way underwriting the transition away from fossil fuels. At the same time, Europe is suffering under the weight of an energy crisis born of Russia’s invasion of Ukraine and, more recently, of upheavals in the Middle East around the Strait of Hormuz and the Bab al-Mandeb. A natural alignment would be for China and Europe to build a green partnership that helps wean the world off volatile fossil fuels and address the climate crisis. The exact shape of such measures is not yet defined, but using joint ventures, cooperation, and technology exchange to tap Chinese expertise and cost advantages could benefit both sides while buoying the global green transition. A tariff spiral in clean technology, by contrast, would make the energy transition slower and more expensive for everyone.

More broadly, China and Europe share an interest in conflict resolution. China has always been clear that sovereignty and territorial integrity apply universally, that nuclear escalation is unacceptable, and that a negotiated settlement must provide credible security for all parties. But it can do more to ease the concerns of a Europe that feels threatened by a Russia now in its fifth year of fighting in Ukraine. Working together, Europe and China could help provide an off-ramp, each using its leverage to bring the negotiating positions closer together. A truly durable settlement, acceptable to both sides, may eventually require security guarantees involving both European and non-European countries, and China could contribute through reconstruction, nuclear safety, and peacekeeping. The Middle East is another region where common interests are greater than current policy coordination suggests. Continued conflict and volatility around the straits have not only given fresh impetus to the transition away from fossil fuels but also created a new area of shared interest. Together, Europe and China could support a peace architecture with wider international participation.

Artificial intelligence governance is another opportunity. China and Europe approach data, platforms, and regulation differently, but both reject a future in which a handful of private companies set global rules without public accountability. They can work together on safety testing, scientific exchange, interoperable standards, and the application of AI to health, climate, and development. Agreement will be difficult, but building a shared environment for rule-making would help hedge against fragmentation in this rapidly developing field.

Finally, China and the EU have both long advocated restoring the World Trade Organization. A revitalized WTO already contains tools to address subsidies and demonstrable injury. Boeing and Airbus were both found, in WTO disputes, to have benefited from improper support, and those cases were handled through multilateral proceedings rather than through an open-ended campaign against either side’s wider industrial success. The WTO’s dispute-settlement system must now be restored, its rules on subsidies and state enterprises updated, and its development functions strengthened. The United States weakened that system by blocking appointments to the Appellate Body after adverse rulings; but China and Europe are both major beneficiaries of an open trading system, and both can press for reform.

None of this will be sustainable without renewed contact between societies. Direct flights, student exchanges, tourism, university partnerships, city-to-city links, and think-tank dialogue all have their roles to play, for they are the infrastructure of mutual understanding.

China–Europe relations will not always be perfectly aligned, and they will likely continue to contain elements of cooperation, competition, and disagreement. But together, we can put to rest the prospect of weaponized interdependence and move instead toward win-win interdependence.

Europe does not need to become less European in order to cooperate with China, nor does China need to adopt European political mores for cooperation to succeed. Both are now free to cooperate selectively and on the merits of each issue. And a world in which China and Europe cannot find areas of deep mutual interest—despite their deep economic ties and their shared stake in multilateralism—is a world that is measurably poorer for it.
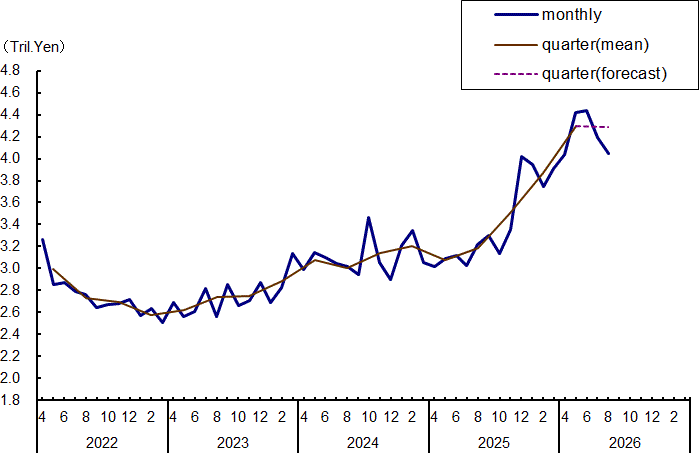
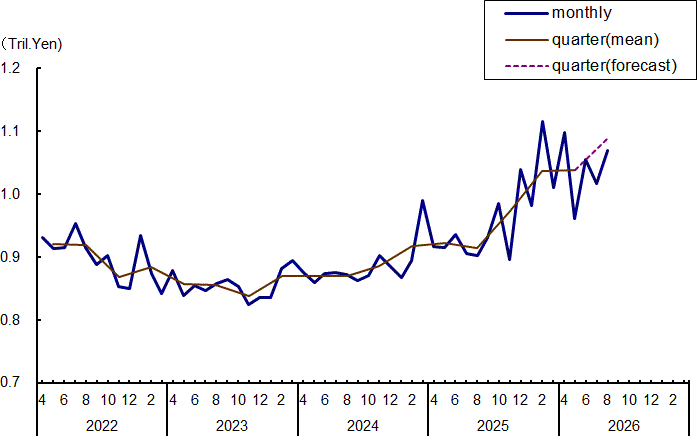
Japan-Watching: Machinery Orders in August, 2026

[from Japan’s Cabinet Office (内閣府) Economic and Social Research]

Results

  1. The total value of machinery orders received by 280 manufacturers operating in Japan decreased by 3.7% in August from the previous month on a seasonally adjusted basis.
  2. Private-sector machinery orders, excluding volatile ones for ships and those from electric power companies, increased a seasonally adjusted by 5.2% in August.

Percentage change from previous quarter (month)

(%)

2025
Jul-Sep
Oct-Dec2026
Jan-Mar
Apr-JunJul-Sep
(forecast)
2026
May
JunJulAug
Total3.510.210.311.3-0.19.50.4-5.5-3.7
private sector-1.36.22.614.6-3.837.4-26.01.5-4.2
(exc. volatile orders)-1.06.66.40.24.9-12.49.7-3.75.2
manufacturing5.3-0.810.0-1.34.0-14.919.9-1.01.6
non-manufacturing (exc. volatile orders)-4.411.36.2-2.35.9-9.34.5-2.62.9
governments-14.757.7-21.3-17.828.5-5.010.5-9.2-6.1
from overseas14.53.631.010.41.3-4.419.9-8.2-7.7
through agencies0.32.64.86.711.1-5.87.21.3-6.3

Note

  1. Seasonally adjusted series. As all series are seasonally adjusted individually, a sum of seasonally adjusted individual/component series does not equal to seasonally adjusted totals.
  2. Volatile orders: Orders for ships and those from electric power companies.

References

Chart 1: Total Value of Machinery Orders

Chart 2: Private Sector (excluding volatile orders)

Table 1: Machinery Orders by Sectors

(billion Yen %)

2025
Jul-Sep
Oct-Dec2026
Jan-Mar
Apr-JunJul-Sep
(forecast)
2026
May
JunJulAug
Total9,543.6
(3.5)
[6.1]
10,514.8
(10.2)
[13.5]
11,593.0
(10.3)
[23.5]
12,900.0
(11.3)
[39.4]
12,881.0
(-0.1)
[36.7]
4,422.2
(9.5)
[40.4]
4,439.0
(0.4)
[43.7]
4,195.7
(-5.5)
[36.8]
4,041.9
(-3.7)
[26.1]
private sector3,370.6
(-1.3)
[12.9]
3,580.8
(6.2)
[11.2]
3,674.3
(2.6)
[11.6]
4,210.8
(14.6)
[22.4]
4,051.2
(-3.8)
[21.0]
1,706.2
(37.4)
[40.8]
1,262.6
(-26.0)
[12.7]
1,281.3
(1.5)
[10.3]
1,226.9
(-4.2)
[13.8]
(exc. volatile orders)2,741.4
(-1.0)
[6.6]
2,921.6
(6.6)
[8.1]
3,109.2
(6.4)
[12.6]
3,116.2
(0.2)
[10.8]
3,268.6
(4.9)
[19.9]
962.0
(-12.4)
[-1.9]
1,055.8
(9.7)
[16.9]
1,016.9
(-3.7)
[11.2]
1,069.8
(5.2)
[18.6]
manufacturing1,369.3
(5.3)
[14.0]
1,357.8
(-0.8)
[3.9]
1,493.7
(10.0)
[14.8]
1,474.8
(-1.3)
[12.5]
1,534.0
(4.0)
[12.6]
437.2
(-14.9)
[-4.7]
524.1
(19.9)
[27.4]
518.6
(-1.0)
[20.5]
527.0
(1.6)
[23.5]
non-manufacturing (exc. volatile orders)1,409.5
(-4.4)
[1.5]
1,568.1
(11.3)
[12.0]
1,666.0
(62)
[12.5]
1,627.2
(-2.3)
[9.6]
1,723.8
(5.9)
[25.6]
516.9
(-9.3)
[0.9]
540.2
(4.5)
[8.5]
525.9
(-2.6)
[5.7]
541.3
(2.9)
[10.8]
governments1,159.4
(-14.7)
[-22.7]
1,828.8
(57.7)
[-4.4]
1,439.2
(-21.3)
[-18.6]
1,183.4
(-17.8)
[-13.2]
1,521.2
(28.5)
[33.4]
374.7
(-5.0)
[-24.9]
414.2
(10.5)
[-7.3]
376.2
(-9.2)
[-25.8]
353.3
(-6.1)
[8.1]
from overseas4,624.3
(14.5)
[10.3]
4,789.4
(3.6)
[22.3]
6,275.3
(31.0)
[57.2]
6.928.8
(10.4)
[71.1]
7.016.5
(1.3)
[55.6]
2,135.5
(-4.4)
[62.2]
2,559.6
(19.9)
[83.8]
2,350.2
(-8.2)
[81.5]
2,168.7
(-7.7)
[36.9]
through agencies410.6
(0.3)
[9.1]
421.3
(2.6)
[13.1]
441.3
(4.8)
[18.7]
470.7
(6.7)
[13.7]
522.7
(11.1)
[24.7]
150.2
(-5.8)
[0.4]
161.0
(7.2)
[16.1]
163.1
(1.3)
[12.1]
152.8
(-6.3)
[17.4]

Notes

  1. Seasonally adjusted series. As all series are seasonally adjusted individually, a sum of seasonally adjusted individual/component series does not equal to seasonally adjusted totals.
  2. Figures in () represent the percentage change from the previous quarter (month). Figures in [] are the percentage change from the corresponding quarter (month) of the previous year in original series.
  3. Volatile orders: Orders for ships and those from electric power companies.

Table 2:

2025
Jul-Sep
Oct-Dec2026
Jan-Mar
Apr-Jun2026
May
JunJulAug
Manufacturing5.3-0.810.0-1.3-14.919.9-1.01.6
1. Foods and beverages-72-0.911.0-2.1-13.227.3-11.60.1
2. Textile mill products12.3-3.1-12.526.13.8-14.3-7.0-18.6
3. Pulp, paper and paper products5.09.4-7.9-2.514.35.465.2-33.2
4. Chemical and chemical products9.5-37.542.7-21.719.239.0-12.0-11.5
5. Petroleum and coal products-36.366.7-53.4-2.57.132.94.819.6
6. Ceramic, stone and clay products31.2-7.19.515.7-13.33.26.1-23.0
7. Iron and steel22.6-11.521.5-21.5-5.3-10.85.8-36.3
8. Non-ferrous metals-5.2-0.226.1-16.019.5225.3-82.2132.6
9. Fabricated metal products-6.9-5.716.448.313.8-46.113.2-10.7
10. General-purpose and production machinery7.1-4.111.0-0.8-10.318.9-1.49.3
11. Business-oriented machinery-11.52.48.219.9-14.33.2-7.2-5.7
12. Electrical machinery-6.310.3-3.020.2-12.02.246.1-5.9
13. Information and communication electronics22.3-8.611.915.1-23.629.74.713.0
14. Automobiles, parts and accessories3.8-0.813.6-0.57.46.91.513.1
15. Ship building18.8-25.765.73.9-80.594.988.9-41.0
16. Other transport equipment-4.55.936.4-11.467.14.7-41.443.7
17. Other manufacturing-1.59.9-4.2-4.6-10.2-0.6-1.36.1
Non-manufacturing-2.410.3-1.524.168.0-40.40.8-5.7
18. Agriculture, forestry and fishing10.412.20.5-23.2-24.233.011.0-4.0
19. Mining, quarrying of stone and gravel-8.4-6.93.0-24.120.723.76.725.0
20. Construction-3.18.34.09.31.6-8.55.8-17.2
21. Electricity supply1.0-1.50.291.7342.9-75.134.2-34.9
22. Transportation and postal activities7.00.1-15.85.5-23.38.93.3-13.9
23. Telecommunications-16.818.8-0.814.6-7.522.3-23.216.9
24. Wholesale and retail trade4.8-2.44.13.4-3.1-3.1-3.929.2
25. Finance and insurance-6.39.38.5-2.7-10.617.9-6.80.2
26. Real estate-20.94.714.139.7-69.3253.1-26.40.7
27. Information services-6.47.725.1-11.8-8.916.0-16.97.9
28. Goods leasing14.3-12.810.1-16.6-18.6-0.9-6.8136.0
29. Other non-manufacturing-2.541.5-2.8-5.234.9-26.620.1-28.0

Note

Percentage change from previous quarter (month) in seasonally adjusted series.

Existence and the Problem of Separability

In contracts and legal documents, there is a concept of “separability” which means that clause A is connected to clause B in a way that cannot be undone.

The great twentieth century French philosopher, Gabriel Marcel, has a profound non-separability analysis of existence itself. Marcel wrote:

…We cannot really separate:—

  1. Existence
  2. Consciousness of self as existing
  3. Consciousness of self as bound to a body, as incarnate.
Gabriel Marcel, Being and Having: An Existentialist Diary, Harper Torchbooks, 1965, page 10.

This leads to saying things that are very deep aspects of existential thinking governed by the points above. For example, Marcel wrote, “As I have said elsewhere, the moment I treat my body as an object of scientific knowledge, I banish myself to infinity.” Consider the end of the previous phrase. The very notion that someone, within themselves could go down a route to “banish themselves” in this way, shows you a door into very deep psychological problems. In other words, Marcel is telling you that some psychological problems could have a philosophical or existential root cause and are a type of blunder.

This is not to say that one should avoid scientific thought. Taking a drop of your blood and viewing it under a microscope is not a blunder. However, if you take this to the extreme of trying to analyze everything scientifically, to the exclusion of philosophy in daily life, this is Marcel’s warning.

Marcel’s context for this thinking is given here:

Notes for a Paper to the Philosophical Society

Undated, written in 1927 or 19281

When I affirm that something exists, I always mean that I consider this something as connected with my body, as able to be put in contact with it, however indirect this contact may be. But note must be taken that the priority I thus ascribe to my body depends on the fact that my body is given to me in a way that is not exclusively objective, i.e. on the fact that it is my body. This character, at once mysterious and intimate, of the bond between me and my body (I purposely avoid the word relation) does in fact colour all existential judgments.


What it comes to is this. We cannot really separate:—

  1. Existence
  2. Consciousness of self as existing
  3. Consciousness of self as bound to a body, as incarnate.

From this several important conclusions would seem to follow:

  1. In the first place, the existential point of view about reality cannot, it seems, be other than that of an incarnate personality. In so far as we can imagine a pure understanding, there is, for such an understanding, no possibility of considering things as existent or non-existent.
  2. On the one hand, the problem of the existence of the external world is now changed and perhaps even loses its meaning; I cannot in fact without contradiction think of my body as non-existent, since it is in connection with it (in so far as it is my body) that every existing thing is defined and placed. On the other hand, we ought to ask whether there are valid reasons for giving my body a privileged metaphysical status in comparison with other things.
  3. If this is so, it is permissible to ask whether the union of the soul and body is, in essence, really different from the union between the soul and other existing things. In other words, does not a certain experience of the self, as tied up with the universe, underlie all affirmation of existence?
  4. Inquire whether such an interpretation of the existential leads towards subjectivism.
  5. Shew how idealism tends inevitably to eliminate all existential considerations in view of the fundamental unintelligibility of existence. Idealism versus metaphysics. Values detached from existence: too real to exist.

Existential and personalist interests closely linked. The problem of the immortality of the soul is the pivot of metaphysic.

Every existent is thought of like an obstacle by which we take our bearings—like something we could collide with in certain circumstances—resistent, impenetrable. We think of this impenetrability, no doubt, but we think of it as not completely thinkable.2 Just as my body is thought of in so far as it is a body, but my thought collides with the fact that it is my body.

To say that something exists is not only to say that it belongs to the same system as my body (that it is bound to it by certain connections which reason can define), it is also to say that it is in some way united to me as my body is.

Incarnation—the central ‘given’ of metaphysic. Incarnation is the situation of a being who appears to himself to be, as it were, bound to a body. This ‘given’ is opaque to itself: opposition to the cogito. Of this body, I can neither say that it is I, nor that it is not I, nor that it is for me (object). The opposition of subject and object is found to be transcended from the start. Inversely, if I start from the opposition, treating it as fundamental, I shall find no trick of logical sleight of hand which lets me get back to the original experience, which will inevitably be either eluded or (which comes to the same thing) refused. We are not to object that this experience shews a contingent character: in point of fact, all metaphysical enquiry requires a starting-point of this kind. It can only start from a situation which is mirrored but cannot be understood.

Inquire if incarnation is a fact; it does not seem so to me, it is the ‘given’ starting from which a fact is possible (which is not true of the cogito).

A fundamental predicament which cannot be in a strict sense mastered or analysed. It is exactly this impossibility which is being stated when I declare, confusedly, that I am my body; i.e. I cannot quite treat myself as a term distinct from my body, a term which would be in a definable connection with it. As I have said else-where, the moment I treat my body as an object of scientific know-ledge, I banish myself to infinity.

This is the reason why I cannot think of my death, but only of the standstill of that machine (illam, not banc). It would perhaps be more accurate to say that I cannot anticipate my death, that is, I cannot ask myself what will become of me when the machine is no longer working.3

[1] This paper was never delivered.

[2] It is thought of, but it is never resolved. The opacity of the world is in a certain sense insoluble. The link between opacity and Meinbeit. My idea is opaque to me personally in so far as it is mine. We think of it as an adherence. (Note written Feb. 24th, 1929.)

[3] ‘To be involved.’ (idée d’un engagement) Try to shew in what sense this implies the impossibility (or absolute non-validity of my representing my death. In trying to think of my death I break the rules of the game. But it is radically illegitimate to convert this impossibility into a dogmatic negation. (Note written Feb. 24th, 1929.)

It is evident that this whole train of thought is at the root of le Gouvernail: the first notes on the theme of le Gouvernail were composed a few days after these. (Note written April 13th, 1934.)

Gabriel Marcel, Being and Having: An Existentialist Diary, pages 10-12

The reader should not be afraid of converting this level of discussion to everyday life and everyday slang. For example, when Marcel uses phrases like, “I banish myself to infinity” that should resonate with phrases like “flipping out.”

Take this example from Kierkegaard. There’s a book-seller in Copenhagen and he greets a customer who has just entered his shop. The book-seller turns to his wife and says, “It is I who am speaking, isn’t it?” Kierkegaard’s book-seller seems to have “banished himself” and cannot return.

China: Deep History

Winston Churchill says somewhere (if we paraphrase) that the further back you are able to look, the more secure your ability to analyze the present and the future. Without these ‘historical smarts’, your sense of direction is very feeble. Let us use the novel, Lost Illusions, by Honoré de Balzac as a back door into historical smarts.

This novel was originally published in three parts between 1837 and 1843 and is set mostly in the 1820s, primarily in provincial France. It is unique because it starts with technology and commerce.

At the time when this story begins, the Stanhope press and inking-rollers were not yet in use in small provincial printing-offices. Angoulême, although its paper-making industry kept it in contact with Parisian printing, was still using those wooden presses from which the now obsolete metaphor ‘making the presses groan’ originated. Printing there was so much behind the times that the pressmen still used leather balls spread with ink to dab on the characters. The bed of the press holding the letter-filled ‘forme’ to which the paper is applied was still made of stone and so justified its name ‘marble’. The ravenous machines of our times have so completely superseded this mechanism — to which, despite its imperfections, we owe the fine books produced by the Elzevirs, the Plantins, the Aldi and the Didots — that it is necessary to mention this antiquated equipment which Jérôme-Nicolas Séchard held in superstitious affection; it has its part to play in this great and trivial story.

Not only do we get this conceptual framework about printing technology, but later on in the novel, Balzac gives us a further insight into paper-making and textiles, including a long discussion of China.

In England, where four-fifths of the population use cotton to the exclusion of linen, they make nothing but cotton paper. The cotton paper is very soft and easily creased to begin with, and it has a further defect: it is so soluble that if you seep a book made of cotton paper in water for fifteen minutes, it turns to a pulp, while an old book left in water for a couple of hours is not spoilt. You could dry the old book, and the pages, though yellow and faded, would still be legible, the work would not be destroyed.

“There is a time coming when legislation will equalize our fortunes, and we shall all be poor together; we shall want our linen and our books to be cheap, just as people are beginning to prefer small pictures because they have not wall space enough for large ones. Well, the shirts and the books will not last, that is all; it is the same on all sides, solidity is drying out. So this problem is one of the first importance for literature, science, and politics.

“One day, in my office, there was a hot discussion going on about the material that the Chinese use for making paper. Their paper is far better than ours, because the raw material is better; and a good deal was said about this thin, light Chinese paper, for if it is light and thin, the texture is close, there are no transparent spots in it. In Paris there are learned men among the printers’ readers; Fourier and Pierre Leroux are Lachevardiere’s readers at this moment; and the Comte de Saint-Simon, who happened to be correcting proofs for us, came in in the middle of the discussion. He told us at once that, according to Kempfer and du Halde, the Broussonetia furnishes the substance of the Chinese paper; it is a vegetable substance (like linen or cotton for that matter). Another reader maintained that Chinese paper was principally made of an animal substance, to wit, the silk that is abundant there. They made a bet about it in my presence. The Messieurs Didot are printers to the Institute, so naturally they referred the question to that learned body. M. Marcel, who used to be superintendent of the Royal Printing Establishment, was umpire, and he sent the two readers to M. l’Abbe Grozier, Librarian at the Arsenal. By the Abbe’s decision they both lost their wages. The paper was not made of silk nor yet from the Broussonetia; the pulp proved to be the triturated fibre of some kind of bamboo. The Abbe Grozier had a Chinese book, an iconographical and technological work, with a great many pictures in it, illustrating all the different processes of paper-making, and he showed us a picture of the workshop with the bamboo stalks lying in a heap in the corner; it was extremely well drawn.

“Lucien told me that your father, with the intuition of a man of talent, had a glimmering of a notion of some way of replacing linen rags with an exceedingly common vegetable product, not previously manufactured, but taken direct from the soil, as the Chinese use vegetable fibre at first hand. I have classified the guesses made by those who came before me, and have begun to study the question. The bamboo is a kind of reed; naturally I began to think of the reeds that grow here in France.

“Labor is very cheap in China, where a workman earns three halfpence a day, and this cheapness of labor enables the Chinese to manipulate each sheet of paper separately. They take it out of the mould, and press it between heated tablets of white porcelain, that is the secret of the surface and consistence, the lightness and satin smoothness of the best paper in the world. Well, here in Europe the work must be done by machinery; machinery must take the place of cheap Chinese labor. If we could but succeed in making a cheap paper of as good a quality, the weight and thickness of printed books would be reduced by more than one-half. A set of Voltaire, printed on our woven paper and bound, weighs about two hundred and fifty pounds; it would only weigh fifty if we used Chinese paper. That surely would be a triumph…

In 2025, we are to some extent, back to China, going from the proto-industrial world to our industrial and even digital world.

To educate oneself on all of this, you should look at the supreme scholarly achievement of the 20th century, namely Professor Joseph Needham’s masterpiece, Science and Civilisation in China.

Education and the Long-Term: Automation As Example

The American Revolution: Pages From a Negro Worker’s Notebook

Chapter 2: The Challenge of Automation

“Since 1955 and the advent of automation, overtime has been detrimental to the workers. Again and again workers have been faced with the decision to work overtime or not to work overtime, and the decision has usually been: ‘To hell with those out of work. Let’s get the dollar while the dollar is gettable.’ The amazing thing is that this has nothing to do with the backwardness of these workers. Not only can they run production and think for themselves, but they sense and feel the changes in conditions way in advance of those who are supposed to be responsible for their welfare. But with all these abilities there is one big organic weakness. Over and over again workers in various shops and industries, faced with a critical issue, only divide and become disunited, even though they are well aware that they are being unprincipled and weakening their own cause as workers. Since the advent of automation there has not been any serious sentiment for striking, particularly if the strike was going to come at the expense of material things that the workers already had in their possession, like cars, refrigerators, TV sets, etc. They were not ready to make any serious sacrifices of these; they would rather sacrifice the issue. Between the personal things and the issue, they have chosen the personal. Most American workers have geared themselves to a standard of living that is based on a five-day week plus—either in the form of overtime or another job, part or full time. And any time this standard of living is threatened, it is a personal crisis, which means that more and more decisions are being personalized and individualized rather than collectivized and socialized.”

(The American Revolution: Pages From a Negro Worker’s Notebook, James Boggs, Monthly Review Press, 1963, page 33)

As far back as 1963, with President John Kennedy in office, James Boggs (a Detroit autoworker) was already quite aware of automation and its challenges.

A “meta-intelligent” education means we learn from any sources available including “angry pamphlets” without worrying about the ideological blinders or fireworks because our desire is not to engage in polemics but to “extract signals” from a noisy world.

Chapter 2 of James Boggs’s pamphlet is called “The Challenge of Automation” and begins: “Since 1955 and the advent of automation, overtime has been detrimental to the workers…”

This immediately tells you that automation is a very long-run historical trend and should be seen in a larger sweep with history as your searchlight.

Indeed the famous German classic The Weavers by Gerhart Hauptmann is about machines as a threat to employment:

The Weavers (German: Die Weber, Silesian German: De Waber) is a play written by the German playwright Gerhart Hauptmann in 1892. The play sympathetically portrays a group of Silesian weavers who staged an uprising during the 1840s due to their concerns about the Industrial Revolution and replacement by machines and automation.

In 1927, it was adapted into a German silent film The Weavers, directed by Frederic Zelnik and starring Paul Wegener.

A Broadway version of The Weavers was staged in 1915–1916.

To dismiss all such movements and revolts as Luddite-like is not useful since it sweeps legitimate problems under the rug.

This includes Ernst Toller’s classic The Machine Wreckers (German: Die Maschinenstürmer). Two of his early plays were produced in this period: The Machine Wreckers (1922), whose opening night in 1937 he attended, and No More Peace, produced in 1937 by the Federal Theatre Project and presented in New York City in 1938.

All of these critiques of machines and automation are part of a long-term historical overview of machines and jobs and in our time, robotics and AI, etc which should be analyzed as a trajectory and arc where “machine wreckers” à la Hauptmann or Toller are understood empathetically and realistically and not dismissed as vandals.