CCG President outlines opportunities for China and Europe to deepen cooperation in trade, investment, climate action, and global governance.
[from the Center for China & Globalization, 7 November 2026]
Henry Huiyao Wang [王辉耀], Founder and President of the Center for China & Globalization (CCG), has published an article titled “A New Compact for China and Europe” in the Autumn 2026 issue (No. 36) of Horizons, a journal published by the Center for International Relations and Sustainable Development (CIRSD).
Wikimedia Commons/iMoD Official
China and Europe possess almost everything needed for a consequential partnership. Their economies are deeply intertwined. They have no fundamental geopolitical disputes. And they share important interests in climate action, global development, and a functioning multilateral system. Yet the bilateral relationship is weaker than it could be. At its core is a commercial dispute over trade, which is turning what should be a fruitful relationship built on shared interests into one increasingly characterized by the language of industrial vulnerability and tariffs.
Trade has thus become a wedge issue that risks souring a mutually beneficial interdependence. And it comes at a poor moment. The international order is moving away from the unipolar era that followed the Cold War and into a new multipolar era, one in which multilateralism, and the defense of our shared global institutions, matter more than ever. Wars, tariff conflicts, technological fragmentation, and pressure on multilateral institutions are producing a world that is more multipolar but no more governable. Now more than ever, we need cooperation on global governance across a wide range of transnational issues, from climate change to artificial intelligence.
Europe in a Multipolar World
For much of the postwar period, the transatlantic alliance provided the central structure of European security. But the era of American hegemony, when diplomatic sleepwalking was permissible, is over. It seems clear that European policymakers have long since realized that formal alliances and shared values are no longer a substitute for independent judgment on geopolitical and economic questions, at a time when American policy is nakedly unilateral, transactional, and protectionist—and thus hostile to European interests.
Unwilling to be a passive participant in American power politics, or to be caught between the United States and China, Europe has already begun charting a course toward strategic autonomy, even if its exact shape is not yet settled. China, for its part, understands that asking Europe to “choose China” over the United States is not a palatable proposition—least of all now, when self-determination and strategic autonomy have become a clear European focus.
Instead, from China’s perspective, a break from “the West versus the rest” is victory enough, because it enables a shift away from alignment based on ideology toward a world of tactical cooperation based on the merits of each issue.
Canadian Prime Minister Mark Carney offered a useful description of this at Davos this year, calling for “variable geometry”: different coalitions for different issues, built around shared interests rather than around values that are not firmly or equally upheld. In this framing, Europe can cooperate as closely as it wishes with the United States on defense, while still finding common cause with China on climate and trade reform, or with India on development. Such flexibility is increasingly the default in our plural world.
A cohesive Europe able to act independently is preferable to a divided continent whose China policy is increasingly shaped elsewhere. But that also means that policymakers in China must address European fears if they are to benefit from engagement and cooperation on shared interests.
The Changing Bargain
The core anxiety facing Europe, and the one undermining a merits-based relationship, is that the old, unspoken economic bargain—European technology and premium manufacturing in exchange for Chinese consumer goods and lower-cost production—is giving way to a more competitive relationship.
China now possesses broad industrial ecosystems, world-class infrastructure, skilled engineering talent, and the capacity for fast commercialization at scale. It no longer competes on wages alone. In electric vehicles, batteries, solar energy, machinery, telecommunications equipment, and, increasingly, advanced digital applications, Chinese firms can combine cost, speed, and technological capability.
But let us not get carried away with catastrophizing. The shared economic foundation between China and the EU remains immense. In 2025, two-way trade in goods and services exceeded €880 billion. Europe imported more than €570 billion in goods from China and exported about €200 billion, producing a large bilateral goods deficit. Yet this figure should be interpreted carefully. The European Union still recorded an overall goods surplus of approximately €128 billion in 2025, as well as a substantial current-account surplus. Nor are all imports finished products: Eurostat data shows that 57 percent of all extra-EU goods imports in 2025 were intermediate products, meaning that much of what Europe imports feeds into value-added production chains from which Europe itself benefits. Europe’s difficulty is that, while its industry remains broadly profitable, certain critical sectors are already under pressure, and the trend seems unlikely to reverse suddenly in favor of European manufacturing.
Europe is not facing this crisis in a vacuum, either. It is compounded by high energy costs, aging populations, fragmented capital markets, and chronic underinvestment. The result is a genuine fear of deindustrialization, with the attendant loss of skilled employment, supplier networks, technological capacity, and social cohesion. This worry is especially potent in the major European economies with large export-oriented manufacturing sectors, such as Germany, France, Italy, and Spain, and it makes the debate over “overcapacity” deeply politically charged.
While the imbalance is a product of industrial excellence, it can also be attributed to weak domestic demand in China. Household consumption there remains around 40 percent of GDP, while families save heavily out of concern over housing, education, health care, and retirement. The 2025 consumption action plan addressed wages, pensions, health care, childcare, paid leave, and benefits for migrant and flexible workers, and China’s first five-year plan devoted specifically to consumption subsequently set a goal of approximately 60 trillion yuan in retail sales by 2030. But it is far too early to call the effort complete. Although per capita disposable income rose by 5 percent and consumption expenditure by 4.4 percent in 2025, the first half of 2026 was weaker, and overall consumption still lags behind where it should be. Stronger pensions, health care, unemployment insurance, childcare, and portable benefits for migrant workers will help reduce precautionary saving, and greater access for foreign goods and services would ensure that stronger Chinese demand creates opportunities for European producers. That transformation, however, is not yet complete.
Europe, for its part, should recognize that competitive success is not in itself an unfair subsidy. The International Energy Agency estimates that producing a battery-electric vehicle costs more than 30 percent less in China than in advanced economies, with only about one-third of the gap attributable to the battery; a similar cost gap exists for conventional vehicles. China’s earlier industrial policies undoubtedly helped establish this ecosystem, but important forms of direct support, including national EV purchase subsidies, have already been phased out.
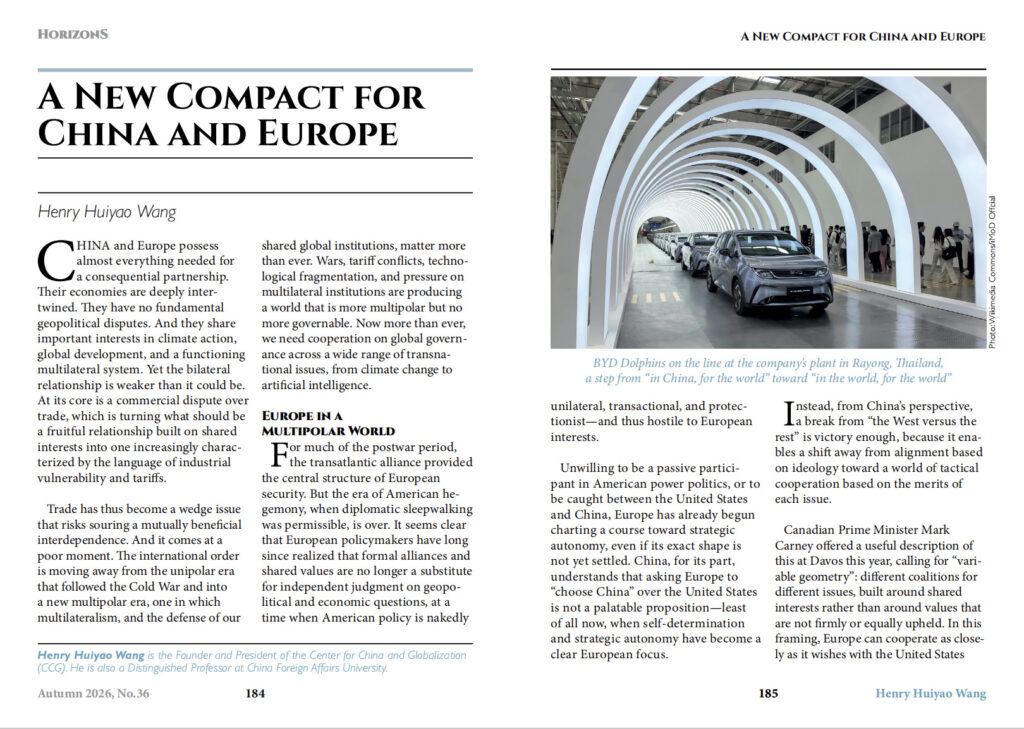
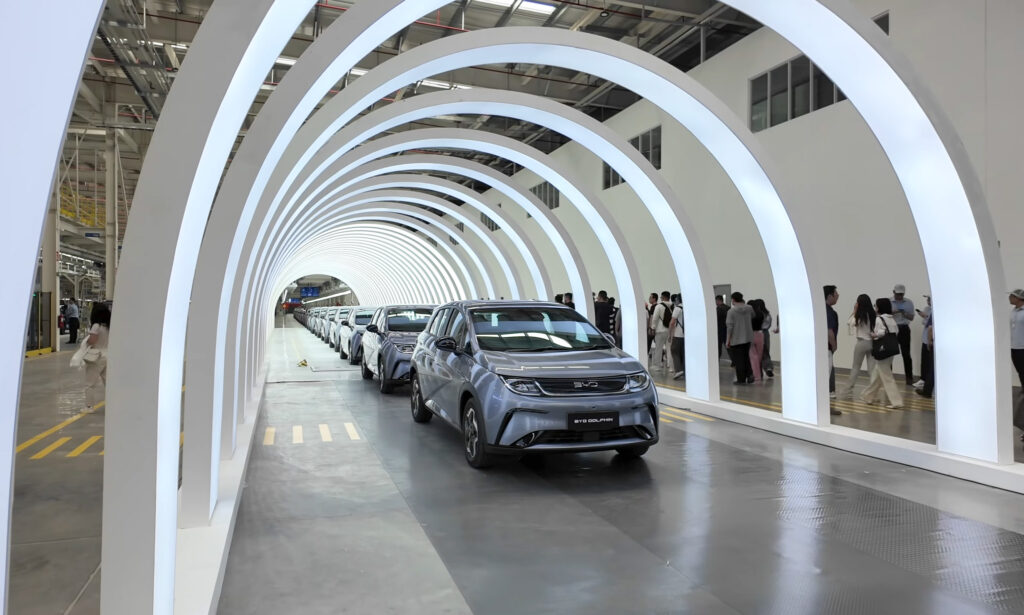
Rhodium Group estimates that BYD enjoys a cost advantage of approximately $4,700 per vehicle over Tesla’s operations in China, of which grants account for only about $292, while vertical integration and lower research, administrative, and supplier costs explain at least three-quarters of the difference. BYD produces roughly 70 percent of its components in-house, including its batteries. Europe should investigate market-distorting support and is right to insist on transparency, but it should not define the ecosystem, technology, and efficiencies China has built as unfair.
Nor is China’s automobile sector insulated from competition. The number of Chinese electric-vehicle makers was reported at 487 in 2018; by 2025, consolidation had reduced the market to approximately 129 brands produced by about 50 manufacturers, and only 10 to 15 are expected to be profitable by 2030. China exported approximately 5.86 million of the more than 31 million vehicles it sold in 2024, meaning that the large majority were still absorbed at home. By comparison, Volkswagen delivered 9.03 million vehicles worldwide but only 1.12 million in Germany, while Toyota and Lexus sold 10.16 million worldwide and 1.44 million in Japan. Airbus, likewise, sells approximately 68 percent of its aircraft outside Europe. Producing for global markets is accepted as normal when established European or Japanese companies do it; it should not automatically become illegitimate when Chinese firms do the same.
China’s textile industry offers a further precedent. Even as wages rose and some production moved to Vietnam, Bangladesh, and elsewhere, China retained 37 percent of global textile exports and 34 percent of clothing exports in 2017, because supplier clusters, infrastructure, skills, and continual upgrading proved more durable than low labor costs alone.
Beyond economic competition, clearer rules are urgently needed on the securitization of critical industries. The dispute over Nexperia—the Chinese-owned semiconductor company placed under Dutch government control in 2025—rattled supply chains and deepened concern in China about investing abroad. Either the company should not have been sold in the first place, or a clearer regulatory environment might have avoided a quasi-nationalization that rapidly internationalized a corporate dispute, and that still hangs over the mutual investment relationship today.
Likewise, proposals for a European instrument modeled on the United States’ Section 301 powers may offer political reassurance, but Section 301 is a blunt unilateral instrument designed to authorize retaliation. Europe would be better served by an explicitly transitional mechanism. Where an import surge threatens to destabilize domestic markets, temporary safeguards can provide time for adjustment, but they should be evidence-based, reviewable, and subject to firm sunset clauses. Their purpose should be to facilitate adaptation and negotiation, not to turn emergency protection into a permanent wall.
An Industrial Compact for Shared Competitiveness
When I visited Jean Monnet’s house outside Paris this summer, I was reminded of the method that helped build modern Europe: begin with concrete achievements that create the basis for solidarity. That method matters especially now, when trade has become a wedge issue and trust and trade cannot be separated.
We must therefore build a new industrial compact: one that aligns Chinese industrial capacity with Europe’s need for investment, innovation, and employment, and that enables China and Europe to stand together in support of a world of free, fair, and open trade.
First, China should follow through on its ongoing shift from an export– and investment-heavy model toward consumption-led growth. Alongside the social measures described above, this requires reducing the barriers faced by private and foreign businesses, improving market access in services and public procurement, and applying regulation more transparently. European companies should be able to compete in China with confidence that they will receive equal treatment and can protect their intellectual property.
Second, Europe needs to draw a sharper distinction between trade in products that present a genuine security risk and investment that strengthens European productive capacity. Concerns about supply-chain resilience and security in defined strategic sectors are unavoidable, given increasing regionalization. But a presumption against Chinese investment would deprive Europe of capital, technology, competition, and jobs precisely when it needs them most. Instead, Europe could openly welcome investment that meets its requirements on governance, data protection, labor standards, and environmental performance, while increasing the local economic contribution such production provides.
This openness should be anchored by a renewed Comprehensive Agreement on Investment. The agreement reached in principle in 2020 was never implemented and the relationship has changed too much for it simply to be revived unchanged. China and Europe should instead negotiate a new CAI covering market access, national treatment, subsidy transparency, technology transfer, public procurement, and enforceable dispute resolution. It should give European companies more predictable access to China, while establishing clear and consistent conditions for Chinese market access and investment in Europe, with an eye to creating employment and supplier networks there.
China has already demonstrated the value it places on market access by extending tariff-free treatment to goods from 53 African countries, and it could move explicitly to align its standards more closely with Europe’s. Europe, for its part, should reconsider its technology and investment restrictions—especially those implemented specifically to protect U.S. interests, such as the restrictions preventing China from purchasing advanced semiconductor equipment from ASML. Working examples of Chinese investment in Europe already exist. Chinese companies are investing in battery and vehicle production in Hungary, Slovakia, Spain, and Serbia, while European manufacturers—including Volkswagen, BMW, and Mercedes-Benz—continue to deepen their research, production, and partnership networks in China. These investments should not be viewed as isolated commercial transactions. They can become the architecture of a more balanced relationship.
Third, localization must mean more than final assembly. Joint ventures and investment agreements can encourage local supplier development, worker training, research partnerships, and the sharing of production know-how, while respecting intellectual-property rights. Chinese industry was once buoyed by European know-how through joint ventures; in return, European industry can now benefit from Chinese advances. The goal should be a competitive ecosystem in which both Chinese and European firms have a stake.
Fourth, any trade measures should be targeted and temporary. If an import surge threatens serious injury, safeguards can buy time for adaptation. But they should have clear evidentiary thresholds, sunset clauses, and review procedures. Protection without a productivity strategy merely postpones decline and risks marginalization, rather than allowing a dynamic industrial sector to emerge. At the same time, Europe can and should complete its own agenda: lowering energy costs, deepening the single market, mobilizing investment, scaling up innovative companies, and improving infrastructure.
Here, China can become Europe’s “fitness partner.” The phrase may sound counterintuitive at a moment of industrial anxiety, but the underlying idea is important. Healthy competition from China can push European companies and governments to confront long-delayed reforms, reduce costs, and innovate faster. Shelter from competitive pressure does not create health; competition, by contrast, can serve as a yardstick for rebuilding strength. China, meanwhile, gains more from a prosperous and capable Europe than from a weakened market increasingly hostile to Chinese commerce.
Finally, the compact should look beyond the bilateral market. Chinese and European joint ventures could look abroad, toward the product and development needs of the Global South. Joint production for Global South markets could be a starting point, moving in time toward joint financing of development and infrastructure to accelerate green industrialization in Africa, Asia, Latin America, and the Middle East.
This would represent the next stage of globalization: not simply Chinese companies “in China, for the world,” but “in the world, for the world.” It would spread productive capacity more widely, answer concerns about concentrated supply chains, and make development a shared undertaking rather than an arena for geopolitical competition.
From Commercial Trust to Strategic Cooperation
An industrial compact cannot by itself remove all political differences. But it would serve as a springboard, and a trust-building exercise, for deeper commitments and further work on shared interests.
Climate cooperation is the most obvious bridge. China’s manufacturing scale has lowered the global cost of solar panels, batteries, and electric vehicles, in a very real way underwriting the transition away from fossil fuels. At the same time, Europe is suffering under the weight of an energy crisis born of Russia’s invasion of Ukraine and, more recently, of upheavals in the Middle East around the Strait of Hormuz and the Bab al-Mandeb. A natural alignment would be for China and Europe to build a green partnership that helps wean the world off volatile fossil fuels and address the climate crisis. The exact shape of such measures is not yet defined, but using joint ventures, cooperation, and technology exchange to tap Chinese expertise and cost advantages could benefit both sides while buoying the global green transition. A tariff spiral in clean technology, by contrast, would make the energy transition slower and more expensive for everyone.
More broadly, China and Europe share an interest in conflict resolution. China has always been clear that sovereignty and territorial integrity apply universally, that nuclear escalation is unacceptable, and that a negotiated settlement must provide credible security for all parties. But it can do more to ease the concerns of a Europe that feels threatened by a Russia now in its fifth year of fighting in Ukraine. Working together, Europe and China could help provide an off-ramp, each using its leverage to bring the negotiating positions closer together. A truly durable settlement, acceptable to both sides, may eventually require security guarantees involving both European and non-European countries, and China could contribute through reconstruction, nuclear safety, and peacekeeping. The Middle East is another region where common interests are greater than current policy coordination suggests. Continued conflict and volatility around the straits have not only given fresh impetus to the transition away from fossil fuels but also created a new area of shared interest. Together, Europe and China could support a peace architecture with wider international participation.
Artificial intelligence governance is another opportunity. China and Europe approach data, platforms, and regulation differently, but both reject a future in which a handful of private companies set global rules without public accountability. They can work together on safety testing, scientific exchange, interoperable standards, and the application of AI to health, climate, and development. Agreement will be difficult, but building a shared environment for rule-making would help hedge against fragmentation in this rapidly developing field.
Finally, China and the EU have both long advocated restoring the World Trade Organization. A revitalized WTO already contains tools to address subsidies and demonstrable injury. Boeing and Airbus were both found, in WTO disputes, to have benefited from improper support, and those cases were handled through multilateral proceedings rather than through an open-ended campaign against either side’s wider industrial success. The WTO’s dispute-settlement system must now be restored, its rules on subsidies and state enterprises updated, and its development functions strengthened. The United States weakened that system by blocking appointments to the Appellate Body after adverse rulings; but China and Europe are both major beneficiaries of an open trading system, and both can press for reform.
None of this will be sustainable without renewed contact between societies. Direct flights, student exchanges, tourism, university partnerships, city-to-city links, and think-tank dialogue all have their roles to play, for they are the infrastructure of mutual understanding.
China–Europe relations will not always be perfectly aligned, and they will likely continue to contain elements of cooperation, competition, and disagreement. But together, we can put to rest the prospect of weaponized interdependence and move instead toward win-win interdependence.
Europe does not need to become less European in order to cooperate with China, nor does China need to adopt European political mores for cooperation to succeed. Both are now free to cooperate selectively and on the merits of each issue. And a world in which China and Europe cannot find areas of deep mutual interest—despite their deep economic ties and their shared stake in multilateralism—is a world that is measurably poorer for it.