The twentieth centuryphilosopher, Ludwig Wittgenstein, tells us that his purpose is “to show the fly the way out of the fly-bottle.” Where the fly is, of course, ourselves. He then tells us, that perhaps the main reason is that one is unable to free oneself from bewitchment of the mind by “language games.”
In the song “Hotel California” by the Eagles, there’s the line, “‘We are all just prisoners here / Of our own device.’” In this context, “device” could be interpreted as a bad decision.
My Body and Myself
The Americanphilosophy professor, Samuel Todes, in his book Body and World, analyzes the human body, not as a meat-machine, but more like the silent partner of a person navigating their life. You can get a sense of this from Gabriel Marcel, when he writes:
Is my body my body, for instance, in the same sense in which I would say that my dog belongs to me? The question, let us first of all notice, of how the dog originally came into my hands is quite irrelevant here. Perhaps I found it wandering wretchedly about the streets, perhaps I bought it in a shop; I can say it is mine if nobody else puts in a claim for it—though this is still quite a negative condition of ownership. For the dog to be really, not merely nominally, mine there must exist between us a more positive set of relations. He must live, either with me, or as I, and I alone, have decided he shall live—lodged, perhaps, with a servant or a farmer; whether or not I look after him personally, I must assume the responsibility for his being looked after. And this implies something reciprocal in our relations. It is only it the dog recognizes me, obeys me, expresses by his behaviour towards me some feeling which I can interpret as affection or, at the very least, as wholesome fear, that he is really mine; I would become a laughingstock if I persisted in calling an animal that completely ignored me, that took no notice of me at all, my dog. And the mockery to which I would be exposed in such an instance is very significant. It is linked to a very positive idea of how things must be between my dog and me, before I can really say, ‘This dog is mine’.
We should recall, at this point, what we said in an earlier lecture about the body; the latter is not merely an instrument, it presents us with a kind of reality which is quite different from the reality of any sort of apparatus, in so far as it, my body, is also my way of being in the world.
When I try to make clear to myself the nature of my bond with my body, it appears to me chiefly as something of which I have the use (as one has the use of a piano, a saw, or a razor); but all these uses are extensions of the initial use, which is simply the use of the body. I have real priority to my body when it is a question of active use, but none whatever when it is a question of knowledge. The use is only possible on the basis of a certain felt community. But the community is indivisible; I cannot validly say ‘I and my body.’ The difficulty arises from the fact that I think of my relation with my body on the analogy of my relation with my instruments—whereas in fact the latter presupposes the former.
The connections between the trio of “me, myself and I” and the body is very elusive (as you may sense from your own introspection). This is another “argument without end.”
But, of course, it needed more than economic hardship, social discontent, and the frustration of political and social ambitions to make a revolution. To give cohesion to the discontents and aspirations of widely varying social classes there had to be some unifying body of ideas, a common vocabulary, of hope and protest, something, in short, like a common “revolutionarypsychology”. In the revolutions of our day, this ideological preparation has been the concern of political parties; but there were no such parties in eighteenth-centuryFrance.
“Labor marketindicators pointed to no growth in employment and a largely stable workweek,” said Jesus Cañas, Dallas Fed senior business economist. “Price pressures remained unchanged while wage growth eased slightly. Perceptions of broader business conditions continued to worsen in October, as pessimism notably increased.”
The revenueindex fell eight points to 0.7, with the near-zero reading suggesting little change in activity from September.
The employmentindex fell from 2.7 to 0.1, its lowest level in seven months.
The input pricesindex was flat at 37.3 and the selling pricesindex remained steady at 9.5.
The wages and benefitsindex fell two points to 17.0, approaching its average reading of 15.8.
The general business activity index dropped from -8.6 to -18.2, its lowest level since December of last year, while the company outlook index fell to -12.8, its lowest level in 16 months.
The sales index fell from -4.4 to -18.1, marking its sixth consecutive month in negative territory.
The employmentindex fell 13 points to -12.4 while the hours worked index fell from 0.6 to -12.1.
The general business activity index dropped from -10.2 to -23.0.
The Dallas Fed conducts the survey monthly to obtain a timely assessment of activity in the state’s service sector, which represents almost 70 percent of the state’s economy and employs about 9.5 million workers.
For this month’s survey, Texas business executives were asked supplemental questions on credit conditions. Results for these questions from the TexasManufacturing Outlook Survey, TexasService Sector Outlook Survey and TexasRetail Outlook Survey have been released together.
In this Economic Letter, we assess whether recent higher inflation is leading businesses and households in Mexico to expect inflation to remain high over the long run. Specifically, we focus on what rising market-based measures of inflation compensation may imply about bondinvestors’ outlook for inflation. The rise in inflation compensation since spring 2021 could reflect three factors: an increase in investors’ inflation expectations, an uptick in the premium investors demand for assuming inflation risk, or changes in other risk and liquidity premiums. We explore the relative importance of each of these factors using a novel dynamic term structure model of nominal and inflation-adjusted yields described in Beauregard et al. (2021, henceforth BCFZ). Overall, our results for five-year inflation expectations five years from now suggest Mexicanbondinvestors’ long-term inflation expectations have been little affected by the recent rise in inflation. Instead, the rise in inflation compensation reflects a notable uptick in the inflation risk premium to the high end of its historical range. This suggests that, despite inflation expectations being little changed on average, some investors are particularly concerned about the risk that inflation will remain above expected levels.
The recent rise in Mexican inflation
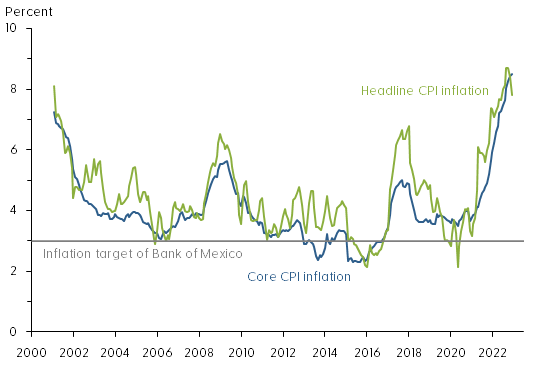
Figure 1 shows the year-over-year change in the Mexicanconsumer price index (CPI) measured both by the headline CPI (green line) and the more stable core CPI (blue line) that strips out volatile food and energy prices. Also shown with a horizontal gray line is the 3% inflation target of the nation’s central bank, the Bank of Mexico.
Figure 1: Mexican consumer price index inflation
Source: Instituto Nacional de Estadística y Geografía.
We note that MexicanCPIinflation has averaged somewhat above the Bank of Mexico’s target since its adoption in 2002. More importantly, CPIinflation in Mexico appears to have become more volatile and somewhat higher over the past five years. Although previous research by De Pooter et al. (2014) found inflation expectations in Mexico to be well anchored, the significant global economic dislocations caused by the coronavirus pandemic and related inflationary pressures could impact inflation expectations of businesses and households.
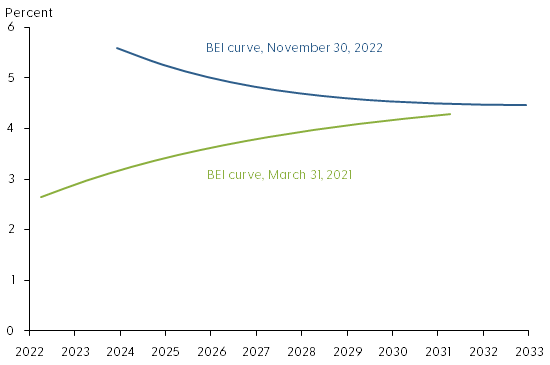
The difference between nominal and real yields for bonds of the same maturity is known as breakeven inflation (BEI). This represents a market-based measure of inflation compensation used to assess financial market participants’ inflation expectations. Figure 2 shows BEI rates at different maturities, meaning annual average rates of inflation compensation between now and maturity, from 1 to 10 years at the end of March 2021 (green line) and at the end of November 2022 (blue line). The slightly upward-sloping BEI curve of close to 3% in 2021 contrasts with the higher downward-sloping BEI curve in 2022.
Figure 2: BEI curves for 1-year to 10-year Mexican bond maturities
Source: Authors’ calculations using bond prices from Bloomberg.
The increase for shorter maturities, the left end of the 2022 BEI curve, is closely tied to the current high level of inflation and suggests inflation may remain elevated for some time. In contrast, the increase at longer maturities, the right end of the 2022 BEI curve, suggests that investors’ longer-term inflation expectations may be drifting above the Bank of Mexico’s inflation target. To better understand the shape and sources of variation of the BEI curve we use a yield curve model.
A yield curve model of nominal and real yields
Market-based measures of inflation compensation such as BEI rates contain three components. First, they include the average CPIinflation rate expected by bondinvestors, which is the focus here. Second is an inflation risk premium to compensate investors for the uncertainty of future inflation. This premium is embedded in nominal yields that provide no inflation protection. Third is the difference in relative market liquidity between standard fixed-coupon and inflation-indexed bonds. As discussed in BCFZ, both of these types of Mexicanbonds are less liquid than U.S. Treasuries, and their prices therefore contain a discount to compensate investors for their liquidity risk. Neither the inflation risk premium nor the liquidity premiums are directly observable and must therefore be estimated.
To adjust for these challenges, we first use the nominal and real yields model developed in BCFZ to identify liquidity premiums in standard fixed-coupon and inflation-indexed bond prices as a function of the time since issuance and the remaining time to maturity. The time since issuance serves as a proxy for declining liquidity as, over time, a larger fraction of bonds gets locked into buy-and-hold strategies. We refer to the observed BEI net of estimated liquidity premiums as the adjusted BEI. In a second step, we then separate adjusted BEI into components representing investors’ inflation expectations using a formula based on the absence of bond market arbitrage opportunities and the residual inflation risk premium.
Results
To assess whether investors’ inflation outlook has fundamentally changed, we follow De Pooter et al. (2014) and examine the five-year forward BEI rate that starts five years ahead, denoted 5yr5yr BEI. This is a horizon sufficiently long into the future that most transitory shocks to the economy can be expected to have vanished. Hence, the embedded inflation expectations are presumably less affected by current high inflation and pandemic-related transitory conditions and can therefore speak to the question about the anchoring of inflation expectations in Mexico.
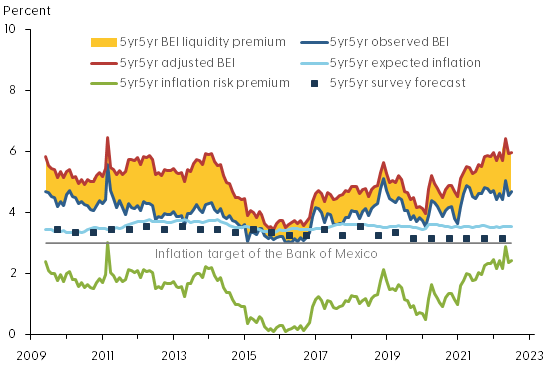
Figure 3 shows the breakdown of 5yr5yr BEI into its various components according to our model. The dark blue line is the observed BEI, and the red line is the estimated adjusted BEI without liquidity risk premiums or other residual disturbances. The difference between these two measures of BEI—the yellow shaded area—represents the model’s estimate of the net liquidity premium or distortion of the observed BEI series due to risk premiums in both nominal and inflation-indexed bond prices. The adjusted BEI is entirely above the observed BEI, suggesting the liquidity risk distortions are systematically larger in the inflation-indexed bond prices, consistent with similar evidence from the U.S. Treasury market (Andreasen and Christensen 2016). Note that the net BEI liquidity premium widened around the financial turmoil in spring 2020 at the start of the pandemic and remains elevated.
Figure 3: Components of 5yr5yr breakeven inflation for Mexico
Source: Survey forecasts from Consensus Economics and authors’ calculations using bond prices from Bloomberg.
The model also allows us to break down the adjusted BEI into an expected inflation component (light blue line) and the residual inflation risk premium (green line). Also shown is the Bank of Mexico’s 3% inflation target (gray horizontal line). For comparison, the figure also shows the 5yr5yr expected CPIinflation in Mexico reported semiannually in the Consensus Forecasts surveys (dark blue squares). We note that both observed and adjusted BEI have trended higher since the start of the pandemic in early 2020. Importantly, the breakdown indicates that long-term expected inflation in Mexico has remained stable, slightly above the 3% inflation target. As a result, the increase in BEI can be attributed to the inflation risk premium, which is at the high end of its historical range towards the end of our sample. Given the elevated levels of current inflation, this suggests some investors are concerned that inflation could remain elevated for longer than currently anticipated.
This raises the question of whether long-term inflation expectations in Mexico are likely to remain anchored near their current level going forward. To assess this risk, we simulate 10,000-factor paths over a three-year horizon using the estimated factors and factor dynamics as of November 2022—that is, the simulations are conditioned on the shapes of the nominal and real yield curves and investors’ embedded forward-looking expectations as of November 2022. These simulated factor paths are then converted into forecasts of 5yr5yr expected inflation. Figure 4 shows the median projection (solid green line) and the 5th and 95th percentile values (dashed green lines) for the simulated 5yr5yr expected inflation over a three-year horizon.
Figure 4: Three-year projections of 5yr5yr expected inflation, Mexico
Source: Authors’ calculations.
Our model projections indicate that long-term inflation expectations are likely to deviate only modestly from their current level, consistent with the variation of the historical estimates back to 2009. Overall, our findings represent tangible evidence that long-term inflation expectations remain well-anchored in Mexico despite the recent rise in inflation.
Conclusion
Global inflation pressures in the aftermath of the pandemic have raised fears about a sustained increase in the level of inflation around the world, which could be particularly challenging for developing economies with monetary policy guided by an inflation target. In this Letter, to assess this risk for a major emerging economy with an established inflation target, we examine the variation in Mexico’s nominal and inflation-indexed bond prices, while accounting for their respective liquidity risk premiums. This allows us to estimate Mexicanbond investors’ inflation expectations and associated risk premiums. The results reveal that the inflation risk premium has pushed up Mexican BEI rates in recent years, while investors’ long-term inflation expectations have remained stable near the Bank of Mexico’s inflation target despite the rise in inflation.
The policy path needed to keep inflation expectations anchored in a situation with highly elevated inflation may involve tradeoffs. The Bank of Mexico responded early and forcefully to inflation pressures starting in June 2021 and has indicated further tightening of the policy rate would likely be appropriate to bring inflation back down to target over the medium term. This could lower economic growth in Mexico in both 2022 and 2023. On the other hand, history shows that it may be difficult and costly to reverse extended departures from announced inflation targets. Thus, it will be important for central banks with inflation-targeting frameworks to monitor measures of long-term inflation expectations in the current situation.
The provision of financial services and products is undergoing rapid transformation, including through the development of stablecoins, which seek to stabilize the price of a digital currency by linking its value to that of a pool of assets. Stablecoins can potentially serve as a means of payment and store of value, and may contribute to the development of global payment arrangements that are faster, cheaper, and more inclusive. Yet these potential benefits can only be realized if significant risks are addressed. Stablecoin initiatives built on an existing big tech platform with a global customer base may have the potential to scale rapidly, and could pose regulatory and oversight challenges and risks related to consumer protection, fair competition, and the combating of money laundering and terrorism financing, among others, as well as have a significant impact on public policy goals such as financial stability and monetary policy transmission. This paper, written jointly by G7 members, the BIS, and the IMF, including RESMF staff, scopes the causes and implications of the adoption of global stablecoins, and the potential policy efforts to rein in the risks they can bring about.
We study the optimal design of a central bank digital currency (CBDC) in an environment where agents sort into cash, CBDC and bank deposits according to their preferences over anonymity and security; and where network effects make the convenience of payment instruments dependent on the number of their users. CBDC can be designed with attributes similar to cash or deposits, and can be interest-bearing: a CBDC that closely competes with deposits depresses bankcredit and output, while a cash-like CBDC may lead to the disappearance of cash. Then, the optimal CBDC design trades off bank intermediation against the social value of maintaining diverse payment instruments. When network effects matter, an interest-bearing CBDC alleviates the central bank’s tradeoff.
We estimate world cycles using a new quarterly dataset of output, credit and assetprices assembled using IMF archives and covering a large set of advanced and emerging economies since 1950. World cycles, both real and financial, exist and are generally driven by US shocks. But their impact is modest for most countries. The global financial cycle is also much weaker when looking at credit rather than assetprices. We also challenge the view that synchronization has increased over time. Although this is true for prices (goods and assets), this not true for quantities (output and credit). The world business and credit cycles were as strong during Bretton Woods (1950–1972) as during the Globalization period (1984-2006). For most countries, the way their output co-moves with the rest of the world has changed little over the last 70 years. We discuss the reasons behind these new findings and their policy implications for small open economies.
by Nina Biljanovska, Lucyna Gornicka & Alexandros Vardoulakis
An asset bubble relaxes collateral constraints and increases borrowing by credit-constrained agents. At the same time, as the bubble deflates when constraints start binding, it amplifies downturns. We show analytically and quantitatively that the macroprudential policy should optimally respond to building asset price bubbles non-monotonically depending on the underlying level of indebtedness. If the level of debt is moderate, policy should accommodate the bubble to reduce the incidence of a binding collateral constraint. If debt is elevated, policy should lean against the bubble more aggressively to mitigate the pecuniary externalities from a deflating bubble when constraints bind.
by Senay Agca, Deniz O Igan, Fuhong Li & Prachi Mishra
Why do firms lobby? This paper exploits the unanticipated sequestration of federal budget accounts in March 2013 that reduced the availability of government funds disbursed through procurement contracts to shed light on this question. Following this event, firms with little or no prior exposure to the federal accounts that experienced cuts reduced their lobbying spending. In contrast, firms with a high degree of exposure to the cuts maintained and even increased their lobbying spending. This suggests that, when the same number of contractors competed for a piece of a reduced pie, the more affected firms likely intensified their lobbying efforts to distinguish themselves from the others and improve their chances of procuring a larger share of the smaller overall. These findings are stronger in government-dependent sectors and when there is intense competition. The evidence is more consistent with a rent-seeking explanation for lobbying.
by Deniz O Igan, Hala Moussawi, Alexander F. Tieman, Aleksandra Zdzienicka, Giovanni Dell’Ariccia, Paolo Mauro
We track direct public interventions and public holdings in 1,114 financial institutions over the period 2007–17 in 37 countries based on publicly available information. We use aggregate official data to validate this new dataset and estimate the fiscal impact of interventions, including the value of asset holdings remaining in state hands at end-2017. Direct public support to financial institutions amounted to $1.6 trillion ($3.5 trillion including guarantees), with larger amounts allocated to lower capitalized and less profitable banks. As of end-2017, only a few countries had fully divested the initial support they provided during the crisis. Public holdings were divested faster in better capitalized, more profitable, and more liquid banks, and in countries where the economy recovered faster. In countries where the government stake remained high relative to the initial intervention, private investment and credit growth were slower, financial access, depth, efficiency, and competition were worse, and financial stability improved less.
Over the past three decades, the price of machinery and equipment fell dramatically relative to other prices in advanced and emerging market and developing economies. Using cross-country and sectoral data, we show that the decline in the relative price of tangible tradablecapital goods provided a significant impetus to the capital deepening that took place during the same time period. The broad-based decline in the relative price of machinery and equipment, in turn, was driven by the faster productivity growth in the capital goods producing sectors relative to the rest of the economy, and deeper trade integration, which induced domestic producers to lower prices and increase their efficiency. Our findings suggest an additional channel through which rising trade tensions and sluggish productivity could threaten real investment growth going forward.
We study the impact of bankcredit on firm productivity. We exploit a matched firm-bank database covering all the credit relationships of Italiancorporations, together with a natural experiment, to measure idiosyncratic supply-side shocks to credit availability and to estimate a production model augmented with financial frictions. We find that a contraction in credit supply causes a reduction of firm TFP growth and also harms IT-adoption, innovation, exporting, and adoption of superior management practices, while a credit expansion has limited impact. Quantitatively, the credit contraction between 2007 and 2009 accounts for about a quarter of observed the decline in TFP.
by Antonio Fatás, Atish R. Ghosh, Ugo Panizza & Andrea F Presbitero
Governments issue debt for good and bad reasons. While the good reasons—intertemporal tax-smoothing, fiscal stimulus, and asset management—can explain some of the increases in public debt in recent years, they cannot account for all of the observed changes. Bad reasons for borrowing are driven by political failures associated with intergenerational transfers, strategic manipulation, and common pool problems. These political failures are a major cause of overborrowing though budgetary institutions and fiscal rules can play a role in mitigating governments’ tendencies to overborrow. While it is difficult to establish a clear causal link from high public debt to low output growth, it is likely that some countries pay a price—in terms of lower growth and greater output volatility—for excessive debt accumulation.
by Harald Hau, Peter Hoffmann, Sam Langfield & Yannick Timmer
New regulatory data reveal extensive price discrimination against non-financial clients in the FX derivatives market. The client at the 90th percentile pays an effective spread of 0.5%, while the bottom quarter incur transaction costs of less than 0.02%. Consistent with models of search frictions in over-the-counter markets, dealers charge higher spreads to less sophisticated clients. However, price discrimination is eliminated when clients trade through multi-dealer request-for-quote platforms. We also document that dealers extract rents from captive clients and market opacity, but only for contracts negotiated bilaterally with unsophisticated clients.
History is “forever new” and we keep asking “what’s new?” but the past is “forever suggestive” and so we inquire here as to whether the past gives us interesting echoes of the more recent.
Specifically, we juxtapose the “closing of the gold window” in August 1971 (Nixon) and the British gold standard gyrations between 1925 and 1931, when England left gold (i.e., September 1931).
At the time, under Nixon, the U.S. also had an unemployment rate of 6.1% (August 1971) and an inflation rate of 5.84% (1971).
On the afternoon of Friday, August 13, 1971, these officials along with twelve other high-ranking White House and Treasury advisors met secretly with Nixon at Camp David. There was great debate about what Nixon should do, but ultimately Nixon, relying heavily on the advice of the self-confident Connally, decided to break up Bretton Woods by announcing the following actions on August 15:
Nixon directed Treasury SecretaryConnally to suspend, with certain exceptions, the convertibility of the dollar into gold or other reserve assets, ordering the gold window to be closed such that foreign governments could no longer exchange their dollars for gold.
An importsurcharge of 10 percent was set to ensure that American products would not be at a disadvantage because of the expected fluctuation in exchange rates.
Speaking on television on Sunday, August 15, when American financial markets were closed, Nixon said the following:
“The third indispensable element in building the new prosperity is closely related to creating new jobs and halting inflation. We must protect the position of the American dollar as a pillar of monetary stability around the world.
“In the past 7 years, there has been an average of one international monetary crisis every year …
“I have directed Secretary Connally to suspend temporarily the convertibility of the dollar into gold or other reserve assets, except in amounts and conditions determined to be in the interest of monetary stability and in the best interests of the United States.
“Now, what is this action—which is very technical—what does it mean for you?
“Let me lay to rest the bugaboo of what is called devaluation.
“If you want to buy a foreign car or take a trip abroad, market conditions may cause your dollar to buy slightly less. But if you are among the overwhelming majority of Americans who buy American-made products in America, your dollar will be worth just as much tomorrow as it is today.
“The effect of this action, in other words, will be to stabilize the dollar.”
Britain’s own experience in the twenties is explained like this:
“In 1925, Britain had returned to the gold standard.
(editor: This Churchill decision was deeply critiqued by Keynes.)
“When Labour came to power in May 1929 this was in good time for Black Friday on Wall Street in the following October.
“After the Austrian and German crashes in May and July 1931, Britain’s financial position became critical, and on 21st September she abandoned the gold standard.
(Europe of the Dictators, Elizabeth Wiskemann, Fontana/Collins, 1977, page 92-93)
Nixon’s policies gave us the demise of Bretton Woods, while the economic gyrations of 1925-1931 were part of the lead-up to World War II.
The setting is both “infinitely different” across the decades but the feeling of “flying blind” applies to both cases: U.S.A. “closing the gold window,” August 1971 and Britain’s overturning Churchill’s 1925 return to the gold standard, by 1931. One gets the sense of “concealed turmoil” and a lot of “winging it” in both cases. Policy-makers disagreed and they all saw the world of their moments “through a glass, darkly.”